


Citizens Takeout Letter Comparison: Evaluating Private Carriers vs. Florida’s Insurer of Last Resort
What if that unexpected notice from Florida's insurer of last resort isn't a signal of instability, but actually a strategic opportunity to insulate yourself from future state-wide assessments? It's natural to feel a sense of unease when you're told your policy might move to a private company you've never heard of. Most homeowners worry that a shift away from Citizens will lead to aggressive premium hikes after the first year or leave them with a carrier that doesn't have the financial depth to handle a major storm. You deserve a clear, objective way to weigh these risks against the benefits of the private market.
This article provides a rigorous Citizens takeout letter comparison with private carrier Florida alternatives, offering a framework to evaluate the financial health of take-out companies and the nuances of the 20% eligibility rule. We'll examine the specific criteria that determine whether you can stay with Citizens and how to verify that a private carrier has the solvency required for long-term security. We will also analyze how moving to the private market can actually lower your exposure to the hidden costs of state-backed insurance. You'll gain the clarity needed to decide whether to opt out or accept the offer with total confidence in your protection.
Table of Contents
Understanding the Citizens Depopulation Program and Your Takeout Letter
Receiving a takeout letter can feel like an unexpected disruption, but it's actually a formal proposal from a private carrier to assume your policy's liabilities. This process is part of the Florida depopulation program, a legislative effort designed to reduce the state's financial exposure to catastrophic storm events. The Citizens Property Insurance Corporation was established as a safety net, yet its massive growth has created a concentrated risk pool that the state now seeks to diversify. When a private company offers to "take out" your policy, they're essentially betting on the stability of your home's risk profile.
It's vital to act quickly once that envelope arrives. Most notices provide a strict 30-day window for a response. If you don't take action within this timeframe, your policy may be moved automatically. The Florida Office of Insurance Regulation (OIR) acts as a rigorous gatekeeper in this process, vetting every private carrier before they're allowed to participate. They review financial statements, reinsurance structures, and claims-handling history to ensure these companies have the capacity to protect Florida homeowners. A detailed Citizens takeout letter comparison with private carrier Florida options is the first step in determining if this shift serves your long-term financial interests.
The 20% Eligibility Rule Explained
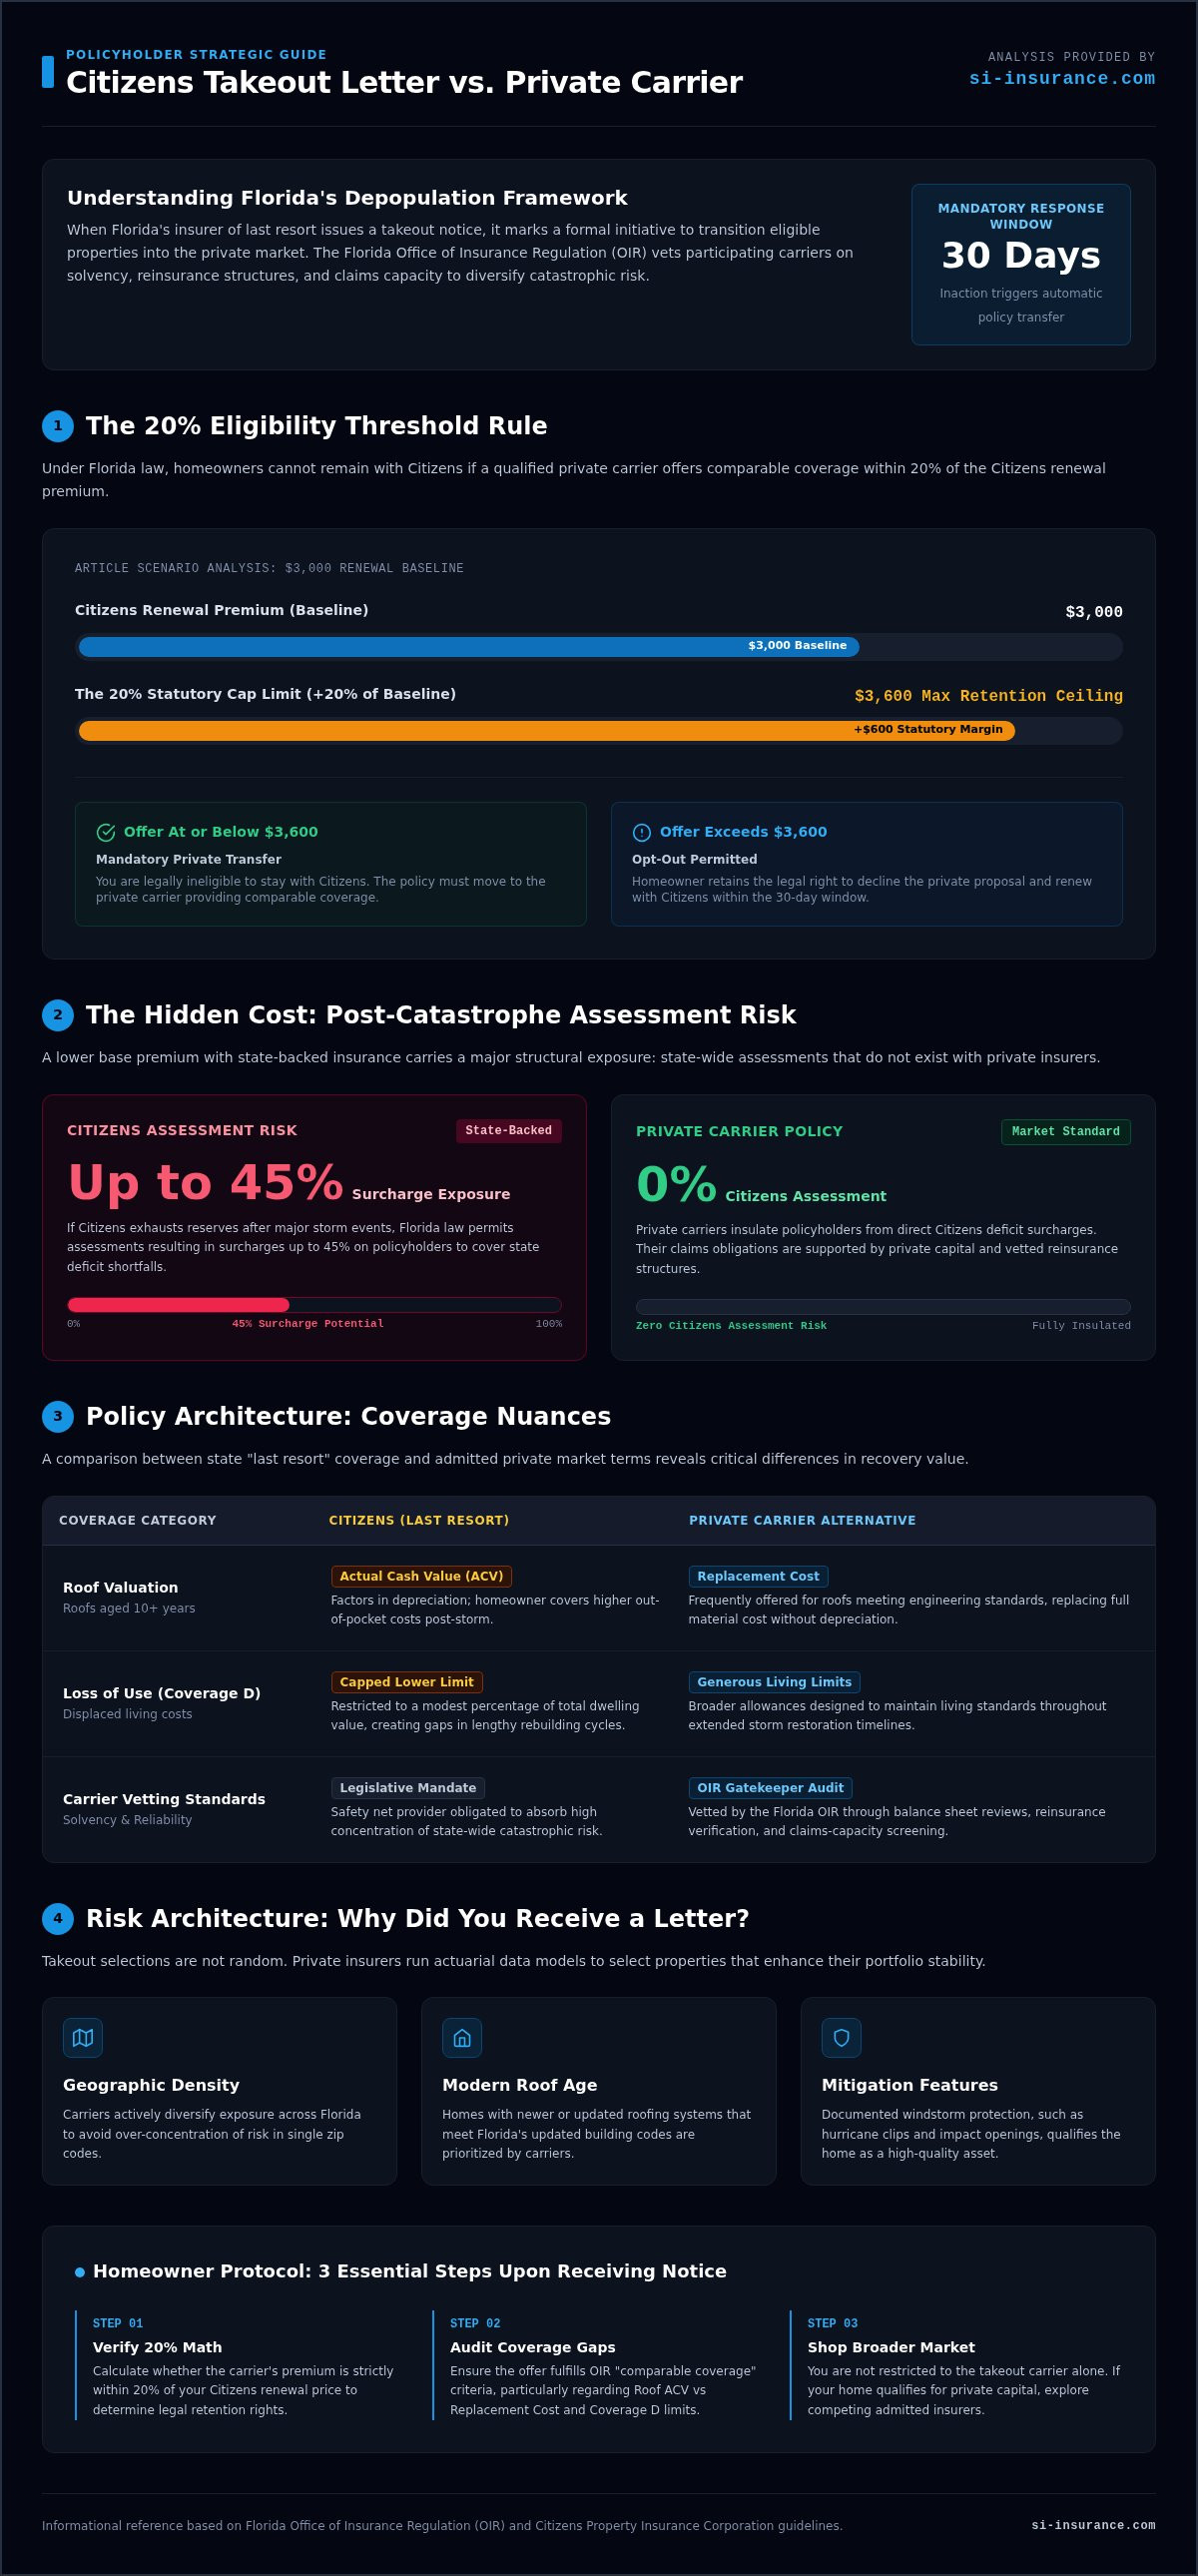
The most significant hurdle for many homeowners is the 20% eligibility threshold. Under Florida law, if a private carrier's premium offer is within 20% of your Citizens renewal premium, you're legally ineligible to remain with the state-backed insurer. For example, if your Citizens renewal is $3,000, any private offer priced at $3,600 or less (excluding fees and assessments) triggers a mandatory move. The OIR mandates that these offers must provide "comparable coverage," meaning the private policy shouldn't leave you with massive gaps in protection just to meet the price point. This rule is designed to push stable risks back into the private market while keeping Citizens as a true last resort.
Why You Received the Letter: Risk Architecture
It isn't a random selection. Private carriers use sophisticated data modeling to identify homes that meet specific risk profiles. They often look for geographic density, meaning they want to avoid having too many policies in a single zip code. They also prioritize homes with modern roof ages and updated mitigation features. If you received a letter, it's actually a strong signal that the private market views your home as a high-quality asset. This interest from private companies is a hallmark of a recovering Florida insurance market in 2026, suggesting that capital is returning to the state to provide more traditional, stable alternatives for well-maintained properties.
Citizens vs. Private Carriers: A Strategic Coverage Comparison
When you begin a Citizens takeout letter comparison with private carrier Florida options, it's essential to look beyond the initial premium quote on the page. Citizens is legally mandated to operate as a "last resort" provider, which often translates to a more restrictive policy structure that lacks the depth of the private market. While a private carrier might offer a higher base price, the true value often lies in the superior coverage limits and specialized endorsements that Citizens simply doesn't provide. For instance, private market policies often include more generous "Loss of Use" (Coverage D) limits, which cover your living expenses if your home becomes uninhabitable. Citizens typically caps this at a lower percentage of the total dwelling value, which can leave a significant financial gap during a long-term reconstruction project after a hurricane.
Another critical differentiator involves how your roof is insured, especially if it's over a decade old. Many private carriers offer Replacement Cost coverage for roofs that meet their specific engineering standards, whereas Citizens might automatically shift older roofs to an Actual Cash Value (ACV) basis. This distinction is vital for your long-term security; ACV factors in depreciation, meaning you could be responsible for a much larger portion of the bill after a storm. Understanding these nuances is part of a strategic risk assessment that helps you avoid expensive surprises down the road when you can least afford them.
Hidden Costs: The Assessment Factor
One of the most misunderstood aspects of the Citizens Depopulation Program is the unique assessment structure that functions as a hidden liability. If Citizens faces a massive deficit after a catastrophic event, they have the legal authority to levy surcharges on their policyholders first. These assessments come in three distinct tiers: Policyholder, Emergency, and Regular. The "Citizens Surcharge" is a potential 15% to 45% premium add-on following a catastrophe. In contrast, private carriers are subject to FIGA assessments, which are generally much lower and spread across all insurance lines in the state, providing a more stable and predictable cost environment for the homeowner.
Endorsement Availability and Flexibility
Private carriers win on flexibility by offering endorsements that Citizens intentionally omits to keep its rates artificially low. You can often add protection for water backup, identity theft, or scheduled personal property like jewelry or fine art that requires specific valuation. These are not just "extras"; they're essential components of a comprehensive Home Insurance in Florida strategy for sophisticated owners. If you have specific high-value needs or unique property features, the private market is almost always the better fit because it allows for a tailored approach that a state-backed entity simply isn't designed to match.
Financial Solvency: Evaluating Private Carrier Stability in 2026
The fear that a private carrier might collapse following a major hurricane is the primary deterrent for many homeowners considering a move. It's a valid concern given the historical volatility of the Florida market. However, the regulatory landscape in 2026 is governed by stringent capital requirements that didn't exist in previous cycles. The Florida Office of Insurance Regulation (OIR) subjects every participant in the depopulation program to rigorous stress tests. These companies must prove they have enough liquid capital and reinsurance to handle a 1-in-100-year storm without compromising their ability to pay claims.
Reinsurance is the invisible backbone of the private market, acting as a global safety net that offloads risk to international financial markets. When you perform a Citizens takeout letter comparison with private carrier Florida alternatives, you're evaluating a company that has secured massive layers of this "insurance for insurance companies." This structure ensures that claim payments aren't solely dependent on the carrier's local bank account. Instead, they're backed by global capital, providing a level of protection that is often more sophisticated than the state-backed risk pool.
Demotech vs. A.M. Best Ratings
Financial strength ratings offer an objective window into a carrier's long-term health. Demotech ratings are common among Florida-based carriers, where an 'A' rating indicates a high probability of maintaining solvency during catastrophic events. A.M. Best remains the global standard for national carriers entering the region. At SI Insurance, we conduct deep-dive audits of these ratings and the underlying reinsurance treaties. We ensure that any carrier we recommend has the institutional strength to meet its obligations, regardless of the season's severity.
The FIGA Safety Net
If a private carrier were to fail, the Florida Insurance Guaranty Association (FIGA) provides a final layer of protection for policyholders. FIGA guarantees that valid claims are paid up to $300,000 per policy, which offers a critical floor of security. This is fundamentally different from the solvency model used by Citizens. While Citizens relies on its statutory power to tax nearly every insurance policyholder in the state to cover deficits, the private market operates on a model of pre-funded capital and international risk-sharing. This makes the private market a more stable environment for those who wish to avoid the threat of statewide emergency assessments.
5-Step Checklist for Evaluating Your Takeout Offer
A Citizens takeout letter comparison with private carrier Florida options requires more than a glance at the bottom line. You must verify that the proposed policy doesn't compromise your security for a marginal price difference. Follow this structured approach to evaluate your offer before the response window expires.
Step 1: Calculate the Premium Gap. Determine if the private offer is within 20% of your Citizens renewal premium. If it's below this threshold, your eligibility to stay with Citizens is legally terminated.
Step 2: Review Coverage 'A' (Dwelling) Limits. Ensure the private carrier hasn't reduced your dwelling coverage to lower the premium. It must reflect current 2026 reconstruction costs in your specific Florida county.
Step 3: Compare Deductibles. Look closely at the Hurricane and All Other Perils (AOP) deductibles. A lower premium is a poor trade-off if it comes with a 5% hurricane deductible that you can't afford to pay after a storm.
Step 4: Research Claims Reputation. Consult the Florida Office of Insurance Regulation's consumer complaint index. This data provides an objective look at how the carrier treats policyholders during the claims process.
Step 5: Verify the Opt-Out Deadline. Most offers have a strict 30-day window. Mark this date clearly; once it passes, your policy is assumed by the private market automatically.
How to Properly Opt-Out
If you choose to decline the offer, you must use the designated online portal or return the mail-in form provided in your notice. It's vital to remember that doing nothing is equivalent to saying yes. Your Agent of Record plays a pivotal role here. They can facilitate the opt-out process and ensure your decision is recorded correctly within the Citizens system. If you miss this deadline, the transition happens by default, and you'll be bound by the terms of the private carrier's policy.
When to Say 'Yes' to the Takeout
There are many scenarios where moving to the private market is the superior strategic move. Private carriers often offer significant bundling opportunities with your auto or umbrella policies, which can lead to overall household savings. They also typically provide much higher limits for water damage, whereas Citizens often caps this coverage at a mere $10,000. Homeowners with high-value assets should prioritize the broader liability protection of private carriers over the base premium of Citizens. If the takeout company is well-capitalized, the move can offer a more stable long-term environment. To get a professional second opinion on your offer, contact SI Insurance for a side-by-side policy analysis.
Navigating the Transition with SI Insurance
Receiving a takeout notice isn't just about managing paperwork; it's a pivot point for your household's financial security. At SI Insurance, we perform a granular side-by-side analysis to ensure your transition doesn't result in hidden coverage gaps. Our approach goes beyond the surface level of the premium quote. We scrutinize the carrier's claims-handling history and their underlying financial architecture to provide you with a clear, objective recommendation. This level of sophisticated risk engineering is essential for Florida families who value long-term stability over short-term savings.
One of the most significant advantages of an independent partnership is our ability to shop for a "third option." While the takeout company in your letter was vetted by the state, they might not be the most competitive or robust choice available in the open market. We represent over 30 Florida carriers, allowing us to perform a Citizens takeout letter comparison with private carrier Florida across the entire landscape. If a more stable or cost-effective alternative exists, we'll find it for you. This objective stance ensures your loyalty remains with your own financial interests rather than a specific insurance corporation.
An independent agent acts as your long-term advocate. Insurance carriers often change their risk appetites and rates annually; we stay with you, managing renewals and providing a steady hand if you ever need to file a claim. Our commitment to protecting Broward County homeowners is rooted in a deep understanding of the local market's unique challenges and opportunities.
Beyond the Letter: A Holistic Risk Review
A takeout notice serves as an ideal catalyst for a broader evaluation of your protection. It's often the perfect time to review your Flood Insurance, especially as state requirements for Citizens policyholders continue to shift. Additionally, moving to the private market often unlocks significant discounts when you bundle your home and Auto Insurance. Our teams in Sunrise and Pompano Beach are ready to sit down with you for a personalized strategy session that looks at your entire risk portfolio, ensuring every asset is shielded correctly.
Request Your Strategic Comparison Today
Don't let the 30-day response window close without a professional audit of your options. We invite you to send us your takeout letter for a complimentary, sophisticated coverage audit. Our local presence in Sunrise and Pompano Beach means we understand the specific market nuances of South Florida better than a distant call center representative ever could. We're committed to providing the elite expertise you need to make an informed decision for your family. Contact SI Insurance for a Takeout Offer Review today and take control of your insurance future with confidence.
Securing Your Florida Home’s Financial Future
Deciding the future of your property’s protection requires a blend of technical data and strategic foresight. While the 20% rule often dictates your legal eligibility, the true value of a private carrier lies in superior coverage limits and the absence of high-tier Citizens assessments. By performing a comprehensive Citizens takeout letter comparison with private carrier Florida options, you move from being a policyholder in a state-backed pool to a client with a tailored risk management strategy.
Our team at SI Insurance acts as your expert guide, leveraging our independent status to vet over 30 carriers and analyze complex solvency ratings from Demotech and A.M. Best. We specialize in personalized risk management for Broward County homeowners, ensuring your transition is both secure and advantageous. Don't let the 30-day window close without a professional audit of your offer.
Request a Professional Takeout Offer Comparison today to ensure your home remains protected by the most stable and comprehensive coverage available. You’ve worked hard for your home; let's make sure your insurance works just as hard for you.
Frequently Asked Questions
Do I have to accept the Citizens takeout offer?
You aren't strictly forced to accept every offer, but your ability to decline depends on the premium price gap. If the private carrier's quote is more than 20% higher than your Citizens renewal, you can choose to stay with the state-backed insurer. However, if the offer falls within that 20% threshold, Florida law requires you to move. It's vital to submit your opt-out request through the official portal before the 30-day deadline expires.
What is the 20% rule for Citizens insurance in 2026?
The 20% rule is a legislative mandate designed to reduce the state's risk by moving stable policies back into the private market. If a vetted private company offers a premium that is within 20% of your estimated Citizens renewal, you lose your eligibility to remain with the insurer of last resort. Understanding this rule is a core part of any Citizens takeout letter comparison with private carrier Florida analysis, as it determines your legal options for coverage.
Is Citizens Property Insurance cheaper than private carriers?
While Citizens often presents a lower base premium, it isn't always the most cost-effective solution when you factor in total risk. Citizens policyholders face unique "assessment risks" that can add surcharges of up to 45% to your bill after a major storm deficit. Private carriers often provide more competitive rates when you bundle home and auto insurance; they also typically include much higher limits for common issues like water backup and mold damage.
What happens if I ignore the Citizens takeout letter?
Ignoring the notice is functionally the same as accepting the offer. If you don't take action within the 30-day window specified in your letter, your policy will be automatically assumed by the private carrier on the effective date. This means your coverage and billing will transition to the new company without any further input from you. It's always better to review the carrier's financial stability with a professional before this transition happens by default.
Are private insurance companies in Florida financially stable?
Florida's regulatory landscape in 2026 is designed to ensure that every participating private carrier has the capital to survive a 1-in-100-year storm. These companies rely on global reinsurance treaties to offload catastrophic risk, providing a layer of security that local reserves alone cannot offer. Additionally, the Florida Insurance Guaranty Association (FIGA) acts as a safety net, protecting policyholders up to $300,000 per claim if a carrier were to face insolvency after a major event.
Can I switch to a different private carrier instead of the one in the takeout letter?
You are not restricted to the specific company mentioned in your takeout notice. If you're being moved out of Citizens, it's often the perfect time to shop the entire private market for a better deal or more comprehensive coverage. At Si Insurance Agency, we can compare the takeout offer against 30 other carriers to see if a different provider offers a better bundling discount or more robust endorsements for your specific property in Broward County.
Will my premium increase after the first year with a private takeout carrier?
Private carriers must adhere to rate filings approved by the Florida Office of Insurance Regulation, so they can't arbitrarily spike your premium without cause. While rates can fluctuate based on market conditions or your home's age, you aren't trapped after the first year. You retain the right to shop for new coverage at every renewal. Working with an independent agent ensures that if your current carrier raises rates significantly, we can quickly move your policy.
Does a private carrier offer better coverage than Citizens?
Most private carriers offer significantly broader protection than the basic "last resort" policies provided by Citizens. You'll often find higher limits for "Loss of Use" and water damage, along with options for identity theft and scheduled personal property. When performing a Citizens takeout letter comparison with private carrier Florida options, most homeowners find that the private market's ability to tailor endorsements provides a much higher level of absolute security for their high-value assets and unique lifestyle needs.
Comments