


12 Strategic Ways to Reduce Car Insurance Costs in Florida for 2026
What if the very technology designed to monitor your every turn is actually the most powerful tool you have to reclaim control over your financial future? Many drivers across South Florida feel a growing sense of unease as they face unpredictable premium hikes and the complexities of AI-driven pricing models. It's a frustrating reality, especially when you want to ensure your family remains protected in our unique legal environment. We understand that finding a balance between elite protection and cost efficiency requires more than just a basic search for quotes.
We've developed this guide to provide you with 12 strategic ways to reduce car insurance costs 2026 without sacrificing the essential coverage you rely on. You'll discover how to leverage modern telematics, identify overlooked Florida-specific credits, and utilize the analytical power of an independent agent to optimize your policy. We're moving beyond generic advice to offer a sophisticated look at how the 2026 market functions. By following these expert-level strategies, you'll gain the clarity and confidence needed to secure a policy that reflects both your high standards and your commitment to smart risk management.
Table of Contents
The 2026 Florida Insurance Landscape: Understanding Modern Cost Drivers
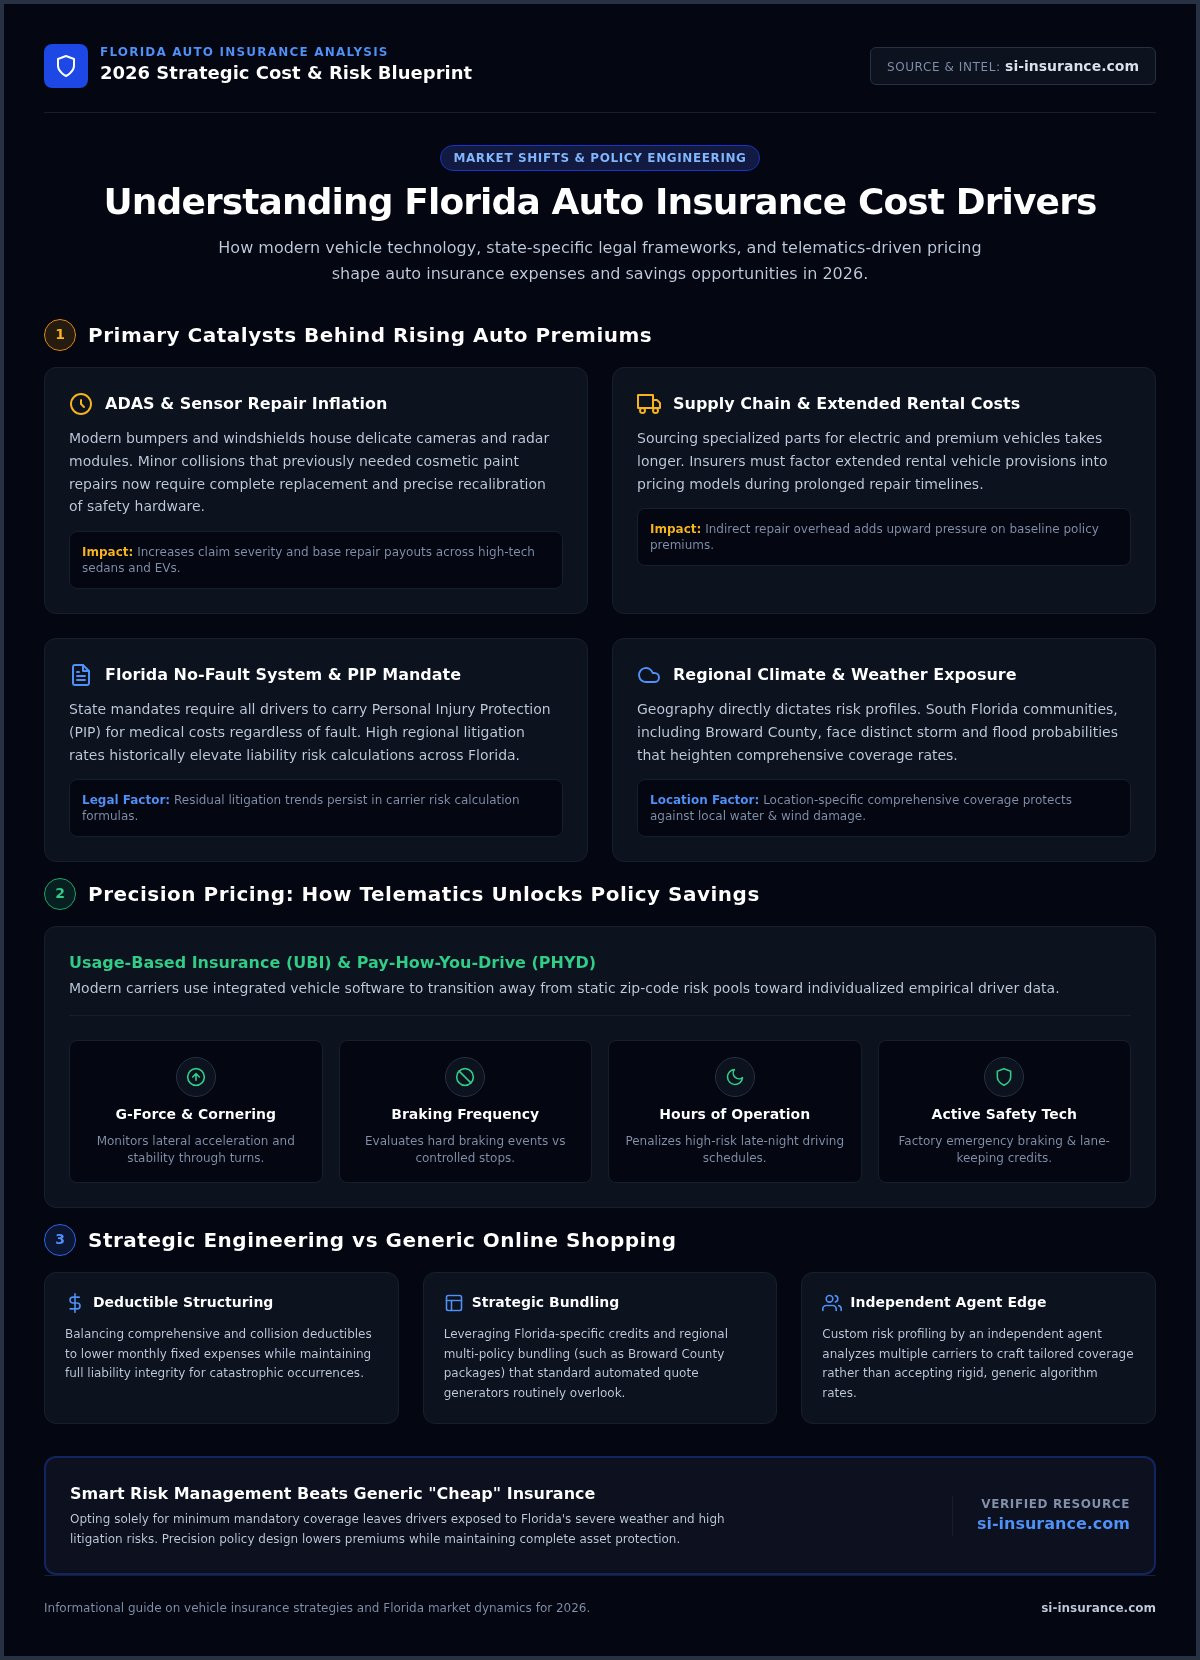
The insurance market in Florida has evolved into a complex ecosystem where traditional risk assessment meets high-tech reality. Understanding why your premiums look the way they do is the first step in identifying ways to reduce car insurance costs 2026. It isn't just about how you drive; it's about what you drive and where you park it. In South Florida, we deal with a unique intersection of heavy traffic, sophisticated vehicles, and environmental factors that demand a more nuanced approach to coverage than ever before.
Technological Complexity and Repair Inflation
Advanced Driver Assistance Systems (ADAS) have fundamentally shifted premium pricing because the sophisticated sensors and cameras integrated into modern bumpers and windshields significantly increase the financial liability of every collision. A minor fender-bender that once required a simple paint touch-up now often involves replacing and recalibrating expensive radar modules. These components are essential for safety, yet their vulnerability drives up repair totals. Additionally, the 2026 supply chain remains sensitive; specialized parts for electric vehicles and high-end sedans can take longer to source, leading to extended rental car costs that insurers must account for in their pricing structures. This means even if you're a safe driver, the vehicle you choose carries its own inherent cost profile.
Florida’s Regulatory Influence on Your Wallet
The legal framework governing vehicle insurance in the United States varies by state, and Florida’s specific mandates play a major role in your policy's cost. Our state relies on a "No-Fault" system, requiring every driver to carry Personal Injury Protection (PIP) to cover their own medical expenses regardless of who caused the accident. While this aims to speed up claims processing, the high rate of litigation in Florida often pushes liability costs higher for everyone. Recent state-level reforms have attempted to stabilize the market, but the residual impact of past legal trends continues to influence how carriers calculate risk in your monthly bill.
Geography also dictates your financial profile. In Broward County, the risk of flood damage or storm-related incidents is a constant factor in comprehensive coverage pricing. This is where the distinction between "cheap" and "strategic" insurance becomes vital. Opting for the lowest possible price often leaves you exposed to these regional risks. Instead, finding ways to reduce car insurance costs 2026 involves engineering a policy that utilizes local credits and high-level risk management to lower costs while keeping your protection airtight. We focus on finding that balance so you don't have to choose between a fair price and the security your family deserves.
Leveraging Telematics and AI: Data-Driven Savings Strategies
The transition from generalized risk pools to individualized assessment has reached its peak in 2026. One of the most effective ways to reduce car insurance costs 2026 is by demonstrating your specific safety profile through telematics. Instead of being judged solely by your zip code or age, you can now provide carriers with empirical evidence of your responsibility behind the wheel. This shift toward Usage-Based Insurance (UBI) means your premium is no longer a static figure but a dynamic reflection of your daily habits. For many drivers in Sunrise and Pompano Beach, finding ways to reduce car insurance costs 2026 involves more than just shopping around; it requires embracing the data your car already collects.
The Rise of Precision Pricing
Pay-How-You-Drive (PHYD) models have evolved beyond the rudimentary plug-in devices of the past. Modern carriers utilize integrated vehicle software to monitor nuanced metrics such as G-force during cornering, the frequency of hard braking events, and the specific hours of operation. AI-driven algorithms process these data points to construct a predictive risk profile, essentially calculating the probability of a future claim based on your current tendencies. By maintaining a steady hand and avoiding high-risk behaviors like late-night driving, you position yourself for significant premium reductions that traditional policies simply can't offer.
Integrated Safety System Discounts
Your vehicle's factory-installed technology acts as a secondary layer of financial mitigation. Beyond just protecting you during a crash, active safety features like automatic emergency braking and lane-keeping assistance actively prevent incidents, which insurers reward with lower comprehensive and liability rates. It's vital to distinguish between passive features, such as airbags, and active systems that intervene in real-time. We recommend verifying your vehicle's specific technical specifications with a professional to ensure every available credit is applied to your account. For more general advice on policy optimization, you can review these Insurance Information Institute tips for reducing car insurance costs.
Navigating the data-sharing agreements of 2026 requires a careful balance between privacy and profit. While some drivers remain hesitant to share their telemetry, the financial incentives are becoming increasingly difficult to ignore. Most modern agreements are transparent about how data is used to calculate risk without compromising your personal identity. If you're unsure which telematics program aligns with your needs, consulting with an independent agent can help you evaluate which carriers offer the best rewards for your specific driving profile. This personalized approach ensures you aren't just another data point in an algorithm, but a valued client with a custom-engineered risk strategy.
Strategic Policy Structuring: Balancing Deductibles and Liability
Building an insurance policy that withstands the economic pressures of 2026 requires a meticulous look at your coverage structure. It's one of the most direct ways to reduce car insurance costs 2026 without leaving yourself exposed to financial ruin. We often see drivers focus solely on the monthly premium, yet the real value is found in the balance between what you pay now and what you're prepared to pay in the event of a loss. A sophisticated policy isn't just a bill; it's a carefully engineered financial safety net.
Optimizing Deductibles for Long-Term Liquidity
Adjusting your deductible is a classic lever for premium control, but it requires a calculated approach to your personal liquidity. Increasing a deductible from $500 to $1,000 can result in meaningful annual savings, provided you have the cash reserves set aside to cover that higher threshold after an incident. In high-density areas like Sunrise and Pompano Beach, where traffic congestion increases the statistical likelihood of minor collisions, we recommend choosing a deductible that reflects your actual risk tolerance and monthly budget. It's about finding that 'break-even' point where the premium savings outweigh the potential out-of-pocket risk over a three-to-five-year period.
For vehicles that have depreciated significantly, maintaining collision and comprehensive coverage may no longer be economically viable. If the annual cost of these specific protections exceeds 10 percent of the vehicle's actual cash value, it's often a signal to drop those coverages. This strategic shift ensures your premium dollars are protecting your most valuable assets, like your home and savings, rather than an aging vehicle with a diminishing replacement value.
Right-Sizing Your Liability Portfolio
While state minimums might seem like an easy way to save, they're rarely sufficient for Florida homeowners who have significant equity to protect. In our litigious environment, a single accident can lead to claims that far exceed basic coverage levels. We explore these nuances deeply in our Florida Auto Insurance Strategic Guide, which outlines how to structure your limits for maximum security. Balancing the cost of higher limits against the risk of personal litigation is a hallmark of elite risk management.
Finally, don't overlook Uninsured Motorist (UM) coverage. Florida continues to see a high percentage of drivers operating without adequate insurance, making UM an essential component of a sophisticated risk plan. It's another one of the vital ways to reduce car insurance costs 2026 in the long run; preventing a single out-of-pocket medical catastrophe far outweighs the modest cost of the premium. By focusing on these high-level structures, you ensure your policy serves as a true financial safeguard for your family's future.
Maximizing Florida-Specific Discounts and Credits
Local knowledge often serves as the most effective catalyst for premium reduction. While national carriers utilize broad data sets, identifying the specific ways to reduce car insurance costs 2026 in Florida requires a more localized lens. You'll find that our state offers a variety of specialized credits that are frequently overlooked by generic online quote engines. These savings aren't just minor adjustments; they're rewards for your professional background, your academic history, and your proactive commitment to road safety.
The Power of the Bundle in South Florida
Bundling your auto policy with Home Insurance creates a 'loyalty' discount that reflects your stability as a client. For residents in Sunrise and Pompano Beach, this strategic alignment simplifies financial management by consolidating risk under a single agency. Condo owners and renters also find significant value here, as the combined premium is typically lower than maintaining separate policies with disconnected providers. It's an efficient way to demonstrate your total risk profile while securing a more competitive rate across all your assets.
Defensive Driving and Education Credits
Education remains a powerful tool for cost mitigation. Florida DHSMV-approved defensive driving courses provide a direct path to lower premiums, particularly for those looking to offset the impact of minor traffic infractions. Families with students attending university more than 100 miles from home can leverage 'student-away-at-school' credits, which acknowledge the reduced vehicle usage during the semester. Additionally, residents over the age of 55 are eligible for the 'Mature Driver' discount after completing a state-recognized safety program; it's a recognition of the experience and caution typical of this demographic.
Maintaining a clean record within Florida’s points system is perhaps the most sustainable of the many ways to reduce car insurance costs 2026. Carriers reward drivers who avoid the accumulation of points, viewing them as lower-risk assets in a complex driving environment. Don't overlook the impact of professional affiliations either. Educators, first responders, and members of certain academic organizations often qualify for specialized credits that standard algorithms might ignore. These nuanced details are exactly what we look for when engineering your coverage.
To ensure you're capturing every available regional credit and not leaving money on the table, consult with our independent agents today for a tailored policy review that prioritizes your unique financial goals.
The Independent Agency Advantage: Engineering a Custom Risk Profile
While digital platforms often promise immediate results, they frequently lack the contextual intelligence necessary to navigate the complexities of the 2026 Florida market. An algorithm can identify a price point, but it cannot understand the specific nuances of your financial goals or the unique risks associated with your lifestyle in Broward County. Choosing an independent agency means you're no longer restricted to the rigid underwriting of a single carrier. We operate as your dedicated consultant, leveraging our access to a wide network of providers to ensure that your coverage is both comprehensive and cost-effective.
One of the most effective ways to reduce car insurance costs 2026 is to foster a competitive environment where multiple carriers vie for your business. Because we aren't beholden to one brand, we can pivot your coverage as market conditions change, ensuring you always benefit from the most favorable rates available. This methodology transforms insurance from a static expense into a dynamic, engineered asset that evolves alongside you. It's a professional partnership built on the foundation of long-term security and intellectual confidence.
Local Expertise in Sunrise and Pompano Beach
Our presence in Sunrise and Pompano Beach gives us a distinct advantage in understanding the specific environmental and economic pressures facing our clients. From assessing the flood risks of specific neighborhoods to understanding the traffic density of local corridors, our local expertise allows us to refine your risk profile with precision. We believe that a physical office in Broward County provides a level of accountability and claim support that a global call center simply cannot match. It's about being a present, reliable guardian for your assets, tailoring policies specifically for Florida's unique economic climate.
The Strategic Review Process
We recommend against allowing any policy to auto-renew without a meticulous professional audit. Life doesn't stand still, and several life events can trigger significant new savings opportunities:
Asset Acquisition: Purchasing a new home or a vehicle with updated safety features.
Lifestyle Shifts: Changes in marital status or professional affiliations.
Usage Changes: A transition to remote work or a significantly shorter daily commute.
Our annual portfolio reviews are designed to capture these shifts, ensuring your policy remains perfectly aligned with your current reality while uncovering new ways to reduce car insurance costs 2026. To begin refining your coverage, we invite you to Schedule a consultation with SI Insurance. We'll work together to ensure your insurance portfolio is a testament to both security and strategic foresight.
Securing Your Financial Future on Florida's Roads
Mastering the intricacies of the 2026 insurance market requires a blend of technological adoption and meticulous planning. We've explored how leveraging telematics and right-sizing your liability limits are essential ways to reduce car insurance costs 2026 while maintaining a robust safety net. By identifying Florida-specific credits and avoiding the pitfalls of auto-renewal without a professional audit, you position yourself as a calculated participant in a challenging financial landscape.
At Si Insurance Agency, we act as your professional guardian, utilizing our local expertise in Sunrise and Pompano Beach to match you with top-tier carriers. Our independent model is built on the belief that your protection should be as unique as your lifestyle. We're committed to the premium optimization and rigorous risk management you deserve. It's time to ensure your policy reflects your standards of excellence and your commitment to long-term stability.
Ready to refine your coverage? Please Request a Strategic Auto Insurance Audit from Si Insurance Agency today. We're here to help you move forward with absolute security and confidence.
Frequently Asked Questions
Is it better to have a higher deductible or higher monthly premium in Florida?
Generally, a higher deductible reduces your premium, which is a key way to reduce car insurance costs 2026. It's best for drivers with liquid savings who can cover the out-of-pocket cost after an accident. If your budget is tight month-to-month, a lower deductible provides more stability. We recommend analyzing your cash reserves before committing to a high-deductible strategy in Broward County's high-traffic environment. This ensures your risk management remains both practical and sustainable.
Can I get a discount for taking a defensive driving course in Broward County?
Yes, completing a Florida DHSMV-approved defensive driving course typically results in a mandatory premium reduction for several years. This is especially beneficial for mature drivers or those looking to remove points from their license. It's a proactive method to demonstrate your commitment to safety. You should verify with your agent that the specific course you've chosen is recognized by your current carrier to ensure the credit is applied correctly.
How does my credit score affect my car insurance rates in Florida in 2026?
Carriers in Florida utilize credit-based insurance scores to help predict the likelihood of future claims. A higher credit score often correlates with lower premiums because insurers view these individuals as lower risk. If you're looking for ways to reduce car insurance costs 2026, improving your credit standing can have a measurable impact on your long-term rates. It’s one of many variables that independent agencies analyze when matching you with a network of carriers.
Does bundling home and auto insurance really save money in South Florida?
Bundling remains one of the most effective strategies for premium optimization in South Florida. By placing your home and auto policies with the same carrier, you often qualify for a multi-policy discount that reduces the cost of both. This approach also simplifies your risk management by centralizing your coverage under a single agency. For residents in Sunrise and Pompano Beach, it's a sophisticated way to leverage your total asset portfolio for better rates.
What is the 'Good Student' discount, and how do I qualify for it in Florida?
The 'Good Student' discount is a credit offered to full-time students who maintain a high grade point average, usually a 3.0 or better. Carriers view academic success as an indicator of responsibility and lower driving risk. To qualify in Florida, you'll typically need to provide recent transcripts or a dean's list letter to your agent. It’s a significant way to offset the higher premiums often associated with younger drivers in the household.
How often should I shop around for a new car insurance quote?
We recommend a professional audit of your insurance portfolio at least once every twelve months or whenever a major life event occurs. Relying on auto-renewals can lead to missed savings as market conditions and carrier appetites shift. An annual review ensures that your coverage evolves with your lifestyle and vehicle technology. Partnering with an independent agent allows you to compare multiple carriers efficiently without the need for repetitive manual searches.
What happens if I don't have enough insurance in a high-litigation state?
Operating with insufficient coverage in a litigious environment like Florida exposes your personal assets to significant risk. If a judgment exceeds your policy limits, your savings, home equity, and future earnings could be targeted to satisfy the debt. This is why state minimums are rarely enough for established residents. We focus on engineering policies that provide a protective barrier, ensuring your financial security remains intact even during complex legal disputes.
Can telematics data be used against me in the event of an accident?
While telematics data is primarily used to reward safe habits, it creates a digital record of your vehicle's movements and speeds. In some legal scenarios, this data could be subpoenaed to determine fault or verify your actions during a collision. However, most drivers find that the benefits of precision pricing and significant discounts outweigh these concerns. It’s important to review your data-sharing agreement to understand exactly how your information is stored and utilized.
Comments