


Affordable Auto Insurance in Broward County: The Complete 2026 Guide
The cheapest car insurance policy in South Florida often turns out to be the most expensive purchase a driver can make after a crash. If you've spent any time searching for seguro de auto barato en Broward, you know firsthand how frustrating it feels to watch monthly premiums climb while trying to keep your family protected. It's completely understandable to want immediate relief for your budget, but stripping away essential coverages just to save a few dollars can leave your hard-earned savings completely exposed on crowded corridors like I-95.
You don't have to choose between keeping your household expenses manageable and staying properly protected behind the wheel. In this guide, you'll discover how to secure dependable, low-cost car insurance across Broward County without sacrificing vital legal or financial protections. We'll unpack how neighborhood factors from Fort Lauderdale to Sunrise influence your rates, clarify what Florida's no-fault rules actually require, and share practical ways to unlock legitimate discounts with personalized support from an independent local agency.
Table of Contents
Understanding Auto Insurance Rates in Broward County: What Drives Your Costs?
Florida Auto Insurance Essentials: Minimum Requirements vs. Real Protection
Practical Strategies to Lower Your Car Insurance Premium Without Losing Coverage
Captive Agents vs. Independent Brokers: Finding the Best Value in Broward
Understanding Auto Insurance Rates in Broward County: What Drives Your Costs?
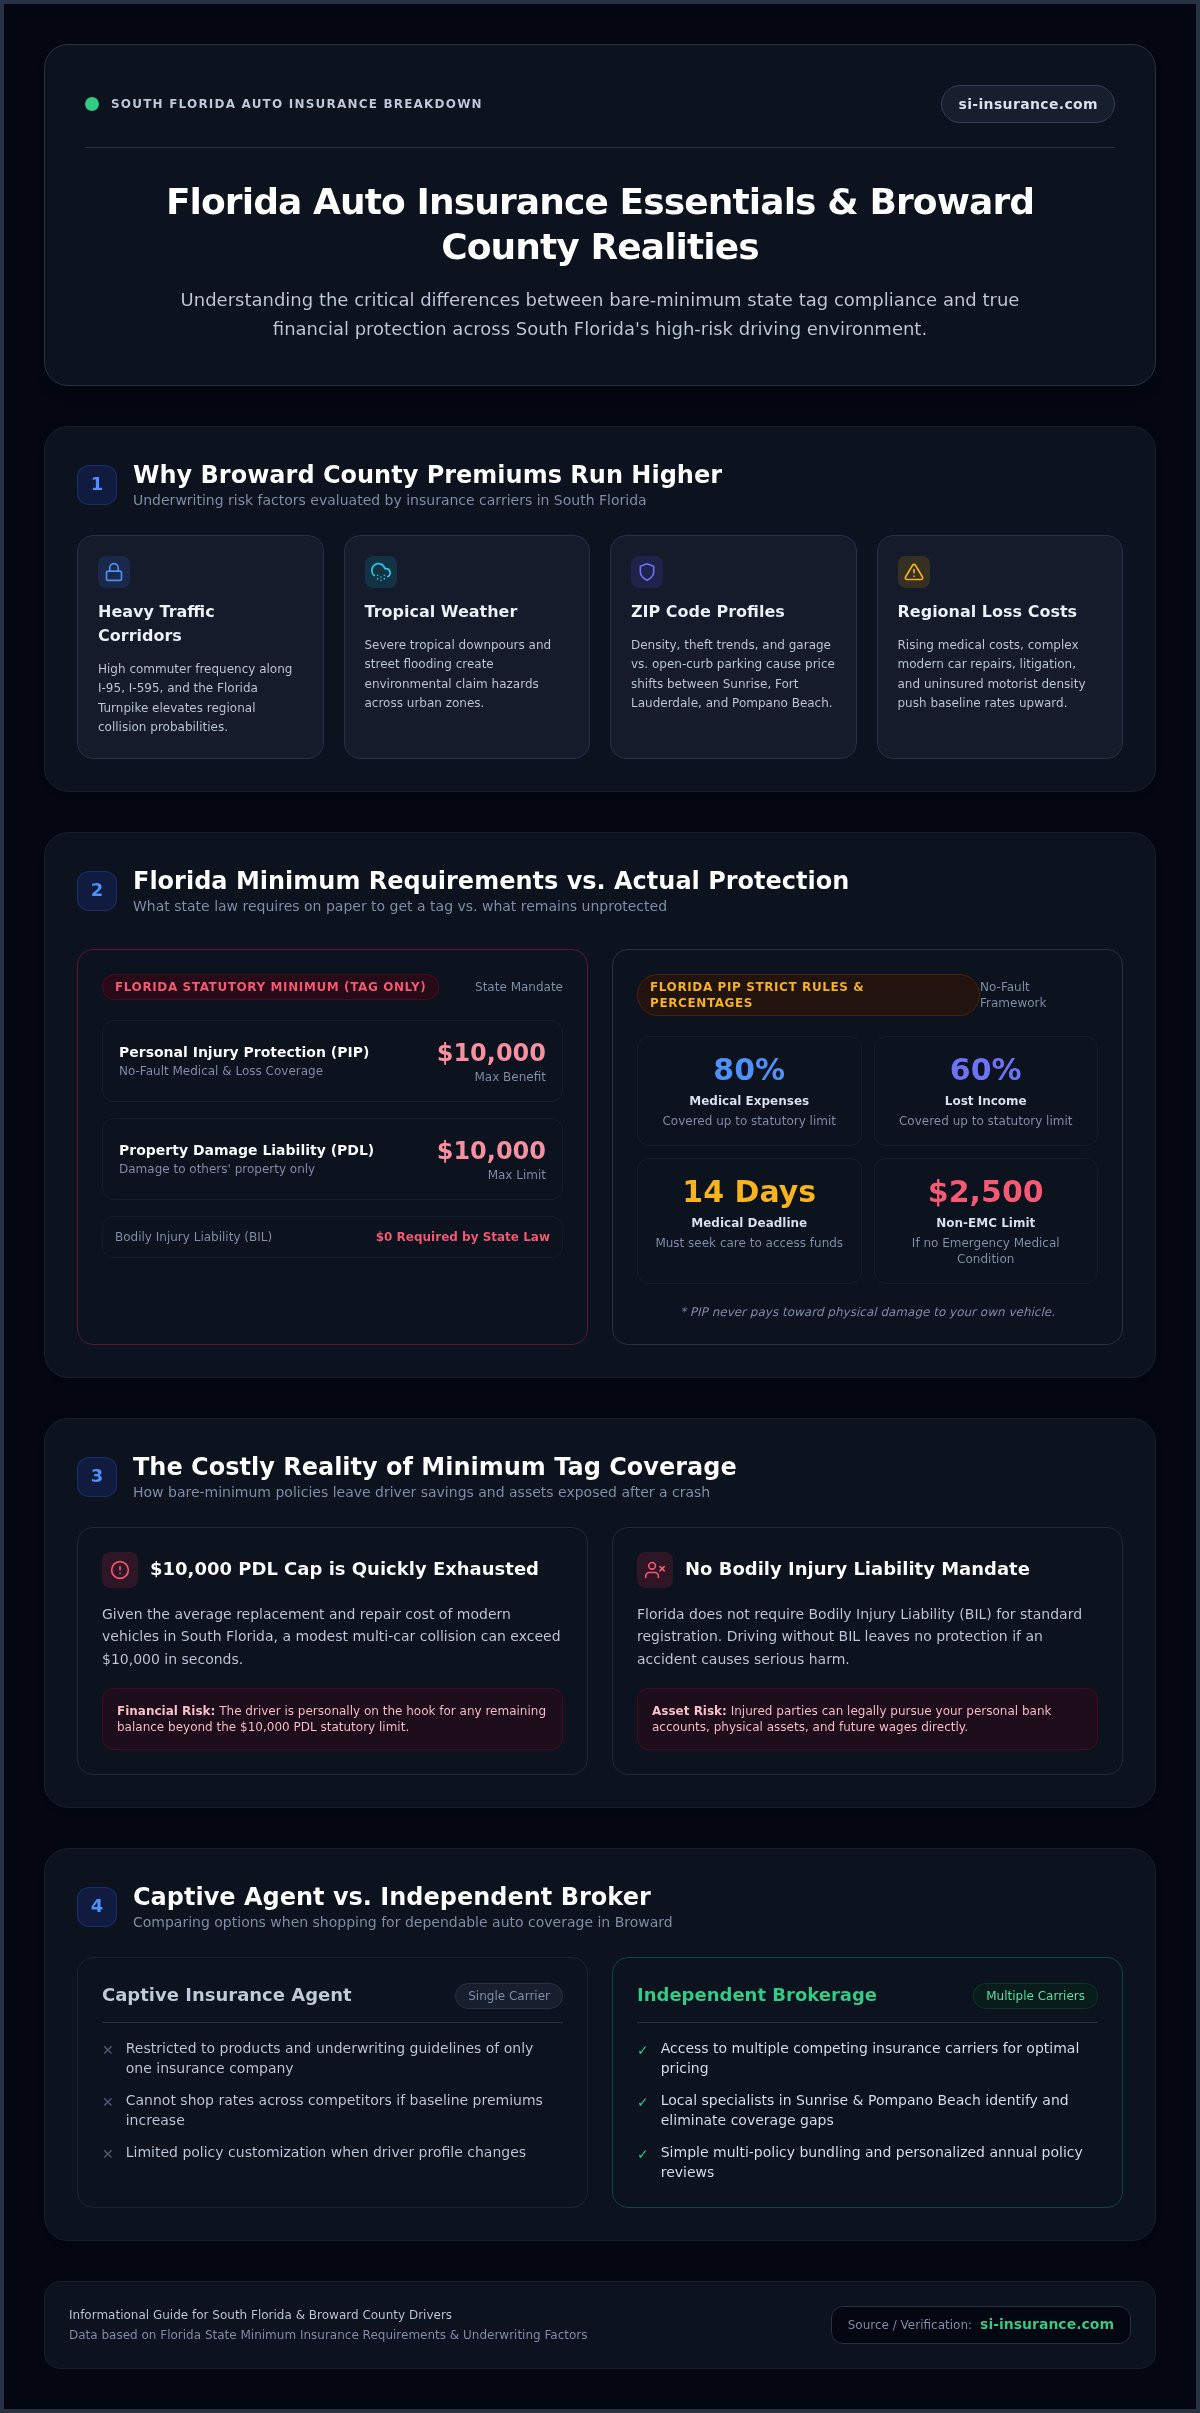
Living in South Florida means dealing with busy highways and intense weather, but it also means dealing with some of the highest premium benchmarks in the state. When drivers start searching for seguro de auto barato en Broward, they quickly discover that insurance carriers evaluate this market under a completely different lens than other parts of Florida. Between frequent claims along major thoroughfares, high regional repair expenses, and heavy tropical downpours that cause localized street flooding, local risk profiles force baseline prices upward.
Actuarial risk models assess multiple overlapping variables. As outlined in standard overviews of seguros de auto en los Estados Unidos, underwriting formulas consider not just state minimum frameworks, but also how environmental factors, regional claim litigation, and high concentrations of uninsured motorists impact baseline loss ratios. When an insurer writes a policy in our county, they prepare for those community-wide expenses.
To see how these moving parts shape what you pay and learn how to reduce those costs, take a look at this helpful guide:
The Impact of South Florida Traffic and Claim Frequencies
Arterial roadways like I-95, I-595, and the Florida Turnpike stay jammed with constant commuter movement and seasonal traffic. Heavy congestion around Fort Lauderdale and Sunrise naturally leads to frequent collisions. Rising medical bills and costly modern vehicle parts make each claim more expensive to settle. Because these incidents frequently involve complex legal recovery, firms supporting victims often explore Lead Generation for Personal Injury Attorneys to connect drivers with qualified representation. Keeping a clean driving history remains your strongest defense, helping offset high regional baseline rates.
Neighborhood Zip Codes: Why Rates Vary Between Sunrise and Pompano Beach
Relocating just five miles down the road can shift what an underwriter charges. Postal codes tell insurers how densely packed the streets are, how often street flooding happens, and how vehicle thefts trend in that exact area. Parking in a secured residential garage carries less risk than parking on open curbs, creating measurable rate differences for motorists seeking seguro de auto barato en Broward.
Florida Auto Insurance Essentials: Minimum Requirements vs. Real Protection
Securing a legal vehicle tag in Florida requires remarkably little coverage on paper, but bare-bones compliance often creates a dangerous illusion of safety. Under state law, the official requisitos mínimos de seguro en Florida mandate just two elements: $10,000 in Personal Injury Protection (PIP) and $10,000 in Property Damage Liability (PDL). While that keeps your registration valid with the state, it leaves massive financial blind spots. Given the average price of modern vehicles, a modest fender-bender involving two other cars can exhaust that $10,000 property damage limit in seconds, leaving you personally on the hook for the remaining balance.
Decoding Florida No-Fault Insurance and PIP Coverage
Florida operates under a no-fault framework, meaning your own insurance carrier pays for your medical treatment regardless of who caused the collision. PIP covers 80% of reasonable medical expenses and 60% of lost income, up to the statutory limit. Strict rules govern these benefits. You must seek qualified medical attention within 14 calendar days of an accident to access funds, and if a medical provider does not diagnose an Emergency Medical Condition, your available limit drops from $10,000 to just $2,500. PIP also never pays a dime toward physical damage to your car.
Why Bodily Injury and Uninsured Motorist Coverage Matter
Motorists searching for seguro de auto barato en Broward often assume that state minimums protect them from legal action. In reality, Florida does not mandate Bodily Injury Liability (BIL) for standard vehicle registration. Driving without BIL means that if you cause an accident resulting in serious harm, the injured party can pursue your personal bank accounts, future wages, and physical assets directly in court.
Uninsured Motorist (UM) coverage is equally essential. Roughly one in five drivers across Florida operates without any auto insurance at all. When an uninsured motorist collides with you on local roadways, UM coverage steps in to pay for your medical procedures, lost income, and long-term recovery. Taking time to review options with an experienced team like Si Insurance Agency helps you build sensible protection that shields your family without stretching your budget.
Practical Strategies to Lower Your Car Insurance Premium Without Losing Coverage
Cutting your monthly expenses doesn't require stripping away the legal protections that keep your household financially secure. In fact, seasoned drivers use practical adjustments to reduce their rates while keeping robust liability limits intact. Established industry groups outline proven estrategias para reducir la prima de seguro that target operational policy settings rather than your core liability shield. Taking a methodical approach to these adjustments helps you unlock genuine savings.
Optimizing Deductibles and Collision Protection on Older Vehicles
Adjusting your comprehensive and collision deductibles offers immediate rate relief. Moving a deductible from $500 to $1,000 significantly lowers your recurring premium because you assume a slightly larger share of minor repair costs. The key is setting aside that difference in an emergency savings reserve so an unexpected claim never catches you off guard. If your vehicle is older and its market value has dropped considerably, paying for collision coverage year after year may no longer make mathematical sense, freeing up cash for essential liability protection.
Harnessing Multi-Policy Bundles and Driver Discounts
Insurers reward policyholders who consolidate multiple risks under a single umbrella. Pairing your vehicle policy with homeowners, condo, or renters coverage is one of the quickest ways to secure affordable terms. Additional discount opportunities include:
Driver Profile Credits: Approved defensive driving courses and good student qualifications consistently trigger underwriter credits.
Vehicle Telematics and Security: Installing verified anti-theft tracking devices or enrolling in low-mileage monitoring programs can reduce rates.
Billing Efficiencies: Setting up automatic monthly transfers and choosing paperless policy delivery eliminate administrative surcharges.
Working with an independent advisor makes comparing these incentives simple. When looking for seguro de auto barato en Broward, comparing options across the top auto insurance companies in Florida allows you to pinpoint which carrier offers the best discount combination for your specific driving profile.
Captive Agents vs. Independent Brokers: Finding the Best Value in Broward
Where you buy your policy matters just as much as the coverage options you select. Many drivers jump onto automated national websites or call captive brand offices when searching for seguro de auto barato en Broward. Captive agents represent only a single insurance company. If that particular company raises its regional rates or tightens its guidelines, the captive agent has no other options to offer you. Automated online algorithms provide quick quotes, but they rarely ask the right questions to uncover potential coverage gaps or identify customized savings.
Why One Carrier Does Not Fit Every Driver Profile
Every insurance company operates with distinct risk appetites. A carrier that offers exceptional pricing for a homeowner with two brand-new vehicles might be prohibitively expensive for a family adding a teenage driver or someone carrying an international license. Independent agencies work differently because they represent dozens of competing regional and national carriers. If your current provider issues a rate hike at renewal, an independent broker shops your profile across their carrier network to find a better fit, keeping your monthly costs manageable without sacrificing your liability limits.
The Advantage of Personalized, Bilingual Service in South Florida
Understanding policy language can feel overwhelming, especially when sorting through state legal requirements. Having access to licensed, bilingual advisors ensures that nothing gets lost in translation. Discussing policy limits, deductibles, and optional protections in your preferred language brings clarity to decisions that protect your family's financial future.
Working with a team that maintains physical neighborhood offices in Sunrise and Pompano Beach gives you a local advocate who knows South Florida roads firsthand. If you're ready to see how multi-carrier comparison can lower your rates, connect with the team at Si Insurance Agency to compare options tailored directly to your budget.
How to Get Affordable Auto Coverage with Si Insurance
Finding a dependable policy at a fair price shouldn't feel like an uphill battle. While online calculators promise instant rates, they often overlook crucial details that lead to price jumps during underwriting. Taking a personalized approach ensures that the premium you're quoted is the premium you actually pay. By gathering the right information up front, you allow our local team to uncover discounts that automated quoting engines frequently miss.
Preparing Your Information for an Accurate Comparison
Having a few basic details ready helps streamline the process and ensures complete accuracy. When you sit down with an advisor, having these documents on hand makes a big difference:
Driver and Household Information: Driver's license numbers and dates of birth for everyone who operates vehicles in your home.
Vehicle Details: Vehicle Identification Numbers (VINs) and current odometer readings for each car.
Current Declarations Page: Your existing policy paperwork, which shows current liability limits, deductibles, and endorsement structures.
Accurate Driving History: Being upfront about recent moving violations or fender benders ensures that carrier proposals remain binding without unexpected rate adjustments.
Partnering with SI Insurance for Long-Term Peace of Mind
Securing genuine seguro de auto barato en Broward requires examining how each coverage layer supports your daily life. Our bilingual insurance specialists in Sunrise and Pompano Beach evaluate your current policies to eliminate coverage blind spots while comparing multiple vetted underwriters simultaneously. We look beyond basic vehicle protection by exploring bundle opportunities with homeowners, condo, or commercial auto policies to maximize your savings.
Your insurance needs naturally change as your life shifts. Whether you buy a new car, move to another neighborhood, or add a new driver to your household, we provide ongoing policy reviews to ensure your protection stays solid and your rates remain balanced. If you're ready to lower your monthly costs while protecting what matters most, connect with SI Insurance to start your personalized coverage review today.
Take Control of Your Broward Auto Insurance Today
True affordability isn't about purchasing the thinnest policy allowed by law. It's about securing dependable protection that genuinely shields your financial future against the daily realities of South Florida driving. By looking past bare minimums, structuring your deductibles thoughtfully, and comparing multiple carriers, finding reliable seguro de auto barato en Broward becomes both realistic and rewarding.
You don't have to navigate changing insurance rules or complex policy options alone. With accessible neighborhood offices conveniently located in Sunrise and Pompano Beach, our team delivers friendly, bilingual professional guidance committed to transparent client advocacy. Through independent agency representation across an extensive network of top-rated Florida carriers, we evaluate multiple underwriters simultaneously to match your budget and unique driving routine. Connect with our local team at Si Insurance Agency to find your best rate and enjoy lasting peace of mind every time you get behind the wheel.
Frequently Asked Questions
Is cheap auto insurance in Broward County sufficient to protect my personal assets?
No, bare-bones cheap insurance usually leaves critical personal assets vulnerable after an accident. Stripping a policy down to state minimums eliminates bodily injury liability protection entirely. If you're judged at fault in a major crash, injured drivers can target your personal savings, future wages, and property. Finding dependable seguro de auto barato en Broward means restructuring deductibles and capturing legitimate discounts rather than discarding essential liability protections.
What is the absolute minimum car insurance required to drive legally in Florida?
Florida law strictly requires drivers to carry a minimum of $10,000 in Personal Injury Protection (PIP) and $10,000 in Property Damage Liability (PDL). Under the state's no-fault system, PIP covers 80% of necessary medical costs and 60% of lost income up to that limit, regardless of fault. Standard vehicle registration doesn't require bodily injury liability, though driving without it creates severe personal exposure.
Why are car insurance premiums significantly higher in South Florida than other states?
Dense traffic congestion, frequent collision claims, and severe weather risks drive South Florida insurance rates well above national averages. Arterial highways like I-95 and the Florida Turnpike experience heavy commuter volume and high accident frequencies daily. Regional litigation patterns, elevated vehicle repair costs, street flooding from tropical storms, and a sizable population of uninsured motorists all push baseline underwriting rates higher across Broward County.
Can bilingual agents help me understand policy conditions in Spanish and English?
Yes, licensed bilingual advisors clarify complex policy language so you understand every condition in your preferred language. Florida's no-fault terminology, statutory deadlines, and optional endorsements can easily create confusion. Working with bilingual specialists ensures that Spanish-speaking motorists secure appropriate coverage limits without language barriers, making the search for seguro de auto barato en Broward both straightforward and secure for your family.
How does an independent insurance agency find lower rates than direct national insurers?
Independent insurance agencies represent dozens of competing regional and national insurance carriers rather than selling policies from just one brand. While captive agents and single-carrier websites can only offer their company's proprietary pricing, independent brokers compare multiple underwriters simultaneously. They match your specific driving record to the carrier offering the best rate and re-shop your coverage if an existing insurer increases renewal prices.
Will raising my comprehensive and collision deductibles substantially lower my payments?
Yes, increasing your comprehensive and collision deductibles provides immediate monthly premium relief. By agreeing to absorb a higher out-of-pocket share, such as moving from a $500 deductible to $1,000, you reduce the carrier's potential claim payout. This strategy is practical and effective as long as you maintain that deductible amount in an accessible emergency savings fund to avoid financial strain after an unexpected loss.
What documents do I need to prepare when requesting a Florida auto insurance quote?
You should assemble your driver's license number, vehicle identification numbers (VINs), and your current policy declarations page. Gathering the birth dates and licensing details of all household vehicle operators ensures rate accuracy. Sharing your typical commuting mileage and disclosing past traffic violations openly allows brokers to calculate precise discounts and deliver a binding quote without unexpected adjustments later.
Comments