


Florida Citizens Property Insurance Alternatives: 2026 Guide
Is your home's most critical financial safeguard truly secure if it relies on Florida's insurer of last resort? While Citizens Property Insurance was designed as a temporary safety net, many homeowners in Broward County find themselves tethered to it indefinitely, often sacrificing coverage depth for basic availability. Finding reliable Citizens Property Insurance alternatives Florida homeowners can trust is no longer just about price; it's a strategic move toward comprehensive risk management and long-term financial stability.
You're likely feeling the mounting pressure of rising premiums and the looming uncertainty of the depopulation process as hurricane season approaches. It's a common frustration to face limited options in South Florida, especially when you're seeking the stability that only a private carrier can provide. This 2026 guide is designed to help you transition from the state-backed program to private market coverage that offers better protection and more intellectual confidence in your policy.
We'll examine the latest eligibility rules regarding the 20 percent premium threshold and the strategic benefits of private market takeouts. By understanding how to work with an independent agency that specializes in the Sunrise and Pompano Beach markets, you can secure higher coverage limits and a more resilient financial future for your property.
Table of Contents
Why Florida Homeowners are Seeking Citizens Property Insurance Alternatives
Florida's insurance market is reaching a critical turning point. For many years, the Citizens Property Insurance Corporation acted as a necessary harbor during a period of intense private market volatility. You should keep in mind that this state-backed entity was established as a temporary safety net, not a permanent home for the state's residential properties. As we move into 2026, many families are actively seeking Citizens Property Insurance alternatives Florida providers can offer to find more comprehensive protection. This shift is happening because "last resort" coverage brings unique risks, including the possibility of heavy financial surcharges if a catastrophic storm exhausts the corporation's funds. These hidden costs can result in assessments on your policy that far exceed your initial premium.
To better understand the mechanism of this transition and what it means for your policy, watch this helpful video:
The Limitations of 'Last Resort' Coverage
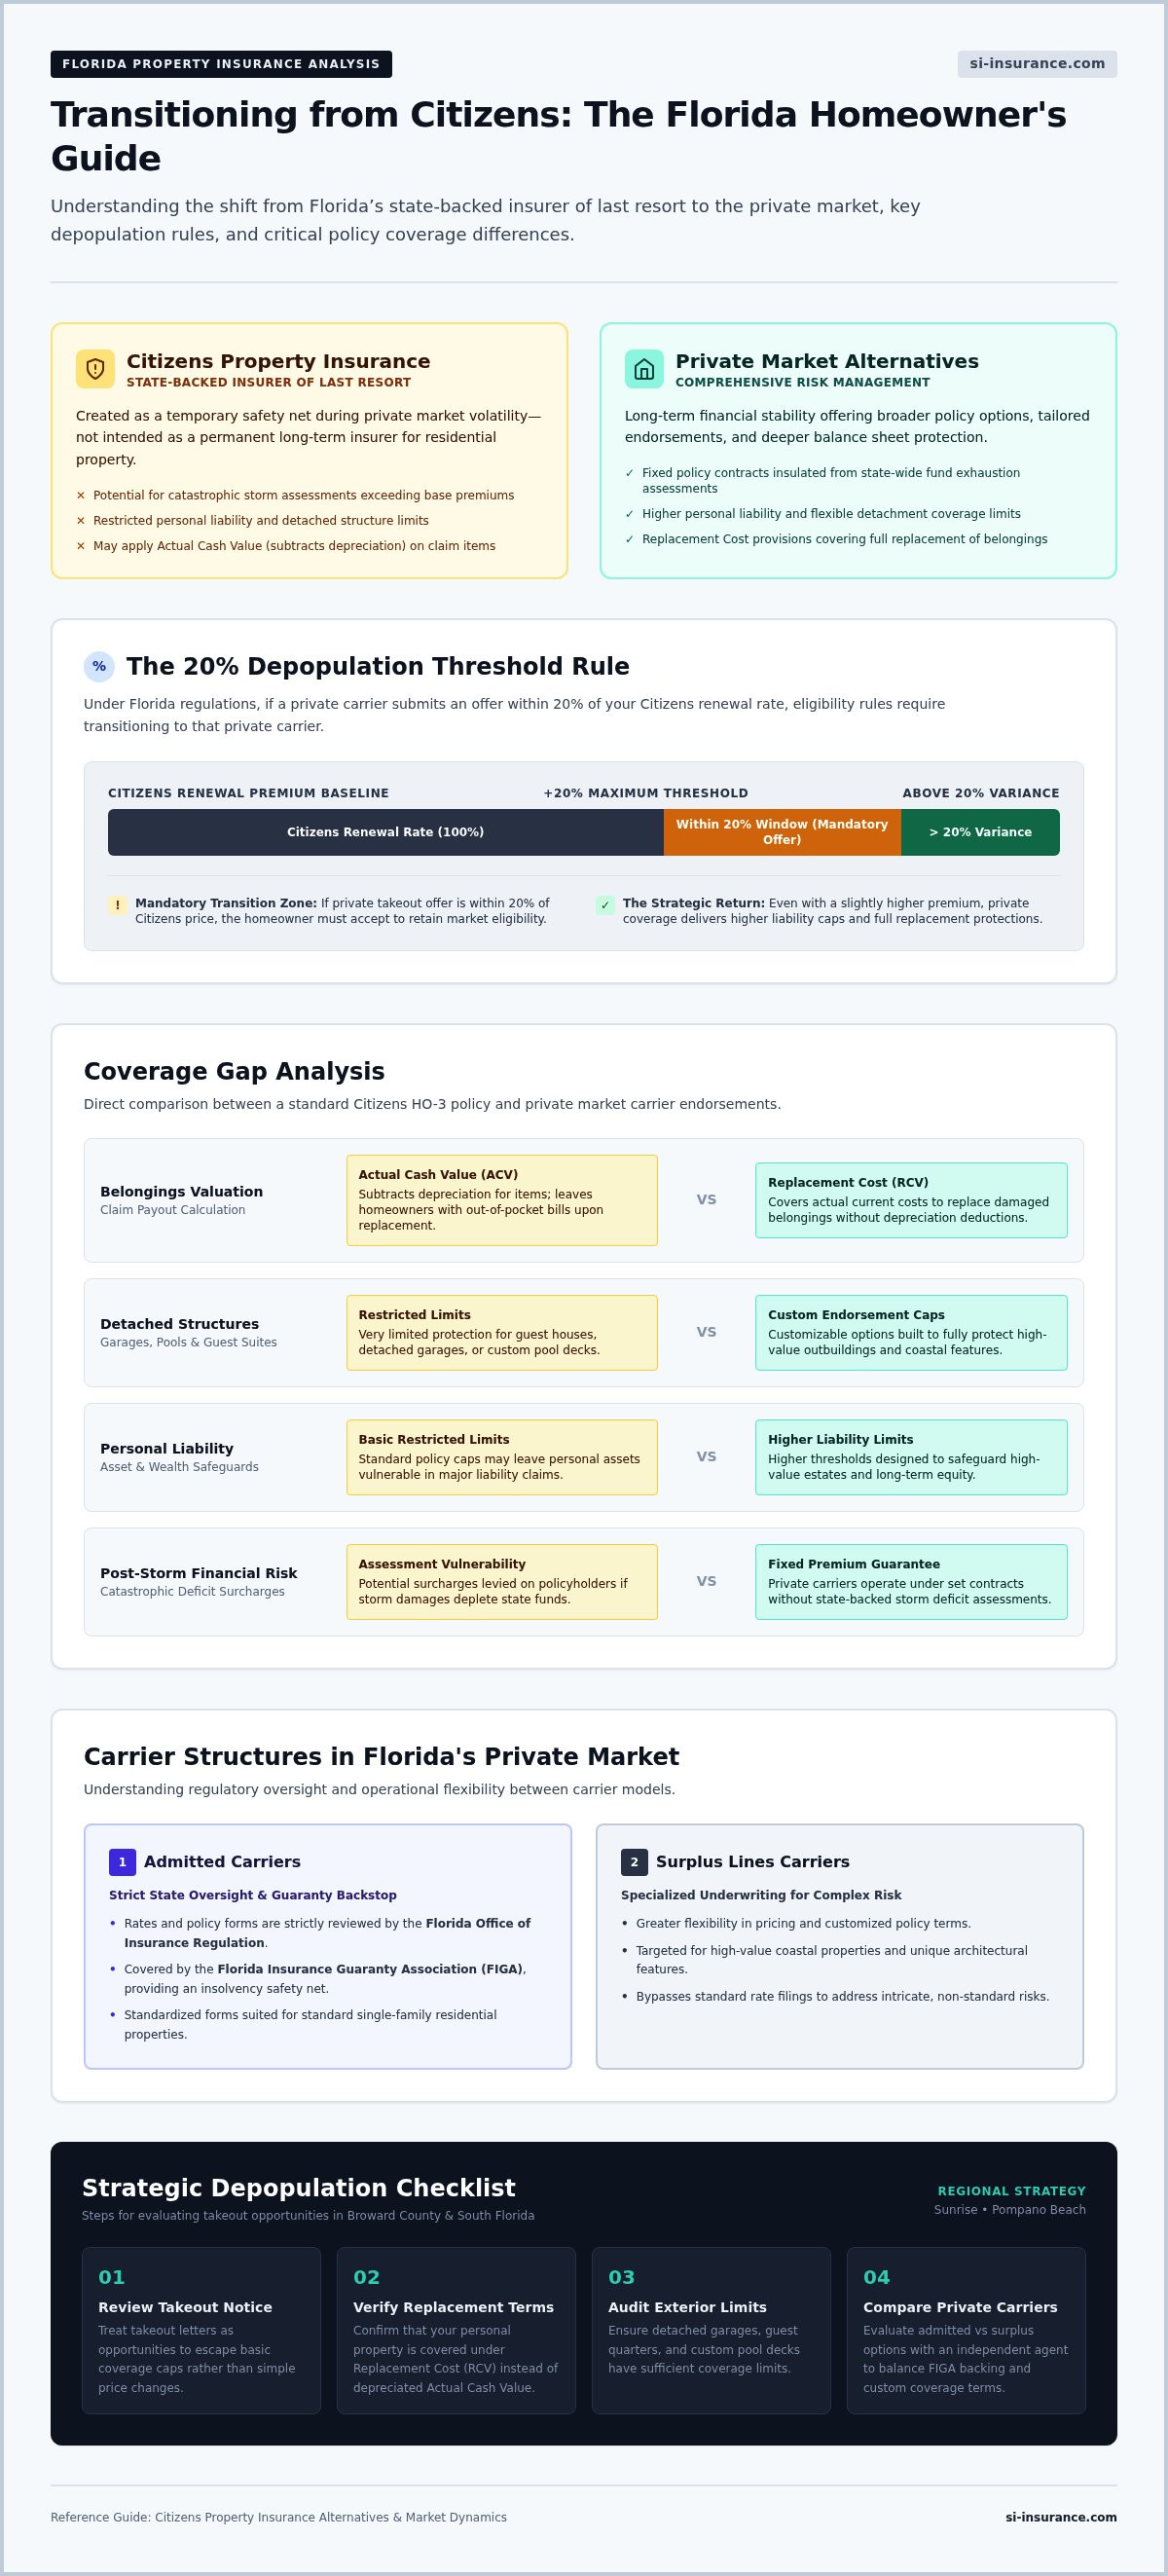
A standard Citizens HO-3 policy often lacks the depth needed for modern protection. You might find restricted limits on personal liability or very limited coverage for detached structures like a guest house, a detached garage, or a custom pool deck. One of the biggest surprises for policyholders is the difference between "Actual Cash Value" and "Replacement Cost." While private market alternatives usually cover what it actually costs to replace your belongings, Citizens might use a valuation that subtracts depreciation for certain items. This leaves you with a significant bill after a claim. For high-value homes in Pompano Beach, these gaps are more than just a nuisance; they're a real threat to your financial security that basic policies aren't built to handle.
Rising Premiums and the 20% Rule
New rules for 2026 have changed how homeowners transition back to the private market. Florida law now states that if a private insurance company offers you a premium within 20% of your Citizens renewal price, you're usually required to take that offer to stay eligible for coverage. This is part of a larger effort to return Citizens to its original role as a small, specialized insurer. Even if a private policy costs a bit more upfront, the value you get in return is often much higher. Private Citizens Property Insurance alternatives Florida residents select often come with higher liability limits and more flexible options for your specific needs. Think of your insurance as a strategy for protecting your wealth over the long haul, rather than just another bill to pay. Working with an independent agent allows you to compare these specialized products side by side to ensure you aren't sacrificing quality for a slightly lower price tag.
Top Private Market Alternatives to Citizens in Florida
The private market in Florida has matured significantly since the recent legislative reforms. When you begin exploring Citizens Property Insurance alternatives Florida homeowners can access, you'll encounter two primary categories: admitted and surplus lines carriers. Admitted carriers are those that have their rates and policy forms strictly reviewed by the Florida Office of Insurance Regulation. These companies offer an additional layer of security because they're members of the Florida Insurance Guaranty Association (FIGA), which provides a backstop for policyholders if a carrier becomes insolvent.
Admitted Carriers vs. Surplus Lines
While admitted carriers provide FIGA protection, surplus lines policies serve a specific strategic purpose for more complex risks. If you own a high-value coastal property or a home with unique architectural features, a surplus lines carrier might be your best option. These insurers have more flexibility in their pricing and policy terms, allowing them to cover risks that standard companies might avoid. Many of these private alternatives now use sophisticated risk modeling and granular data. This means if you've recently upgraded to impact windows or a new roof, these tech-forward insurers can often price your risk more accurately than the broad strokes used by the state. You can find more details on how these companies participate in the market through the Citizens Depopulation Program resources.
Evaluating Carrier Stability in 2026
A carrier's financial rating is a non-negotiable metric when you're moving away from the state-backed system. Most mortgage lenders require a carrier to maintain a specific rating, often an 'A' or better from agencies like Demotech or A.M. Best. This rating signals that the company has the capital reserves and reinsurance treaties necessary to pay out claims after a major storm. Reinsurance is essentially insurance for the insurance company; it's what allows them to remain solvent after a catastrophic hurricane season.
It's vital to look beyond the premium and examine the underlying strength of the entity protecting your home. A professional at Si Insurance Agency can help you verify these credentials and explain how a carrier's reinsurance structure impacts your long-term security. Choosing the right partner means finding a balance between modern efficiency and established financial power. If you're unsure which rating your lender requires, reaching out for a quick consultation can clarify your options and ensure your coverage meets all contractual obligations.
Navigating the Citizens Depopulation and Takeout Process
The "Depopulation Program" often sounds like a bureaucratic hurdle, but it's actually a vital indicator that the Florida insurance market is healing. When private carriers seek to "take out" policies from Citizens, it signals they have the capital and confidence to write new business in the state. Receiving a notice isn't a cause for alarm; it's an invitation to secure more robust protection through specialized Citizens Property Insurance alternatives Florida providers. These private companies are stepping up to offer the stability that a state-backed insurer of last resort simply isn't designed to maintain for the long haul. Transitioning back to the private sector is a sign that your property is once again viewed as a high-value asset by the broader financial market, a perspective shared by specialized lenders like LoansByJB (The Nuhome Team) who focus on complex, investor-driven scenarios.
Your takeout letter is a dense document, but it contains three critical pieces of data: the name of the assuming company, your estimated renewal premium, and a side-by-side coverage comparison. It's essential to verify the reputation of the assuming carrier immediately. You should check their financial stability ratings and their history of claims handling in South Florida. You have a limited window to "opt-out" if you wish to stay with Citizens, but keep in mind that if the private offer is within 20% of your current premium, you'll likely lose your eligibility for Citizens regardless. For a broader look at how these policies fit into your overall portfolio, consult the Florida Department of Financial Services homeowners insurance overview for regulatory guidance on policy types and underwriting standards.
The Agent's Role in the Takeout Transition
You shouldn't try to decode these letters alone. An independent agent acts as your intellectual partner, analyzing whether the assuming company offers true coverage parity or if there are hidden exclusions that could leave you vulnerable. At Si Insurance Agency, we help Sunrise and Pompano Beach residents evaluate these transitions with a focus on long-term asset protection. We look past the premium to ensure the underlying policy language is actually superior to what you're leaving behind. We understand the unique pressures of the Broward County market and can shop multiple Citizens Property Insurance alternatives Florida homeowners might otherwise miss.
Transitioning to a private carrier is a strategic move that often results in higher liability limits and more flexible detached structure coverage. To understand how these changes impact your broader investment, read our Home Insurance in Florida: A Strategic Guide. We don't just process paperwork; we engineer a transition that prioritizes your peace of mind and financial resilience. Ignoring these letters can lead to an automatic transfer, so proactive analysis is the only way to maintain control over your risk management strategy.
A Strategic Checklist for Switching to Private Florida Insurance
Transitioning to Citizens Property Insurance alternatives Florida carriers offer requires more than just a signature; it's a methodical process of refining your home's risk profile. You should start by gathering your current Citizens declarations page to establish a baseline for your coverage limits and deductibles. This document allows for a precise "apples-to-apples" comparison, ensuring that you don't inadvertently sacrifice essential protections while moving to the private market. It's about maintaining the integrity of your coverage while migrating to a more stable, specialized entity that views your property as a high-value asset rather than a state liability.
Step 1: The Pre-Switch Inspection
In the 2026 market, your 4-Point Inspection and Wind Mitigation reports are your most powerful negotiating tools. Private carriers look for modern plumbing, updated electrical systems, and roofs with significant remaining life before they commit to a policy. If you own a home in Pompano Beach, simple upgrades like adding secondary water resistance or improving roof-to-wall connections can drastically lower your private market premiums. You should treat your property as a financial risk profile that needs polishing before you begin shopping for a new carrier. A clean inspection report often makes the difference between a standard policy and a premium offering with better terms.
Step 2: Leveraging Bundles and Discounts
Private carriers prioritize stability, and they often reward clients who bring multiple lines of business into their ecosystem. Unlike Citizens, which is restricted in its offerings, private insurers provide substantial discounts when you pair your home policy with auto coverage. You can explore these synergies in The Ultimate Guide to Auto Insurance in Florida. Beyond bundling, you should look for credits related to centrally monitored alarm systems, gated community residency, or senior citizen status. These small adjustments can significantly refine your total cost of protection while providing a more comprehensive safety net for your entire household.
Step 3: Closing the Coverage Gaps
As you finalize the transition, pay close attention to "Ordinance or Law" coverage, which is often more robust in private policies than in state-backed ones. This is vital for older Florida homes that may need to meet modern building codes after a loss. Additionally, ensure your high-value personal assets are accounted for by reviewing Jewelry Insurance in Florida. Finally, coordinate with your mortgage servicer to update your escrow account. A simple administrative oversight here can lead to a lapse in coverage, which is a risk no homeowner should take during hurricane season. Confirming that your lender has received the new policy and adjusted the payments is the final step in securing your long-term stability.
To begin this methodical review of your current policy and explore better private options, contact Si Insurance Agency today for a professional risk assessment tailored to your specific needs.
Why Si Insurance Agency is Your Partner in the Florida Private Market
Choosing the right insurance partner is about more than just finding a policy; it's about aligning with a consultant who understands the high-stakes nature of Florida real estate. As an independent agency, Si Insurance Agency doesn't work for a single carrier. We work for you. This distinction is vital when you're evaluating Citizens Property Insurance alternatives Florida homeowners need to secure their future. We have the technical mastery to navigate complex risk structures and the access to a broad network of private insurers, allowing us to find the specific alignment of coverage and stability that fits your high-value needs.
Local Expertise in Sunrise and Pompano Beach
Our offices in Sunrise and Pompano Beach aren't just administrative hubs; they're centers of local intelligence. We understand the nuanced differences between coastal exposure along the Pompano beachfront and the specific inland risks in Sunrise neighborhoods. Having a physical presence in the community means we're here for the high-stakes moments, whether it's a meticulous policy review or a complex claim. We bring a level of corporate elegance and absolute security to the process, ensuring you feel confident in the strategic decisions we make together. It's about providing a premium, personalized service that generic, direct-to-consumer platforms simply can't replicate.
Securing Your Florida Legacy
Your home is more than a structure; it's the foundation of your financial legacy in the Sunshine State. Protecting that legacy requires a partner who acts as a protective guardian, someone who prioritizes long-term security over a quick transaction. We take a calculated, analytical approach to risk management, ensuring that the private market solutions we recommend are engineered for resilience. Insurance shouldn't be a source of frustration; it should be a source of intellectual confidence. By moving away from the state-backed system with a professional guide, you're taking a definitive step toward permanent stability.
We invite you to experience a different kind of insurance relationship, one focused on foresight and elite expertise. Our team is ready to analyze your current risk and present alternatives that offer the protection your property deserves. Contact Si Insurance Agency today for a comprehensive review of your Citizens alternatives.
Securing Your Property's Future Beyond the State Safety Net
Transitioning away from the insurer of last resort is a strategic step toward long-term asset protection. You've learned that private carriers offer more than just a policy; they provide comprehensive coverage limits and financial stability that Citizens cannot match. By understanding the depopulation process and using a methodical checklist, you can move your home from a state liability to a private asset. Finding the right Citizens Property Insurance alternatives Florida homeowners can rely on requires a sophisticated approach to risk management.
At Si Insurance Agency, we specialize in these complex transitions. Our local expertise in Sunrise and Pompano Beach allows us to navigate the unique pressures of the Broward County market with precision. We provide access to top-rated private carriers and act as a protective guardian for your most valuable investments. It's time to move past the uncertainty of "last resort" coverage and secure a policy engineered for your specific needs.
We're here to help you build a more resilient financial future for your home and family.
Frequently Asked Questions
Is private home insurance in Florida more expensive than Citizens?
Private premiums aren't always higher than those offered by the state. While Citizens often presents a lower initial quote, private carriers can be very competitive for homes with modern upgrades or superior wind mitigation. You're also paying to avoid the risk of post-storm assessments that can impact Citizens policyholders. Private policies provide a more robust financial structure and higher coverage limits, which often justifies the premium difference for homeowners who prioritize absolute security.
What happens if I ignore a Citizens depopulation or takeout letter?
If you ignore a takeout letter, your policy will likely be automatically assumed by the private carrier listed in the notice. You have a specific deadline to opt-out and remain with Citizens, provided you still meet the eligibility criteria. However, if the private offer is within the 20 percent premium threshold, you'll lose your eligibility for Citizens entirely at your next renewal. This could leave you without the state-backed option when you need it most.
Can I switch back to Citizens if my private carrier raises rates?
You can only return to Citizens if you meet the state's strict eligibility requirements. This typically means you must prove that you've been unable to find a private market policy or that the best private offer you received is more than 20 percent higher than the Citizens premium. Returning isn't guaranteed, as the state continues to tighten rules to reduce its total exposure and encourage homeowners to maintain their coverage with stable, private market entities.
Do private insurance companies in Florida offer better coverage than Citizens?
Yes, private carriers generally provide more comprehensive protection than the basic forms used by Citizens. Private Citizens Property Insurance alternatives Florida homeowners choose often include higher personal liability limits, better coverage for detached structures, and replacement cost valuation for your belongings. Citizens policies are designed to be a temporary safety net, while private market products are engineered to meet the sophisticated needs of property owners who require deeper risk mitigation and long-term stability.
Will my mortgage company accept a private insurance alternative to Citizens?
Most mortgage lenders actively prefer private insurance over Citizens, provided the carrier meets their financial rating requirements. Lenders typically look for an "A" rating or better from agencies like Demotech or A.M. Best to ensure the company has the capital to pay claims after a major hurricane. Because private policies often offer higher coverage limits and more robust terms, they provide a more secure safeguard for the lender's collateral than a basic state-backed policy.
How do I know if a private insurance company in Florida is financially stable?
You should verify the carrier's financial stability rating through independent agencies like Demotech or A.M. Best. These ratings reflect the company's ability to fulfill its obligations to policyholders after a significant catastrophe. It's also wise to examine their reinsurance treaties, which act as a financial safety net for the insurer itself. A professional agent can help you interpret these data points to ensure your home is protected by a resilient and well-capitalized entity.
What is the 20% rule for Citizens Property Insurance in 2026?
The 20 percent rule is a statutory requirement that determines your eligibility for state-backed coverage. If a private insurer offers you a policy with a premium that's within 20 percent of your Citizens renewal quote, you're considered ineligible for Citizens. This rule is designed to push homeowners back into the private market when Citizens Property Insurance alternatives Florida providers are available at a price point that the state deems competitive and reasonable for the current market.
Can an independent agent help me find Citizens alternatives in Broward County?
An independent agent is your most effective partner when navigating the Broward County market. Unlike agents who represent a single carrier, independent professionals have access to a vast network of private insurers willing to write in Sunrise and Pompano Beach. We analyze multiple quotes to find the best alignment of price and protection. This local expertise ensures that your specific neighborhood risks are managed by a stable carrier that understands the South Florida landscape.
Comments