


Florida Compliant Drivers Program: A Strategic Guide to SR-22 Insurance in 2026
A license suspension is not a permanent mark of failure; it is a strategic inflection point for your driving record. While the requirement for SR-22 insurance Florida often feels like an insurmountable hurdle, it actually serves as a structured pathway to restore your professional standing and legal compliance. Many drivers experience significant anxiety when faced with the technical distinctions between SR-22 and FR-44 filings, yet these documents are simply the essential mechanisms used to verify financial responsibility under Florida Statute 324.021. We understand that the fear of escalating premiums and the frustration of the FLHSMV reinstatement process can be exhausting.
You deserve a clear, methodical plan to regain your mobility without being penalized by high costs forever. This guide will teach you how to navigate the Florida Compliant Drivers Program to reinstate your license and eventually secure elite insurance rates. We'll examine the mandatory three year filing period, explain how to avoid the lapses that reset your progress, and provide a roadmap for finding carriers that reward consistent compliance. By treating this process as a calculated risk management exercise, you can move from uncertainty to absolute security on the road in 2026.
Table of Contents
Defining the Florida Compliant Drivers Program and SR-22 Framework
Personal Driver Compliance: SR-22 Filings and License Reinstatement
Commercial Fleet Compliance: Managing High-Risk Drivers in Florida
Analyzing Financial Responsibility: Florida’s SR-22 vs. FR-44 Requirements
Implementing Your Reinstatement Strategy with Si Insurance Agency
Defining the Florida Compliant Drivers Program and SR-22 Framework
The Florida Compliant Drivers Program isn't a formal government office you visit, but rather a structured regulatory pathway. It's designed to help drivers with specific violations demonstrate their financial reliability over time. When the Florida Department of Highway Safety and Motor Vehicles (FLHSMV) mandates a filing, they are essentially asking for a verified guarantee that you possess the necessary coverage to protect others on the road. This is where SR-22 insurance Florida enters the conversation, acting as the critical bridge between a suspended license and the restoration of your full driving privileges.
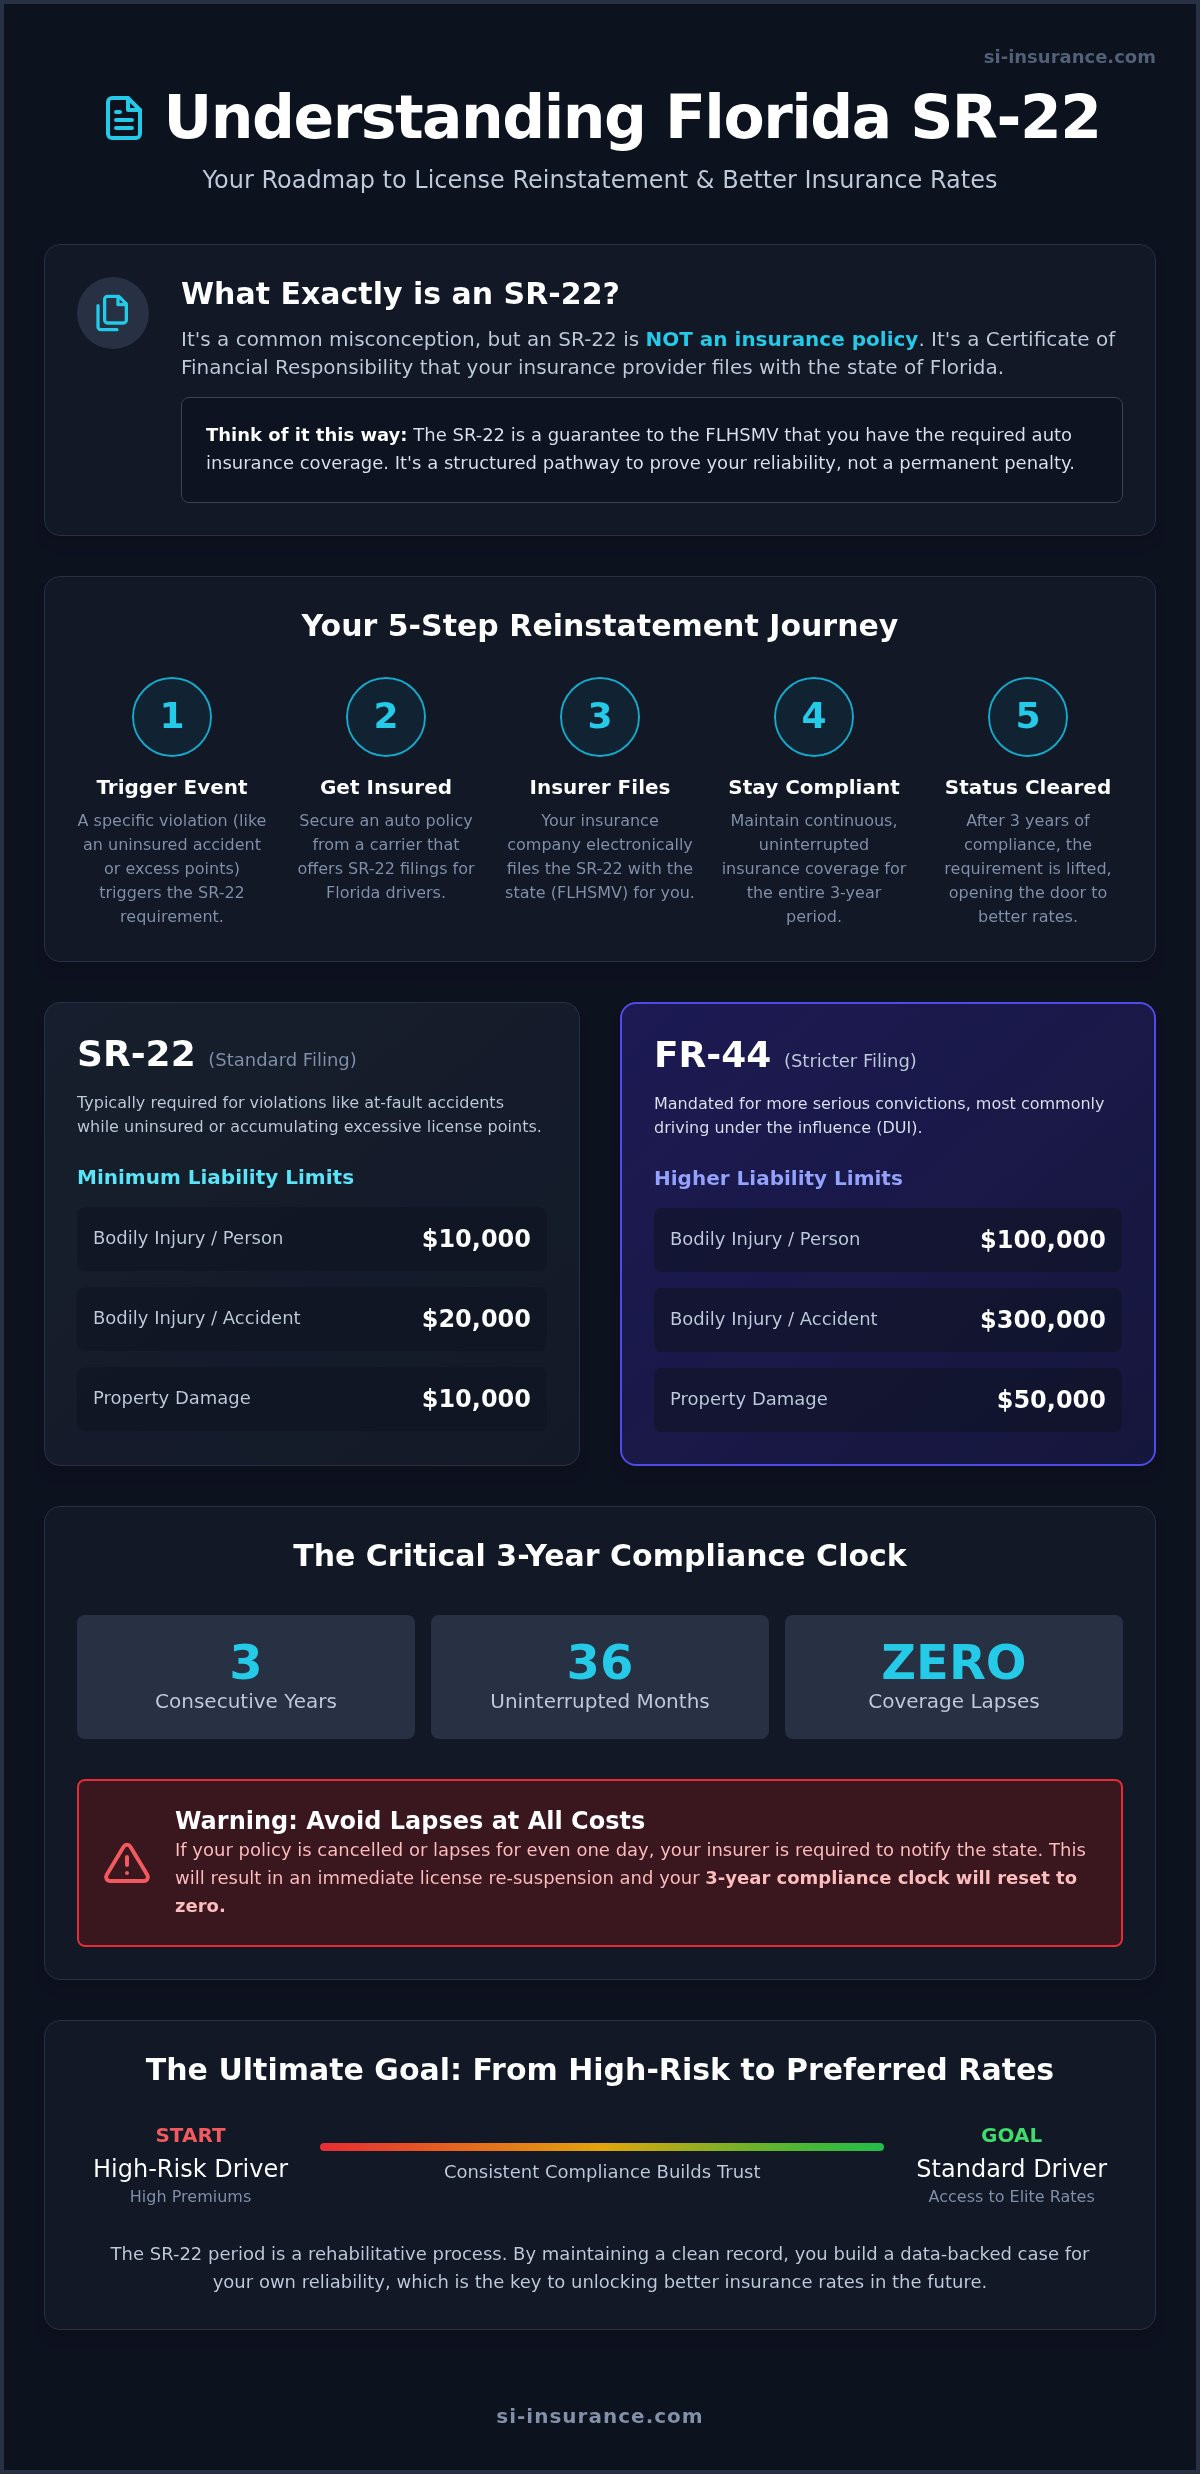
It's vital to understand that an SR-22 is not a standalone insurance policy. Instead, it's a certificate of financial responsibility that your insurance provider files with the state on your behalf. If you are wondering What is an SR-22?, think of it as a high-level endorsement attached to your existing auto insurance. This certificate provides the state with real-time notification of your coverage status. If your policy lapses, the state is notified immediately, which typically results in an automated license suspension. Maintaining this compliant status is the only way to avoid more permanent legal consequences and eventual license revocation.
The Legal Basis: Florida Statute 324.021
In 2026, the primary authority for these requirements remains Florida Statute 324.021. This law dictates that drivers involved in certain incidents, such as accidents while uninsured or accumulating excessive points, must prove they can meet the state's financial responsibility limits. For a standard SR-22, these limits are set at $10,000 for bodily injury to one person, $20,000 for bodily injury per accident, and $10,000 for property damage. Your insurance carrier handles the technical heavy lifting by electronically filing this document, ensuring your record reflects your compliance within a matter of days.
Why Compliance is a Strategic Financial Asset in 2026
The landscape of high-risk insurance has shifted from a punitive model to a rehabilitative one. With the widespread adoption of telematics and real-time Motor Vehicle Record monitoring, insurance companies can see your driving habits more clearly than ever. By participating diligently in the compliance framework, you aren't just following rules; you are building a data-backed case for your own reliability. Drivers who maintain a clean record during their three-year filing period often find themselves positioned as a "calculated risk" rather than a high-risk liability. This distinction is the key to eventually securing elite rates that are usually reserved for those with unblemished records. At Si Insurance Agency, we view this period as a strategic rebuilding phase that protects your long-term financial security.
Personal Driver Compliance: SR-22 Filings and License Reinstatement
Reinstating your driving privileges in Florida is a methodical journey that requires both precision and foresight. While a license suspension can feel like an abrupt halt to your daily life, the path forward is clearly defined by the state’s regulatory framework. The requirement for SR-22 insurance Florida is typically triggered by specific traffic offenses, such as accumulating excessive points, being involved in an accident while uninsured, or certain major violations. According to this SR-22 Insurance Guide, the filing serves as a formal guarantee to the state that you meet the necessary financial responsibility limits for a continuous period.
To ensure your long-term success, it’s essential to integrate these filings with your broader Florida auto insurance strategy. This isn’t just about meeting a legal minimum; it’s about establishing a protective shield for your assets while you work to rebuild your driving record. By viewing this as a strategic transition rather than a simple administrative task, you can move closer to regaining your full mobility.
The Reinstatement Roadmap for Broward County Residents
For those living in Sunrise or Pompano Beach, the reinstatement process is local and sequential. First, you must secure an insurance policy that satisfies Florida’s increased liability mandates. Second, your chosen carrier must electronically transmit the SR-22 certificate to the Florida Department of Highway Safety and Motor Vehicles. Finally, you’ll need to settle any necessary reinstatement fees. As of 2026, these fees typically range from $150 to $500 depending on the specific nature of your violation. If you’re unsure which local office to visit, consulting with a specialized agent can help you navigate the logistics with confidence.
Managing the 36-Month Compliance Window
One of the most significant challenges drivers face is the mandatory 36-month maintenance period. It’s important to remember that the state doesn't provide reminders for SR-22 insurance Florida renewals. You are solely responsible for ensuring your coverage remains active without interruption. A single lapse, even for a day, can trigger an immediate suspension and reset your three-year clock back to zero. This is especially critical if your policy is canceled for non-payment, as the insurance company is legally required to notify the state immediately. To successfully exit the program, you must proactively request the removal of the filing from your policy once the three years have concluded.
Commercial Fleet Compliance: Managing High-Risk Drivers in Florida
Managing a commercial fleet in 2026 requires a meticulous eye for detail, especially regarding driver eligibility and liability mitigation. While the previous sections focused on the personal path to reinstatement, business owners must recognize that a single employee requiring SR-22 insurance Florida can significantly alter the risk profile of an entire operation. This is particularly true for those managing business insurance in Broward County, where high traffic density and strict regulatory oversight increase the stakes. When one driver is flagged as high-risk, it doesn't just affect their individual status; it ripples through your entire commercial auto policy, potentially triggering premium hikes or even non-renewal notices.
Commercial Auto Insurance and High-Risk Driver Qualification
Many commercial carriers are hesitant to provide coverage for drivers with active SR-22 insurance Florida filings. This hesitation stems from the statistical correlation between high-risk status and potential liability claims. If a carrier does accept the driver, you can expect a noticeable increase in premiums across the fleet. Beyond the immediate financial cost, these drivers can negatively impact your company’s Compliance, Safety, and Accountability (CSA) scores. It's a strategic necessity to implement internal protocols that monitor these statuses. By establishing a "Compliant Drivers Program" within your own company, you can create clear paths for drivers to transition back to standard status through consistent, safe performance and rigorous MVR monitoring.
Audit-Readiness for Florida Fleet Owners
Staying audit-ready means maintaining impeccable Driver Qualification (DQ) files. For any driver with an SR-22 mandate, your documentation must be airtight to withstand scrutiny from state regulators or insurance underwriters. At Si Insurance Agency, we assist local entrepreneurs in evaluating these specific fleet risks, ensuring that every driver meets the requirements of Florida Statute 324.021. By utilizing modern telematics, you can provide underwriters with objective data that proves your safety compliance. This level of transparency is essential for maintaining your corporate reputation and securing favorable terms. This proactive approach transforms a potential liability into a manageable, transparent component of your risk management strategy.
Analyzing Financial Responsibility: Florida’s SR-22 vs. FR-44 Requirements
While both certificates serve as proof of financial responsibility, the FR-44 carries a weight far beyond the standard SR-22 insurance Florida mandate. The state reserves the FR-44 specifically for DUI and DWI offenses, requiring a significant leap in liability limits. While an SR-22 typically aligns with the 10/20/10 coverage mentioned earlier, an FR-44 demands 100/300/50. This means you're required to carry $100,000 for bodily injury to one person, $300,000 per accident, and $50,000 for property damage. It’s a rigorous standard designed to ensure you have the "Ability to Respond in Damages" in the event of a severe incident. Transitioning back to a standard policy after this period requires a methodical approach to prove your rehabilitated risk profile to future underwriters.
The Underwriter’s Perspective on Certificate Types
From an underwriting standpoint, an FR-44 isn't just a higher limit; it’s a signal of increased behavioral risk. Carriers often view these drivers as several tiers above standard high-risk individuals. This classification can complicate your efforts to protect high-value assets through specialty vehicle insurance in Florida. At Si Insurance Agency, we identify carriers that specialize in these complex filings, ensuring that even under an FR-44 mandate, your broader portfolio remains protected by professionals who understand the nuances of the 2026 market.
Strategic Methodology for Reducing Premium Spikes
Managing the premium spikes associated with these mandates requires a calculated approach. You don't have to accept the first high quote you receive. Defensive driving courses can provide a small but meaningful offset to high-risk surcharges. Additionally, adjusting your deductibles for collision or comprehensive coverage can help balance the mandatory liability increase. While high-risk status makes things difficult, you can still explore bundling home and auto insurance in Florida to capture available discounts and maintain a unified risk management strategy. By looking at your total insurance spend, we can often find efficiencies that other agencies miss.
If you're currently navigating the complexities of an FR-44 or a standard SR-22 insurance Florida filing, you don't have to do it alone. Contact our experts to evaluate your financial responsibility requirements and secure a policy that protects your future.
Implementing Your Reinstatement Strategy with SI Insurance Agency
Choosing a partner for your license reinstatement is a decision that impacts both your mobility and your financial health for the next three years. While large, national carriers often rely on generic algorithms that can penalize drivers unfairly, an independent agent acts as a protective guardian for your interests. We specialize in the nuances of SR-22 insurance Florida, serving as your expert intermediary to find competitive rates from a diverse array of high-risk carriers. Our methodology isn't about finding the quickest temporary fix; it's about building an airtight strategy that secures your driving future. We've spent years refining an approach that prioritizes long-term security over transactional speed.
The Advantage of Local Broward County Expertise
Being local matters when you're dealing with state bureaucracies and complex filing requirements. Our physical presence in Sunrise and Pompano Beach allows us to navigate the specific requirements of local FLHSMV offices with absolute precision. We understand the local regulatory landscape in 2026 and have curated a network of carriers that specifically reward drivers who show consistent rehabilitation. This local expertise ensures that your SR-22 insurance Florida filing is processed with the speed and accuracy required to get you back on the road without unnecessary administrative delays. You aren't just another policy number to us; you're a neighbor whose record we at SI Insurance are committed to protecting.
Your Next Steps Toward Strategic Security
Your journey toward full reinstatement begins with a comprehensive, methodical review of your current Motor Vehicle Record (MVR) and your broader insurance needs. We don't just look at the isolated violation; we analyze your entire profile to identify opportunities for risk mitigation and long-term savings. This includes planning for the eventual removal of your SR-22 filing once the 36-month window closes. If you're ready for a composed, authoritative consultation that prioritizes your long-term interests, reaching out to the SI Insurance team is the most effective first step you can take. We'll help you begin the enrollment process for the Florida Compliant Drivers Program today, ensuring your transition back to standard status is handled with the corporate elegance and meticulous attention to detail you deserve. Let's start building your road back to elite status through a process that is as steady and deliberate as it is effective.
Securing Your Path Toward Full License Restoration
Navigating the requirements of the Florida Compliant Drivers Program is a vital journey toward reclaiming your mobility and financial reputation. We've explored how SR-22 insurance Florida serves as a technical tool for proving responsibility and why distinguishing between SR-22 and FR-44 mandates is essential for long-term success. Whether you're managing a personal record or a commercial fleet, the key remains consistent: meticulous attention to the 36-month maintenance window. By treating this period as a strategic rebuilding phase, you're not just meeting a legal requirement; you're actively lowering your risk profile for years to come.
As an independent agency with local offices in Sunrise and Pompano Beach, we offer more than just a policy. We provide a sophisticated methodology that matches you with top-tier Florida carriers while offering expert guidance on complex Financial Responsibility Laws. You don't have to manage these high-stakes filings alone. Secure your strategic insurance review with Si Insurance Agency today. Our team is ready to act as your protective guardian, ensuring your transition back to standard-risk status is handled with precision and care. Your future on the road is within reach, and we're here to help you drive toward it with confidence.
Frequently Asked Questions
What exactly is the Florida Compliant Drivers Program?
The Florida Compliant Drivers Program is the state's structured regulatory pathway designed for drivers categorized as high-risk to prove their financial reliability. It isn't a physical location but a monitoring system managed by the FLHSMV. By maintaining continuous coverage and following specific legal mandates, you demonstrate that you're no longer a significant liability. This program serves as a rehabilitative process, helping you transition from a suspended status back to full driving privileges over a set period.
How long am I required to maintain an SR-22 filing in Florida?
Most drivers are required to maintain an active SR-22 filing for a continuous period of three years. This 36-month window begins on the date of your original suspension or the date the requirement was officially triggered. It's crucial that your SR-22 insurance Florida remains active for the entire duration. If you cancel your policy or let it lapse during this time, the state will reset your three-year clock, extending your time in the program.
What is the difference between an SR-22 and an FR-44 in Florida?
The primary difference lies in the severity of the violation and the required liability limits. An SR-22 is typically mandated for non-alcohol-related offenses, such as driving without insurance, and requires standard 10/20/10 limits. Conversely, the FR-44 is strictly for DUI or DWI convictions and demands much higher coverage of 100/300/50. Because the FR-44 represents a higher risk tier, the premiums are significantly more expensive than those associated with a standard SR-22 filing.
Can I file an SR-22 if I do not own a vehicle (Non-Owner SR-22)?
Yes, you can absolutely file an SR-22 even if you don't own a vehicle through a non-owner insurance policy. This specific type of coverage provides the necessary liability protection when you're driving a vehicle that isn't yours. It's an excellent strategic option for individuals who need to reinstate their license but don't currently have a car. This ensures you remain compliant with the Florida Compliant Drivers Program while keeping your insurance costs manageable during the three-year period.
How much does the SR-22 filing fee cost in 2026?
In 2026, the one-time filing fee charged by insurance carriers to submit the certificate to the FLHSMV typically ranges between $15 and $25. It's important to distinguish this small administrative fee from the separate license reinstatement fees charged by the state. Depending on the nature of your violation, the FLHSMV may charge an additional $150, $250, or $500 to restore your driving privileges. We recommend settling these costs promptly to avoid any administrative delays in your reinstatement.
Will my insurance rates go down immediately after the 3-year SR-22 period ends?
Rates don't typically drop the moment your 36-month period concludes. You must proactively contact your insurance provider to request the removal of the SR-22 endorsement from your policy. Once the filing is removed, you can begin the process of shopping for standard-market rates. While your record will show the previous violation for a longer period, successfully completing the SR-22 insurance Florida mandate proves you're a lower risk, allowing us to help you secure much more competitive premiums.
What happens if my SR-22 insurance policy lapses for even one day?
A lapse of even a single day triggers an immediate electronic notification to the FLHSMV. This usually results in an automated suspension of your driver's license and can reset your three-year compliance clock back to the beginning. The state views any interruption in coverage as a failure to maintain financial responsibility. To avoid this severe setback, we suggest setting up automatic payments or working closely with your agent to ensure your policy renewals are handled well in advance.
Can Si Insurance Agency file my SR-22 electronically with the FLHSMV?
Yes, our agency facilitates the immediate electronic filing of your SR-22 certificate with the FLHSMV. Because we operate as an independent firm, we can quickly coordinate with our network of carriers to ensure your documentation is transmitted with high precision. This electronic process is the fastest way to update your driving record and begin the license reinstatement steps. Our goal is to minimize your downtime and provide a seamless transition back to legal and compliant driving status.
Comments