


Florida Peninsula Insurance Alternatives and Quote Comparisons
The lowest quote isn’t automatically the better policy. A Florida Peninsula Insurance alternatives and quote comparison is most useful when you compare the same coverage limits, deductibles, and exclusions, then consider the insurer’s financial strength and claims reputation. This helps show whether a lower premium is a real saving or reflects less protection.
It’s reasonable to want a competitive price without sacrificing confidence in how a claim will be handled. This guide explains how to compare Florida Peninsula with Edison and other carriers, assess reputation and claims satisfaction, and review financial strength as part of the decision. You’ll also learn how to present a competing offer to your insurer and ask whether it can match the quote, so your comparison supports a clear, informed choice rather than a decision based on price alone.
Table of Contents
Insurer reputation, claims satisfaction, and financial strength
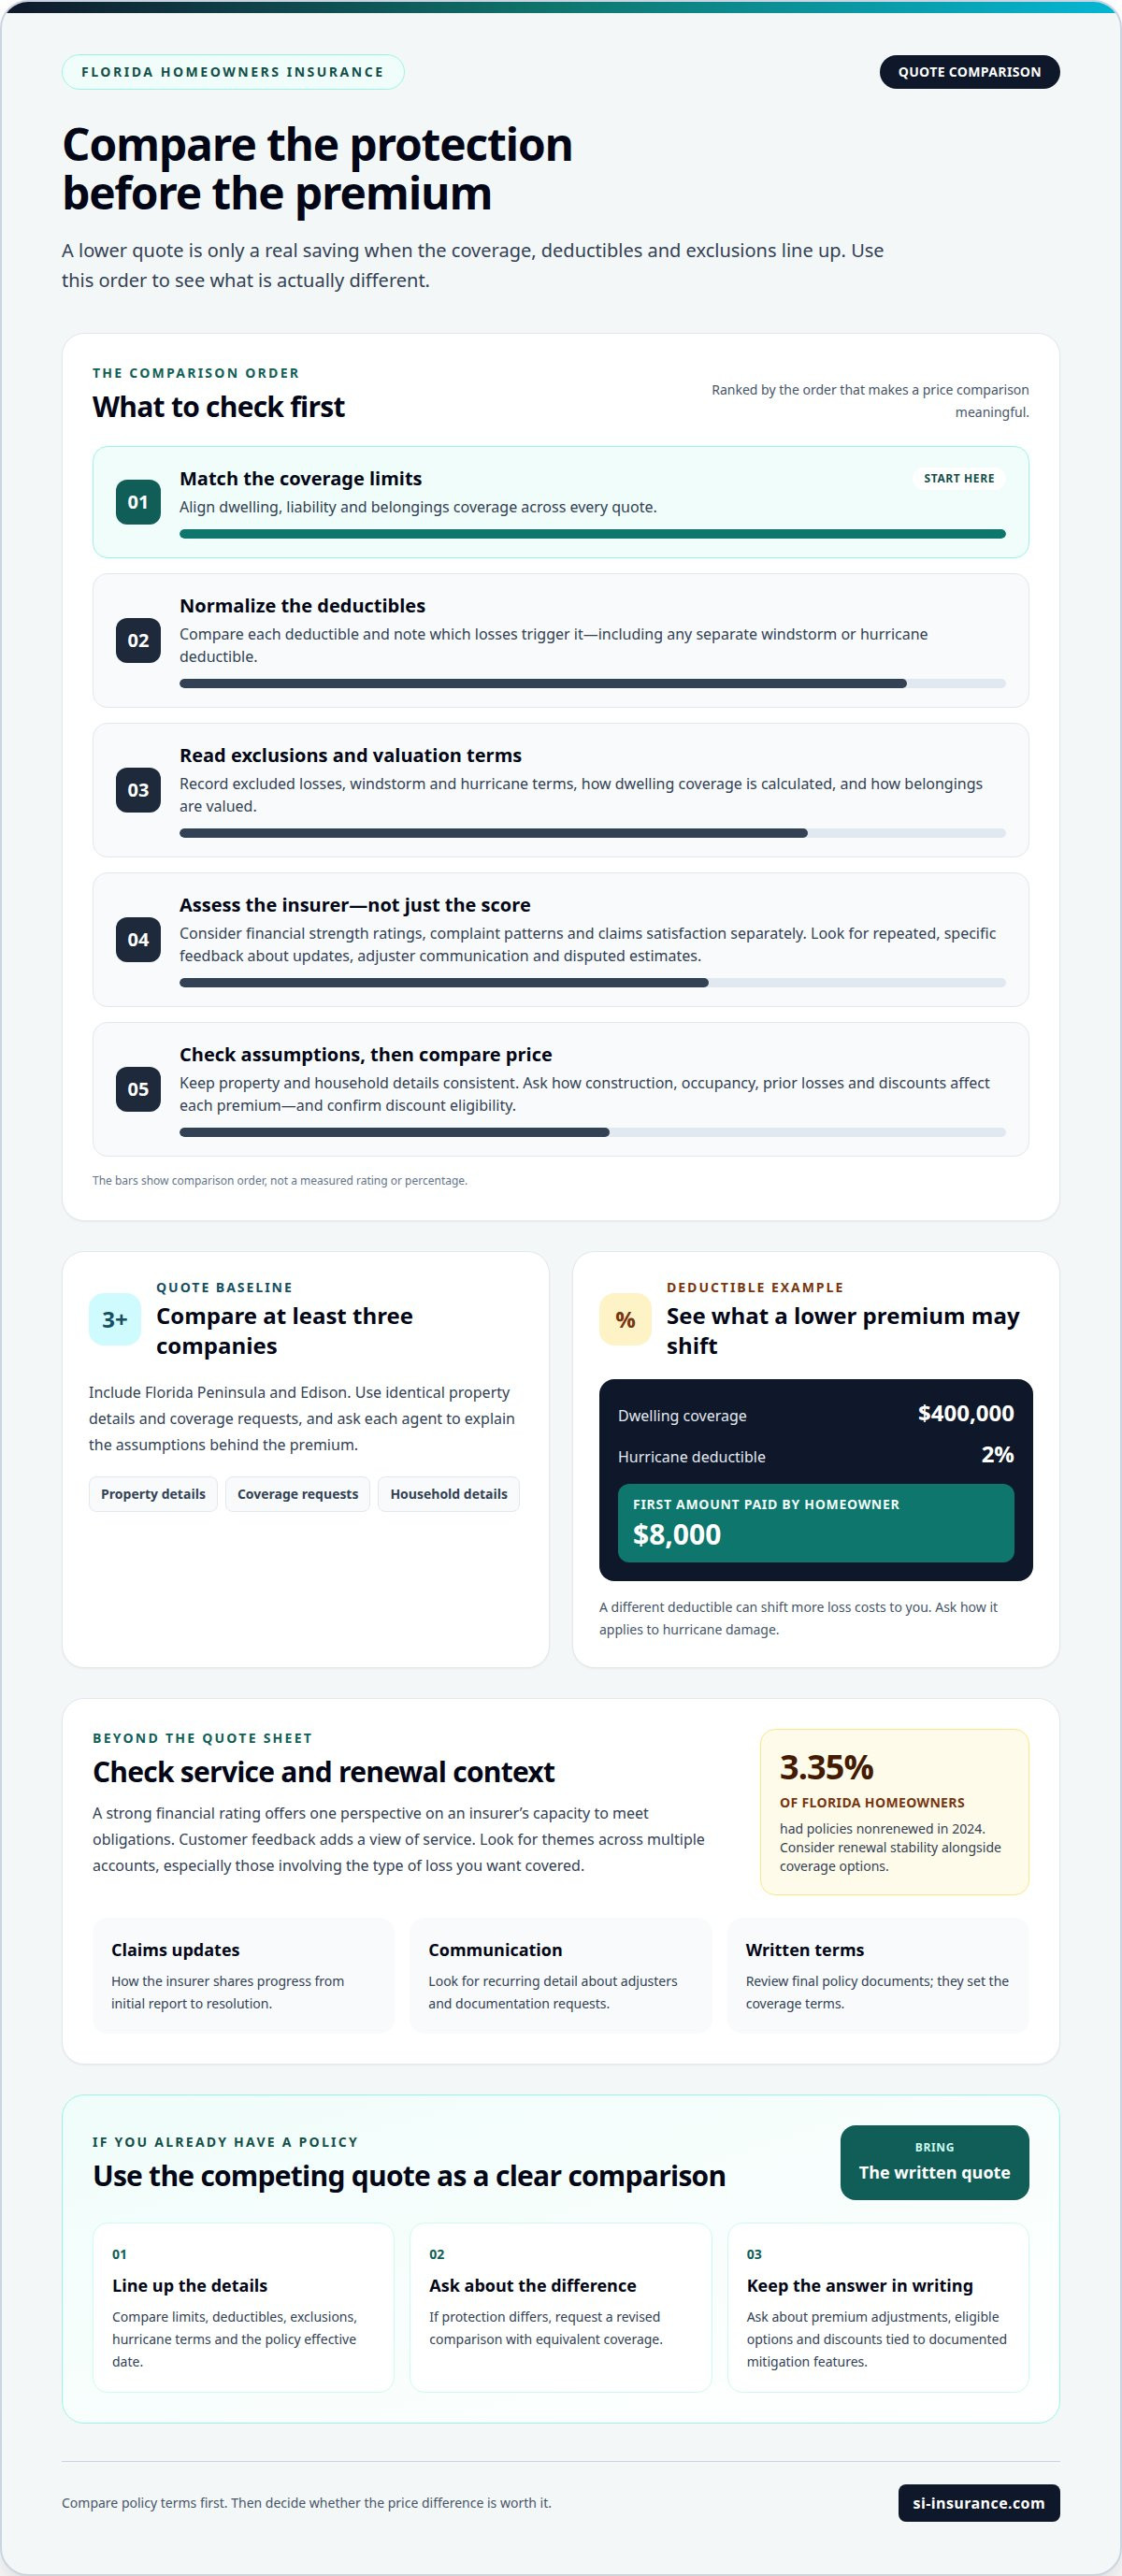
For Florida homeowners, reputation matters most when a claim requires clear decisions and steady communication. Compare each carrier’s financial strength ratings, complaint patterns, and claims satisfaction information rather than relying on a single overall score. A strong rating offers one perspective on an insurer’s capacity to meet obligations; customer feedback adds insight into service experiences. In 2024, 3.35% of Florida homeowners had their policies nonrenewed, making renewal stability another useful point to assess alongside coverage options.
Credit and claims history can affect a home insurance quote, so use the same household details when comparing offers. Ask how each carrier considers credit information, prior losses, and claim type or frequency. For example, disclose a prior water-damage claim consistently in every quote request. Compare discounts and eligibility, too. A discount can lower the premium, but it does not make policies equivalent if limits, deductibles, or exclusions differ.
Customer reviews can reveal practical details that broad satisfaction scores may miss. Look for recurring comments about claim updates, adjuster communication, documentation requests, and disputed estimates. Distinguish specific accounts from general praise or criticism: a detailed description of a roof claim is more useful than an unsupported claim that service was “good.” Reviews reflect individual experiences, so look for themes across multiple accounts and consider whether they involve the type of loss you want covered.
Before choosing a carrier, understand the claims process from initial report to resolution. Identify how to report a claim, what documents may be requested, and how the insurer shares updates. Keep the claim number, submitted materials, and follow-up notes together so you can track progress. Ask how support works when damage affects both the home and personal belongings, then compare the explanation with the policy terms. This connects reputation to the service you may need after a loss.
Comparing quotes from Florida Peninsula, Edison, and other carriers
Request homeowners insurance quotes from at least three companies, including Florida Peninsula and Edison. Use identical property details and coverage requests for each application. Differences in roof information, dwelling limits, or liability coverage can make offers difficult to compare. Ask each agent to explain the assumptions behind the premium, including construction, occupancy, and deductible choices. A comparison of alternatives to Florida Peninsula Insurance and their quotes is most useful when each carrier evaluates the same risk details.
Check exclusions and replacement-cost terms, not just the premium. Review how dwelling coverage is calculated and how belongings are valued—particularly for valuable collections such as coins and stamps that may require documentation or specialized storage from resources like renniks.com. Compare liability limits, deductibles, and any separate terms for windstorm or hurricane damage. Include association rules or mortgage requirements that affect the property in each request. This helps keep coverage consistent across carriers.
Florida Peninsula’s windstorm and hurricane coverage rates depend on the property and policy structure, including limits and deductibles. Compare policy terms line by line rather than assuming a lower premium means equivalent protection. Check whether a quote has a separate windstorm deductible and how it applies to the dwelling. Ask the agent to explain differences using the policy documents.
Coverage: Match dwelling limits, liability protection, and belongings coverage.
Exclusions: Record excluded losses and different windstorm or hurricane terms.
Deductibles: Compare each deductible and identify which losses trigger it.
Discounts: Ask which discounts apply and what eligibility conditions they require.
Review final policy documents, not preliminary estimates. A licensed agent can clarify coverage options, while the written policy sets the terms. If one quote costs less, identify whether a changed deductible, exclusion, or valuation basis explains the difference. Florida drivers are advised to obtain quotes from at least three companies; homeowners can use the same disciplined approach to distinguish price from protection.
Periodic comparisons matter beyond homeowners coverage. Drivers who have not compared Florida auto insurance rates recently could be overpaying by hundreds of dollars per year. Auto and home policies are different products, so review each separately, using matching details for the coverage requested and checking the written terms.
Asking a current insurer to match a competing quote
Use a written competing quote to start a specific discussion with your current insurer. Ask the agent to compare the premium with the other offer’s dwelling limit, liability coverage, deductibles, exclusions, and hurricane terms. If the policies differ, request a revised comparison with equivalent protection. This gives the insurer a clear basis for reviewing the price, rather than just a premium figure.
Prepare before contacting the company. Include the competing quote, policy effective date, and a short list of coverage differences. Point to details such as a higher windstorm deductible or lower limit for belongings. Ask whether the insurer can adjust the premium, change eligible coverage options, or apply discounts tied to documented mitigation features. Keep the responses in writing so you can compare revised terms with the original offer.
Check the deductible’s real effect before accepting a lower premium. For example, a Florida policy with $400,000 in dwelling coverage and a 2% hurricane deductible would require the homeowner to pay the first $8,000 of hurricane-related repairs. If the competing quote uses a different deductible, its lower premium may shift more loss costs to you. Ask the agent to show how each hurricane deductible applies, not just how it affects the annual premium.
Use a focused sequence:
Send the competing quote and identify the coverage items that match.
Ask the current carrier to review rating details, mitigation records, and available discounts.
Request revised terms in writing, including deductibles and exclusions.
Compare the revised offer with the competing policy’s financial strength and claims support.
An independent agent can explain how carriers evaluate a Florida home, including hurricane exposure and mitigation details. Keep your decision focused on equivalent protection. A premium match is useful only if the revised policy retains the coverage and terms that matter to your household.
How does Florida Peninsula Insurance compare with Citizens Property Insurance and other Florida insurers?
Compare Florida Peninsula, Citizens Property Insurance Corporation, Edison, and other carriers using the same coverage limits and property details. Citizens was created in 2002 by the Florida Legislature. That background distinguishes it from private carriers, but it does not establish which policy best fits a particular Florida home. Compare each written offer’s dwelling protection, deductibles, exclusions, liability limits, and renewal terms before weighing the premium.
Citizens eligibility has a specific price threshold: a Florida homeowner may qualify for Citizens coverage if premiums from other insurers are more than 20% higher than the Citizens rate. Apply that test to comparable coverage, not quotes with different limits or deductibles. For example, a private offer with a higher windstorm deductible cannot be treated as equivalent simply because its premium falls near the Citizens figure.
Also review Citizens takeout offers carefully. A Florida Peninsula takeout offer priced within 20% of the Citizens renewal estimate removes the option to remain with Citizens. Compare the offer’s effective date, coverage terms, and deductible structure against the renewal estimate before deciding. This threshold can affect the available choice, so keep both documents together and calculate the difference using the same basis.
Citizens: Compare eligibility, renewal terms, and the written coverage limits.
Florida Peninsula: Review any takeout offer against the Citizens renewal estimate.
Edison and other carriers: Compare equivalent limits, deductibles, exclusions, and premium terms.
Use a simple comparison sheet to record each carrier’s dwelling limit, liability protection, windstorm deductible, exclusions, premium, and renewal conditions. Mark any item that differs instead of treating the quotes as interchangeable. Then weigh the cost against the protection and terms actually offered. For a focused next step, review Florida home insurance options and compare them against your current Citizens or private-carrier documents.
Treat that protection as a separate comparison item rather than assuming it is included in a homeowners quote.
SI Insurance: Auto Insurance
SI Insurance helps Florida residents compare Auto Insurance options alongside broader household insurance needs. If you’re reassessing home coverage, the agency also offers Home Insurance, so you can discuss both needs through one agency. Motorcycle and Boat Insurance are available for households with those coverage needs.
Bring your current policy details and the coverage priorities you identified. Clear information about vehicles, drivers, and desired protection helps guide a more relevant Auto Insurance discussion. If you’re comparing home policies, a separate Home Insurance review keeps property protection in view without assuming the policies share terms or pricing.
Contact SI Insurance to discuss your insurance needs, or visit the SI Insurance website.
Make your next renewal decision with confidence
Make your next step a documented decision, not simply a reaction to a renewal notice. Keep your coverage priorities with the written offers, then use them to focus the discussion on what fits your household. A Florida Peninsula Insurance alternatives and quote comparison is most useful when it helps you explain why a policy’s terms meet your needs.
SI Insurance offers Auto Insurance, Motorcycle Insurance, and Boat Insurance for Florida residents reviewing protection across their household. If you’re ready to discuss quote options and your coverage priorities, contact SI Insurance to compare quotes. A clear starting point can make the next insurance decision more deliberate and easier to evaluate.
Frequently Asked Questions
Which home insurance companies offer alternatives to Florida Peninsula Insurance in Florida?
Florida homeowners can compare Florida Peninsula with Edison, Citizens Property Insurance Corporation, and other carriers that write home policies in their area. Availability and eligibility depend on property details and underwriting criteria, so compare written offers rather than assuming every carrier will quote every home. To begin, note your preferred dwelling and liability limits, then discuss Home Insurance options for your Florida home with Si Insurance Agency.
Comments