


Home Insurance in Pompano Beach: A Strategic Approach to Coastal Protection (2026)
For the first time in years, the narrative of Florida's property market is shifting from crisis management to strategic opportunity. Securing home insurance in Pompano Beach no longer feels like a desperate search for any carrier willing to sign, but rather a calculated exercise in elite risk mitigation. You've likely felt the weight of rising premiums and the frustration of navigating complex hurricane deductibles, especially if you're managing a property with an older roof. It's a high-stakes environment where the difference between a generic policy and a meticulously engineered strategy can mean significant annual savings.
This guide explores how the 2026 market stabilization, marked by rate reductions from major carriers like State Farm and Citizens, allows you to secure robust protection that balances cost with comprehensive coverage. We'll demystify the interplay between wind and flood requirements while providing a roadmap for finding a local partner to manage your renewal. By the end of this analysis, you'll have the intellectual confidence to transform your insurance into a sophisticated shield for your coastal assets. We'll examine the specific data points and legislative reforms that are finally putting power back into the hands of Pompano Beach homeowners.
Table of Contents
Navigating the Pompano Beach Home Insurance Landscape in 2026
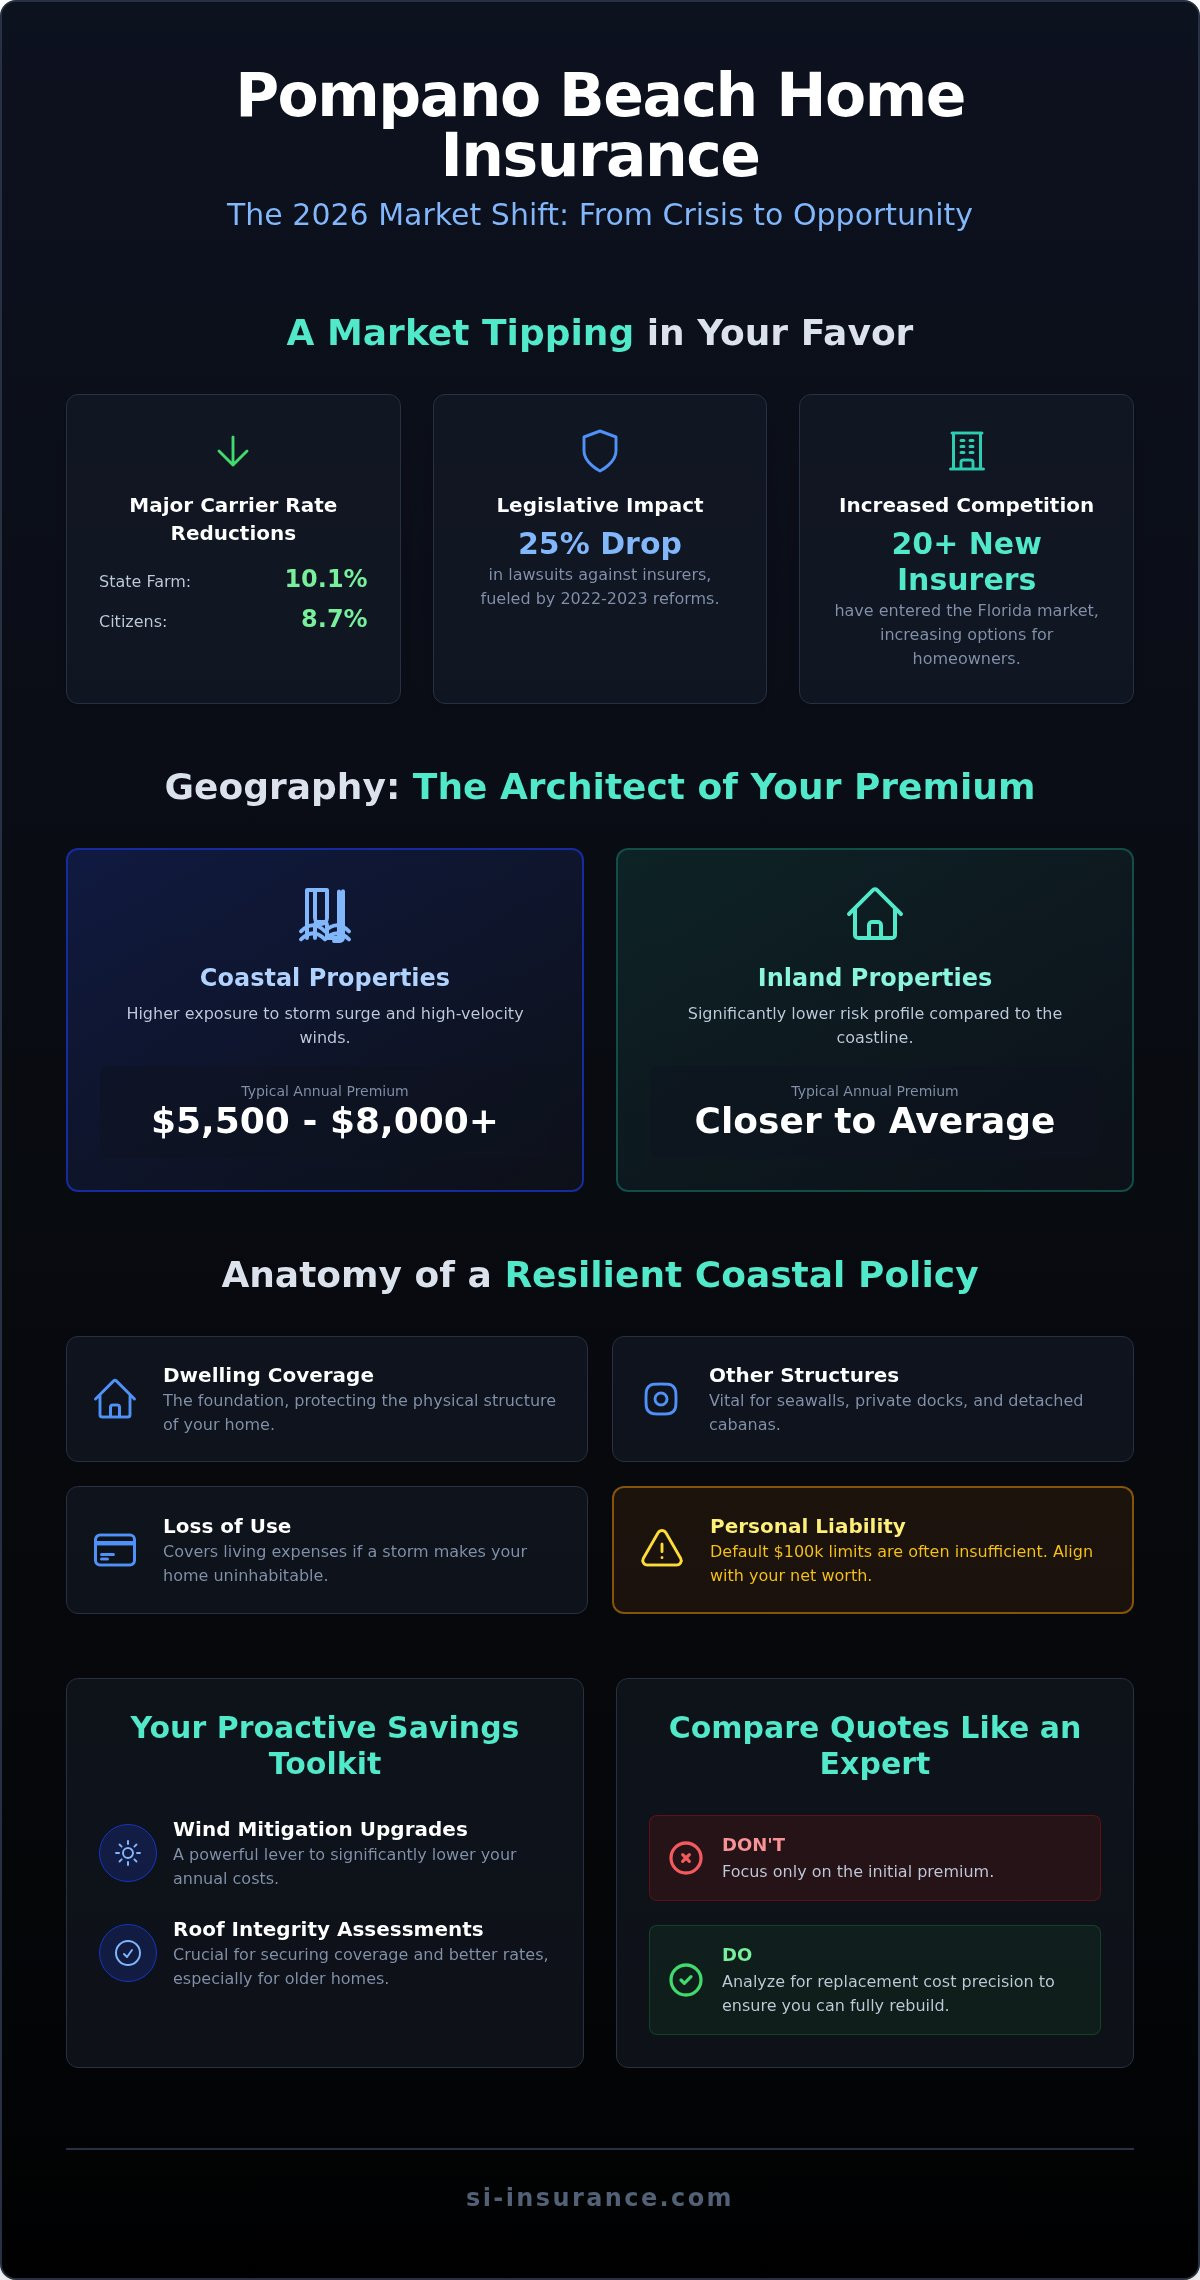
The 2026 property market in Florida is witnessing a pivot that few expected just a few years ago. After a period of extreme volatility, we're seeing a calculated stabilization that directly benefits the discerning homeowner. For those seeking home insurance in Pompano Beach, the landscape is no longer defined by scarcity but by competition. Major carriers like State Farm and Citizens have implemented rate reductions of 10.1% and 8.7% respectively, reflecting a healthier environment following the 2022 and 2023 legislative reforms. This shift means that protecting your home is now less about finding any available policy and more about engineering a precise risk management strategy.
Home insurance in Pompano Beach is best defined as a specialized financial structure designed to protect high-value coastal assets against the unique atmospheric and geological risks of South Florida. It's a shield for your equity, ensuring that whether you're facing a localized flood event or a major hurricane, your financial recovery is guaranteed through airtight policy language. In this environment, an independent agent serves as your strategic buffer, filtering through the noise of over 20 new insurers that have entered the market to find the one that aligns with your long-term security goals.
The Interplay of Coastal Geography and Premiums
Geography is the primary architect of your premium. If your property sits near the Hillsboro Inlet or along the oceanfront, your risk profile is fundamentally different from a home in the Highlands. Proximity to the Intracoastal Waterway often necessitates a more nuanced approach to understanding home insurance coverage, particularly regarding flood and wind-driven rain. While inland properties might see premiums closer to the lower end of the South Florida average, coastal homes often command $5,500 to $8,000 or more because of their exposure to storm surges and higher wind velocities. We analyze these street-level variables to ensure your coverage isn't just generic, but geographically precise.
Why 2026 Requires a New Approach to Coverage
The market's stabilization doesn't mean you should settle for a "set it and forget it" mindset. Lawsuits against property insurers dropped by 25% in 2025 and continued that trend into early 2026, which has directly led to the rate decreases we see today. This evolution requires a local partner like Si Insurance Agency who acts as a strategic intermediary. We help you move beyond basic protection to a plan that considers the specific street-level risks of your neighborhood. Annual policy reviews are now essential, as they allow us to capture the benefits of these rate reductions and the arrival of new, more aggressive carriers in the Broward County market.
Essential Coverage Components for South Florida Homeowners
A standard HO-3 policy serves as the foundation for most home insurance in Pompano Beach, yet its off-the-shelf configuration rarely suffices for the complexities of a coastal estate. While the primary dwelling coverage is the centerpiece, sophisticated risk management requires a deep dive into ancillary protections. For instance, the "Other Structures" provision is vital for residents with significant investments in seawalls, private docks, or detached cabanas. These coastal amenities are often undervalued in generic quotes, leading to substantial out-of-pocket losses following a localized event. Similarly, "Loss of Use" coverage acts as a critical financial bridge; it ensures that if a storm renders your property uninhabitable, your temporary living expenses are fully subsidized without depleting your personal reserves.
Your personal liability limits should also be scrutinized against your total net worth. In a litigious environment, the default $100,000 limit offered by many carriers is often insufficient for high-value households. We recommend aligning these limits with your broader financial portfolio to ensure your assets remain protected against unforeseen legal claims. If you're unsure if your current limits are adequate, reviewing your current policy structure with a specialist can help identify these hidden vulnerabilities before they become liabilities.
The Critical Distinction: Wind vs. Flood Insurance
One of the most dangerous misconceptions in South Florida is the belief that a standard homeowners policy covers all water damage. It's vital to understand that while your policy typically covers wind-driven rain, it strictly excludes damage from rising water or storm surges. This gap makes a separate policy through the National Flood Insurance Program or a private flood carrier a strategic necessity for every Pompano Beach resident. Coordinating these two distinct policies is essential to avoid "finger-pointing" between carriers during the claims process. We focus on ensuring your wind and flood coverages are synchronized so that no matter how the water enters your home, your recovery is funded.
Hurricane Deductibles: A Strategic Financial Decision
Unlike standard flat-fee deductibles for fire or theft, hurricane deductibles in Florida are calculated as a percentage of your home's total insured value. Common structures include 2%, 5%, or 10% options. For a home insured for $600,000, a 2% deductible means you're responsible for the first $12,000 of a claim. It's a significant out-of-pocket exposure that requires careful liquidity planning. You can learn more about the nuances of hurricane deductibles in Florida to determine which threshold strikes the right balance between your annual premium savings and your risk tolerance during storm season.
Strategic Rate Mitigation: Wind Inspections and Roof Integrity
Wind mitigation is a primary premium driver that evaluates a property's structural resilience against high-velocity wind events to determine applicable insurance credits. While broader market shifts provide a general downward pressure on rates, your home's specific engineering is what ultimately dictates the cost of home insurance in Pompano Beach. Carriers no longer rely solely on regional data; they prioritize the empirical evidence provided by professional inspections to assess how a building will perform under extreme atmospheric stress. If your property hasn't been inspected in the last three years, you're likely overpaying for risk that has already been mitigated through modern building standards.
Maximizing Your Wind Mitigation Credits
A professional wind mitigation inspection is the most effective tool for lowering your annual overhead. For properties that have reached the 20-year mark, carriers typically require a Four-Point Inspection to verify the integrity of the roof, electrical, plumbing, and HVAC systems. We focus on identifying key structural enhancements that trigger the highest tier of credits. Specifically, the presence of a secondary water barrier and the use of hurricane clips or wraps rather than simple toe-nails can drastically alter your risk profile. As we analyze Florida's home insurance market stabilization, it's clear that underwriters are increasingly rewarding homeowners who document impact-resistant openings and superior roof-to-wall connections with significantly lower premiums.
Roof Lifecycle Management for Insurance Eligibility
Roof integrity acts as the ultimate gatekeeper for market access. In 2026, carrier standards for roof age have become more rigid, even as the overall market stabilizes. For homes with asphalt shingles, the window for competitive home insurance in Pompano Beach often begins to close once the material reaches 15 years of age. While tile and metal roofing systems offer greater longevity, typically remaining eligible for 25 to 30 years, carriers still demand proof of professional maintenance and the absence of granular loss or cracked tiles.
Managing the transition between an aging roof and a new policy requires a proactive methodology. You shouldn't wait for a non-renewal notice to arrive before considering a replacement. By conducting a roof certification before your renewal period, you can demonstrate to potential carriers that your home remains a high-value, low-risk asset. This foresight ensures you maintain access to the full spectrum of private market insurers rather than being forced into higher-priced residual markets due to perceived structural vulnerability.
How to Compare Pompano Beach Home Insurance Quotes Effectively
The process of evaluating home insurance in Pompano Beach requires a shift from viewing premiums as a commodity to analyzing them as a strategic financial investment. It's tempting to select the lowest annual figure, but a lower price often hides an inadequate dwelling replacement cost calculation. If your home is undervalued on paper, you'll face a significant funding gap when rebuilding after a total loss. We look for A-rated carriers that demonstrate long-term stability; price is one factor, but claims-paying reputation is the true measure of a policy's value. Bundling your property coverage with other lines remains a foundational strategy for optimizing your total insurance spend while simplifying your risk portfolio.
Beyond the Premium: Analyzing Policy Limits
A sophisticated comparison looks deep into the Replacement Cost Value versus Actual Cash Value for your personal property. In Pompano Beach, where high-value coastal assets are common, settling for actual cash value means the insurer will deduct depreciation from your settlement. We also prioritize Increased Cost of Construction coverage, also known as Ordinance or Law. This is vital for older properties that must meet updated 2026 building codes during a repair. You can further refine your strategy by exploring the benefits of bundling home and auto insurance in Florida to capture maximum multi-policy credits.
Leveraging Local Expertise in the Quote Process
The geography of Pompano Beach creates micro-markets that generic online algorithms often fail to capture. A property three blocks from the beach faces different underwriting criteria than a home west of the Intracoastal. We use our local presence to provide a superior underwriting perspective that accounts for these street-level variations. As an independent agency, we access a network of carriers to find the most competitive fit for your specific neighborhood. We also identify hidden discounts that external brokers might miss, such as credits for residing in a gated community or having a centrally monitored alarm system. To ensure your protection is engineered for your specific needs, request a personalized quote analysis today.
Securing Your Investment with Si Insurance Agency
Si Insurance Agency operates as a strategic intermediary in a market that often feels overwhelming to the individual property owner. We don't merely facilitate transactions; we act as a dedicated risk management partner for those seeking home insurance in Pompano Beach. Our methodology is rooted in the concept of coverage engineering, where every policy is meticulously assembled to align with your specific financial goals and the unique physical attributes of your property. By maintaining our status as an independent agency, we preserve the intellectual freedom to compare a diverse network of carriers, ensuring that your long-term security is never compromised by the limitations of a single provider's appetite for risk. Our commitment to the Pompano Beach community is reflected in our focus on localized expertise, where we translate global market trends into actionable, street-level protection for your most valuable assets.
Our Meticulous Approach to Your Security
The progression from initial risk assessment to the final issuance of a policy is a disciplined, step-by-step process designed to instill absolute peace of mind. We begin by deconstructing your current coverage to identify vulnerabilities that generic algorithms often overlook, such as inadequate limits for coastal amenities or gaps in liability protection. This leads to a targeted search within our carrier network to find the precise match for your home's age, roof integrity, and proximity to the coast. We understand that the Florida market can be a source of significant stress for homeowners, but we simplify the intricate aspects of underwriting so you can feel absolute confidence in your protection. Having a calm, calculated partner allows you to focus on your lifestyle while we manage the complexities of specialized risk mitigation through rigorous analysis.
Your Next Steps Toward Absolute Protection
Initiating a strategic consultation is a straightforward yet vital step in securing your coastal assets for the years ahead. To facilitate a comprehensive quote review, we recommend preparing your current policy's declarations page and any recent wind mitigation or four-point inspection reports you've had performed. These documents provide the empirical data our consultants need to engineer a more cost-effective and robust solution for your home insurance in Pompano Beach. Whether you prefer to visit our offices in Pompano Beach or Sunrise, or engage with us through a professional digital consultation, our team is prepared to provide the elite level of service your investment deserves. Request your strategic home insurance quote from Si Insurance Agency today and experience a partnership defined by foresight, stability, and technical mastery.
Advancing Your Coastal Protection Strategy
The stabilization of the Florida property market in 2026 presents a significant opportunity for homeowners to transition from reactive coverage to a proactive risk management plan. By leveraging recent legislative reforms and documented structural improvements, you can navigate the complexities of home insurance pompano beach with absolute clarity. It's no longer just about meeting mortgage requirements; it's about engineering a financial shield that accounts for every variable from roof attachment methods to street-level flood risks. As an independent agency with deep roots in Broward County, we provide the elite consultation needed to match your property with the most resilient carriers in the state.
Our sophisticated approach ensures that your policy is as unique as your coastal investment. We invite you to secure your Pompano Beach home with a strategic quote from Si Insurance Agency and experience the reassurance of a truly personalized protection plan. Taking this step now safeguards your equity against the unpredictable while positioning you to benefit from the market's current downward rate trends. We look forward to acting as your protective guardian in this evolving market.
Frequently Asked Questions
Is homeowners insurance mandatory in Pompano Beach if my home is paid off?
While Florida law doesn't require insurance for homes without a mortgage, it's a high-risk gamble to leave your primary asset unprotected. Without a policy, you're personally liable for any catastrophic loss caused by fire or storms. For most residents, home insurance in Pompano Beach acts as a vital safeguard for their hard-earned equity. We recommend maintaining coverage to ensure your financial stability remains intact regardless of unpredictable atmospheric events.
How does living east of Federal Highway affect my home insurance rates?
Properties located east of Federal Highway are generally classified as higher risk due to their immediate exposure to coastal wind velocities and storm surges. Underwriters view these zones with increased scrutiny, which often results in higher premiums compared to inland neighborhoods like the Highlands. This geographic reality necessitates a more sophisticated approach to risk management. We help clients navigate these street-level variables to find carriers that offer the most competitive rates for oceanfront properties.
What is the difference between a hurricane deductible and a standard deductible?
A standard deductible is a fixed dollar amount, such as $1,000 or $2,500, that applies to common perils like fire or theft. In contrast, a hurricane deductible is calculated as a percentage of your home's total insured value, typically ranging from 2% to 10%. This means your out-of-pocket exposure significantly increases during a named storm. Understanding this distinction is crucial for your liquidity planning and overall financial security during the South Florida storm season.
Does a standard homeowners policy in Pompano Beach cover flood damage?
No, a standard HO-3 homeowners policy strictly excludes damage resulting from rising water or storm surges. This is a critical gap for Pompano Beach residents who live near the Intracoastal or Atlantic. To protect your home from these events, you must secure a separate Flood Insurance policy through the National Flood Insurance Program or a private provider. We coordinate these two distinct coverages to ensure your property has a comprehensive, airtight shield against all water-related risks.
How can a wind mitigation inspection lower my annual insurance premium?
A wind mitigation inspection provides empirical evidence of your home's structural resilience, which carriers use to apply mandatory premium credits. By documenting features like hurricane clips, secondary water barriers, and impact-resistant windows, you can significantly reduce the cost of home insurance in Pompano Beach. Many homeowners find that the savings from these credits far outweigh the initial cost of the inspection. It's an essential step for any property owner looking to optimize their annual insurance spend.
What steps should I take if my home insurance is non-renewed due to roof age?
If you receive a non-renewal notice, your first step should be to obtain a professional roof certification to document its remaining useful life. While some carriers are rigid about the 15-year mark for shingles, others may offer flexibility if the roof is in superior condition. As an independent agency, we can search our network for carriers that specialize in insuring older homes. Proactively managing this transition ensures you maintain continuous coverage and avoid the higher costs of residual markets.
Can I bundle my Pompano Beach home insurance with my auto policy for a discount?
Yes, bundling your property and auto coverage is one of the most effective strategies for capturing multi-policy discounts. Most top-tier Florida carriers offer significant premium reductions when you place multiple lines of business with them. Beyond the financial savings, bundling simplifies your risk management by centralizing your policies under a single point of contact. We analyze your total insurance portfolio to ensure you're maximizing every available credit while maintaining robust protection for all your assets.
How often should I review my home insurance policy with a local agent?
We recommend a comprehensive policy review at least once every twelve months, ideally 60 days before your renewal date. The Florida market is evolving rapidly in 2026, with new carriers entering the state and established ones implementing rate cuts. A local agent who understands Broward County's specific risk zones can identify new opportunities for savings or coverage enhancements. Regular consultations ensure your protection plan keeps pace with both market shifts and any physical changes to your property.
Comments