


Life Insurance in Florida: A Strategic Guide to Family Security (2026)
If you were to step away tomorrow, would your family inherit the life you've built together, or would they be left to manage a complex web of liabilities in an increasingly expensive state? You've likely felt the weight of Florida's rising cost of living and the quiet anxiety that comes with choosing between various life insurance florida options. It's a high-stakes decision that often feels buried under industry jargon and fine print, but it's one that ultimately defines your family's future stability.
We understand that you aren't just looking for a policy; you're seeking a sophisticated risk management strategy that protects your loved ones from debt. This guide provides a meticulous evaluation of available structures to help you secure your family's financial legacy with absolute precision. We'll examine the strategic differences between policy types, establish a reliable methodology for calculating your coverage needs, and provide the clarity required to transform a complex financial obligation into a cornerstone of permanent security.
Table of Contents
Understanding the Strategic Role of Life Insurance in Florida
Securing a robust financial foundation in the Sunshine State requires more than just traditional savings. For many residents, life insurance florida serves as a fundamental pillar of long-term stability, acting as a deliberate safeguard against the state's unique economic pressures. Property values in South Florida continue to climb. The general cost of living impacts future savings. A well-structured policy functions as a critical hedge. It isn't merely about a payout; it's about engineering a financial legacy that can withstand inflationary shifts and ensure your family's standard of living remains uninterrupted.
The tax-free death benefit is a core component of this strategy. This liquidity provides immediate relief when it's needed most, allowing beneficiaries to settle obligations, such as estate taxes or final expenses, without liquidating long-term assets. This preservation of capital is essential for maintaining the integrity of your overall financial structure. For a deeper look at the foundational concepts of these policies, Understanding Life Insurance offers a neutral overview of how these structures have evolved into essential risk management tools.
To better understand the mechanics of how these policies are structured and evaluated, watch this helpful video:
Why Florida Families Prioritize Life Coverage
Florida's landscape presents specific risks that make coverage a priority. Families often hold high-value real estate investments in South Florida, where a mortgage represents a significant portion of their monthly outflow. Without a strategic plan, an untimely passing could force a hasty sale of a family home. Broward County is also a hub for local entrepreneurs who rely on life insurance florida to ensure business continuity. Whether you're providing for young dependents or managing the needs of a multi-generational household, life coverage ensures that the financial engine of your family doesn't stall.
The Interplay Between Life and Other Insurance Pillars
Strategic security is never found in a single policy; it’s the result of how different coverages work together to create a comprehensive safety net. For instance, life insurance directly complements your Florida home insurance by providing the funds necessary for a complete mortgage payoff. This ensures the physical asset you've insured is actually kept by your loved ones rather than being lost to foreclosure. There's also a strong connection between personal security and business insurance in Broward County. A life policy can fund buy-sell agreements or protect against the loss of a key person, ensuring that your professional endeavors and personal legacy remain securely aligned and financially viable for years to come.
Evaluating Your Options: Term vs. Permanent Life Insurance
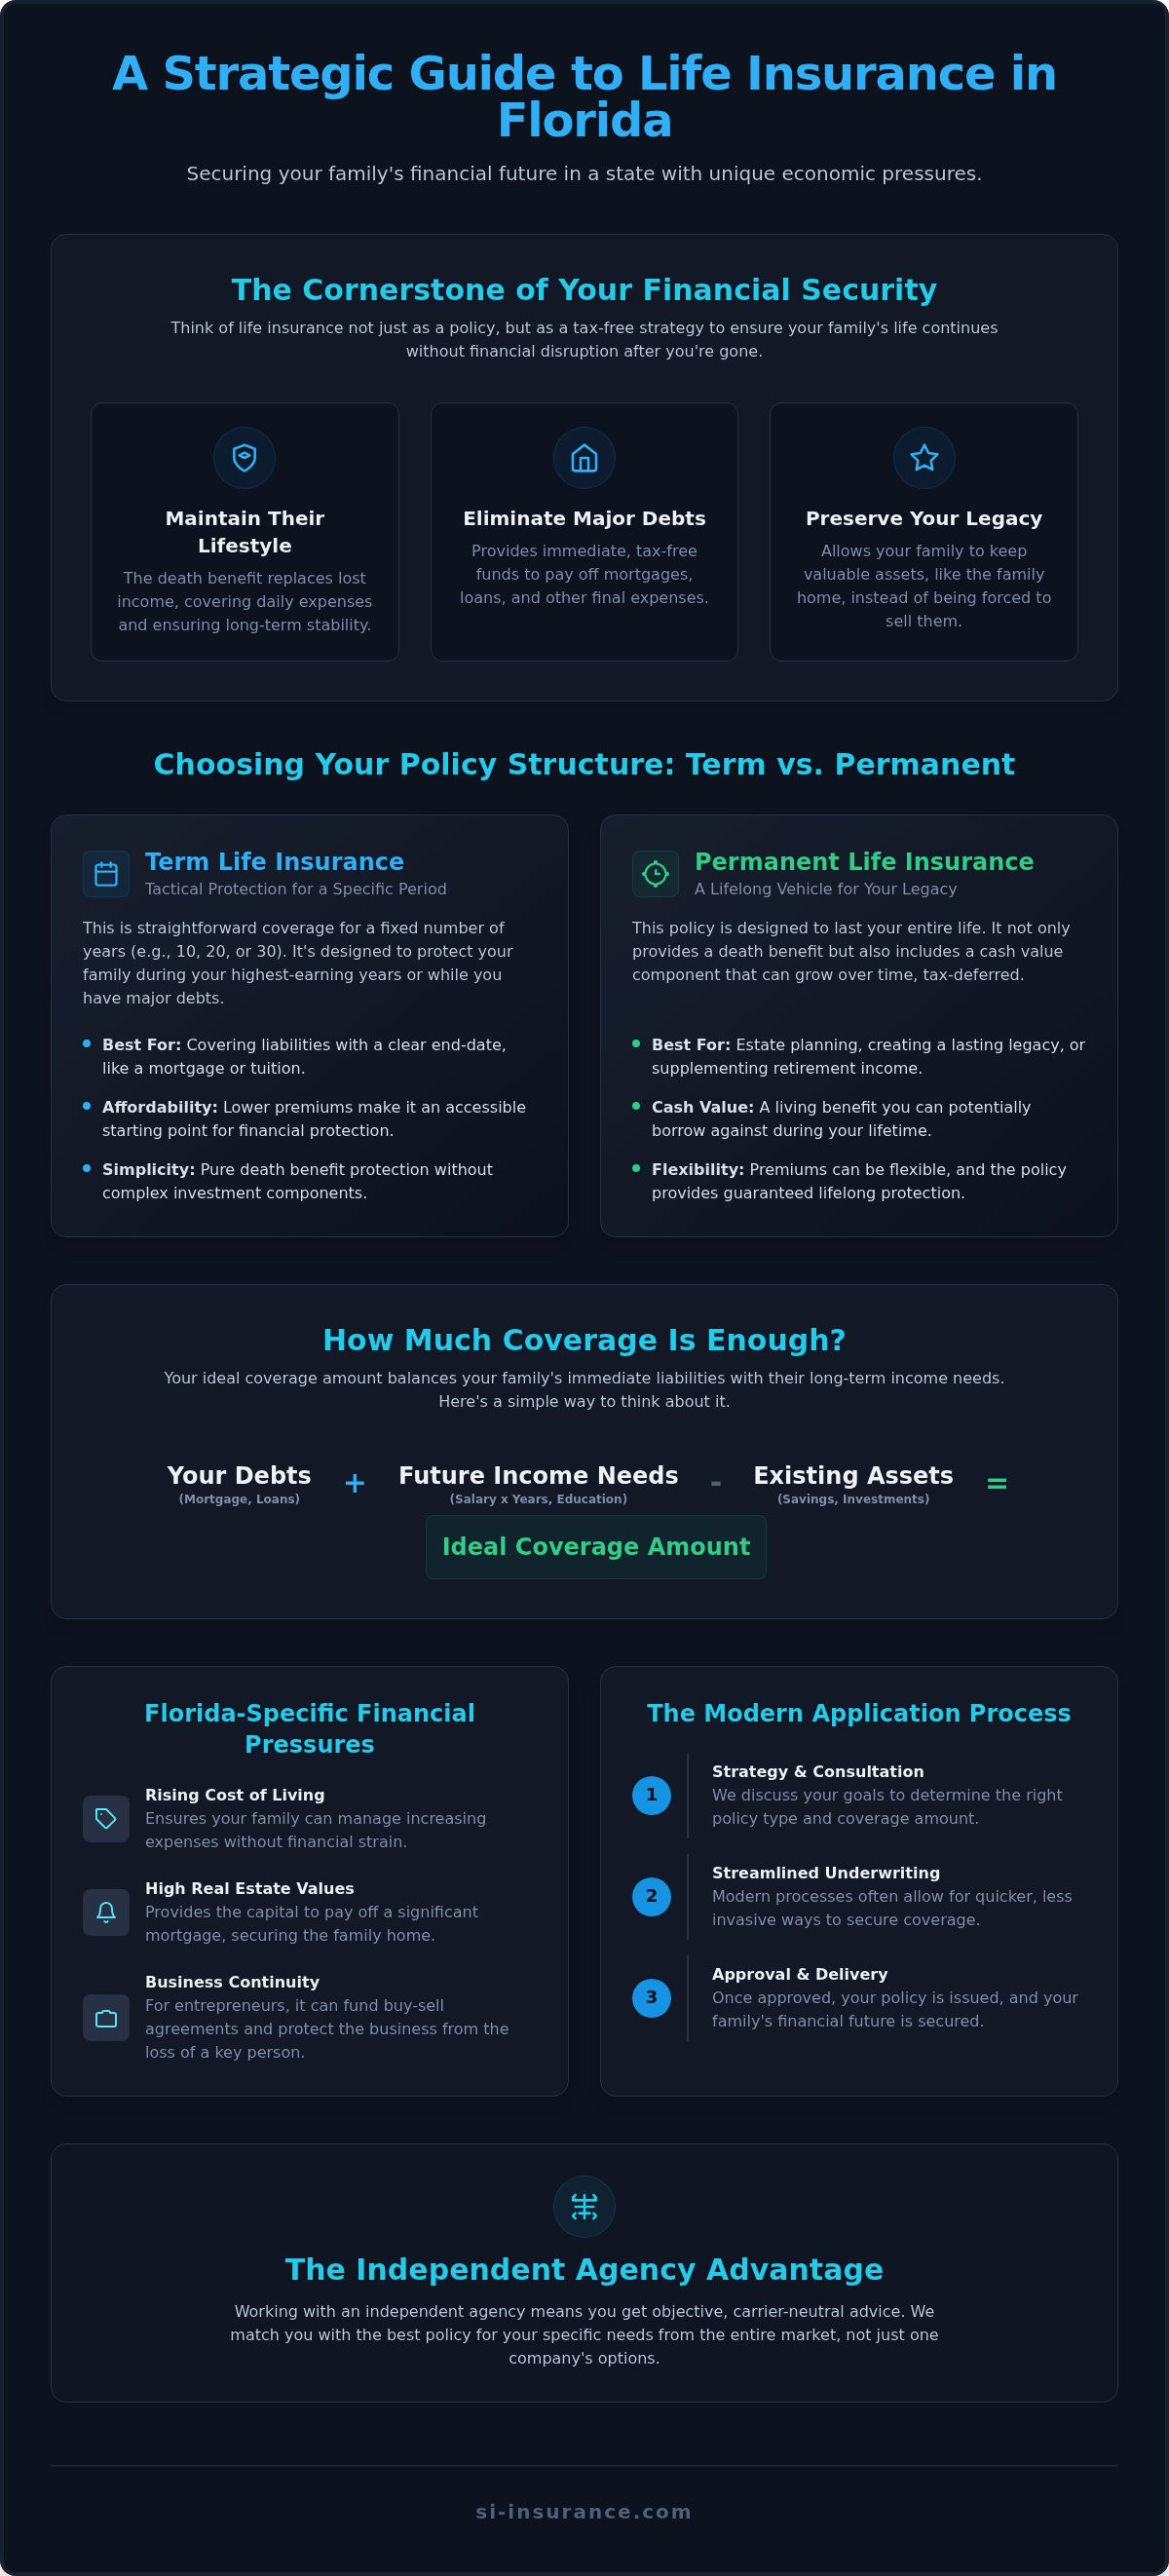
Choosing the right financial structure for your family isn't a decision to rush. It requires a methodical approach that aligns your current liabilities with your long-term vision. When exploring life insurance florida, you'll generally choose between two primary architectures: term and permanent. The selection process involves more than just comparing premiums. It's about determining if your needs are temporary, such as covering a mortgage, or if you require a permanent vehicle for legacy preservation.
Choosing the right type of life insurance depends heavily on your current stage of life and your specific financial objectives. For many, the goal is to bridge a gap until assets are fully grown. For others, the priority is ensuring a guaranteed transfer of wealth regardless of when the policy is called upon. Each structure offers distinct advantages depending on how you view your family's timeline.
Term Life Insurance: Tactical Protection
Term life insurance provides straightforward protection for a predefined period, typically 10, 20, or 30 years. It’s a tactical tool designed to cover significant, time-sensitive obligations. If you're a young family in Sunrise or Pompano Beach, this is often the most efficient way to secure a high coverage amount for a manageable initial cost. It’s particularly effective for ensuring a 30-year mortgage is paid off or that children's education is funded if you aren't there to provide. Once the term expires, the coverage ends, making it a focused solution for specific risks.
Permanent Life Insurance: Strategic Wealth Preservation
Permanent life insurance offers a more complex, lifelong security model that includes a cash value component. Whole life insurance is the traditional choice, providing guaranteed death benefits and fixed premiums that never increase. If you require more adaptability, Universal life insurance allows you to adjust your premiums and death benefits as your financial situation evolves. This flexibility is a significant advantage as your income or family needs change over the decades. The cash value within these policies grows over time, serving as a strategic asset for long-term stability. This structure is ideal for those focused on estate planning or protecting high-value assets from future market volatility.
Determining which path fits your unique profile can be complex, but you don't have to decide alone. Our team at Si Insurance Agency can help you evaluate these structures to find the one that best serves your family's future.
Calculating the Ideal Coverage Amount for Your Florida Lifestyle
Precision is the hallmark of a well-engineered financial plan. When determining the scope of your life insurance florida policy, a generic estimate often falls short of providing absolute security. You need a calculation that accounts for the nuances of your lifestyle while avoiding the unnecessary drain of excessive premiums. This isn't just about picking a number; it's about conducting a rigorous analysis of your family's actual requirements over the next several decades. Under-insuring can leave your loved ones in a precarious position, while over-insuring misallocates capital that could be used elsewhere in your portfolio.
The DIME method serves as a foundational framework, standing for Debt, Income, Mortgage, and Education to provide a comprehensive baseline for coverage needs. However, a truly effective life insurance florida strategy must also account for local economic realities. High property values and the unique cost of living in Broward County mean that a standard calculation might leave your family vulnerable. You have to look at the specific reality of maintaining a home in Sunrise or Pompano Beach, where property taxes and maintenance costs often exceed national averages. This localized perspective ensures your coverage is as accurate as it is protective.
Immediate and Ongoing Financial Obligations
Your strategy should first address immediate liquidity needs. This includes final expenses and any outstanding medical bills that could otherwise burden your estate. Beyond these one-time costs, the most significant factor is income replacement. How many years of your salary would your spouse or children need to maintain their quality of life? You also need to account for recurring liabilities, such as Florida auto insurance premiums and other essential household expenses. By incorporating these ongoing costs into your calculation, you ensure that your family isn't forced to compromise their lifestyle during a difficult transition.
Future Goals and Legacy Planning
A truly sophisticated plan looks far beyond immediate needs. If you have children or grandchildren, you'll want to factor in the rising costs of tuition at Florida institutions. Providing for their education is a cornerstone of many family legacies. You might also consider the role of life insurance in charitable giving or providing an inheritance that isn't eroded by estate taxes. For local entrepreneurs, coverage is often the primary vehicle for funding business buy-sell agreements. This ensures that your business partners have the capital to buy out your shares, providing your family with fair value while keeping the company stable. This level of planning transforms a simple policy into a strategic asset for multi-generational wealth.
Navigating the Life Insurance Application Process in the Sunshine State
Securing a policy is a deliberate sequence of events designed to assess risk with surgical precision. When you apply for life insurance florida, you're entering a formal evaluation where transparency is your most valuable asset. It's a common misconception that the process is designed to find reasons for a denial. In reality, modern underwriting seeks to categorize your health and lifestyle accurately so that your premiums reflect your actual risk profile. Working with a local agent in Sunrise or Pompano Beach ensures that your application is handled with a level of personalized care that automated platforms simply cannot replicate.
The Underwriting and Medical Examination Phase
The underwriting phase is where the insurance carrier evaluates your medical history and current physical health. While some traditional policies still require a brief physical examination, including blood work and blood pressure readings, the landscape has shifted significantly. In 2026, we've seen a widespread move toward "accelerated underwriting" for healthy applicants. This methodology uses data analytics to bypass the medical exam entirely for those who meet specific criteria, often resulting in a policy approval within days rather than weeks. If an exam is required, your risk classification will be determined by several factors:
Medical History: A review of past diagnoses, surgeries, and prescription usage.
Lifestyle Choices: Evaluation of tobacco use, high-risk hobbies, and driving records.
Current Vital Signs: Data points gathered during the physical, if applicable.
It's vital to be entirely forthcoming during this stage. Florida law includes a two-year contestability period. If a carrier discovers material misrepresentations during this window, they may have grounds to challenge a future claim, which could jeopardize the very security you're trying to build.
Finalizing Your Policy and Selecting Beneficiaries
Once your application is approved, the finalization step involves more than just a signature. You'll need to designate primary and contingent beneficiaries with absolute clarity. Primary beneficiaries are first in line, while contingent beneficiaries act as a secondary safeguard if the primary is unable to receive the benefit. This structure ensures your legacy is protected against unforeseen circumstances. You'll also have a 14-day "free look" period, mandated by Florida insurance regulations, which begins the day you receive the policy. This allows you to review the final terms and cancel for a full refund if the policy doesn't meet your expectations. We recommend establishing a regular review schedule to keep your coverage aligned with life changes like marriage, the birth of a child, or a significant career move.
If you're ready to move forward with a plan tailored to your specific needs, you can start your application with Si Insurance Agency today to ensure your family's protection is handled with the expertise it deserves.
Securing Your Legacy with Si Insurance Agency
Choosing a partner for your family's protection is a decision that carries significant weight. When you evaluate life insurance florida providers, you're looking for more than a simple transaction; you're seeking a protective guardian for your financial future. At Si Insurance Agency, we act as elite consultants who specialize in matching your unique needs with top-tier carriers. We don't believe in generic solutions because we know your family's goals are specific and high-value. Our approach bridges the gap between complex financial structures and genuine, human-centric service, ensuring you feel confident in every decision you make.
Our presence in Sunrise and Pompano Beach isn't just about having a physical office. It's about being accessible whenever your strategy needs an adjustment. Life changes, and your insurance should evolve along with it. Whether you're welcoming a new family member or expanding your business interests in Broward County, we're here to provide the steady, calculated guidance you need to maintain absolute security.
The Advantage of an Independent Florida Agency
The primary benefit of working with an independent agency is the objectivity we bring to the table. We aren't restricted to a single corporate menu of products. Instead, we have access to a diverse network of carriers, allowing us to compare various life insurance florida options with complete neutrality. This independence means we work for you, not the insurance company. We provide personalized advocacy during the underwriting process, ensuring your health and lifestyle are represented accurately to secure the best possible terms. Our commitment is to your long-term security, focusing on building a lasting relationship rather than closing a short-term sale.
Diverse Carrier Access: We shop multiple providers to find the specific structure that fits your legacy goals.
Personalized Advocacy: Our team handles the complexities of underwriting and claims so you don't have to.
Strategic Stability: We prioritize solutions that offer permanence and reliability over the decades.
Taking the Next Step Toward Absolute Security
Experience the peace of mind that comes from a meticulously engineered plan. Requesting a personalized consultation is the first step toward securing your family's future. During your initial strategy session, we'll conduct a deep dive into your current liabilities and future aspirations. To maximize our time together, we recommend gathering details about your current mortgage, outstanding debts, and long-term education goals for your children. You can contact Si Insurance Agency today to schedule your session and begin the process of building a legacy that remains secure for generations to come.
Engineering a Lasting Legacy for Your Loved Ones
Securing your family's financial future in the Sunshine State is a deliberate act of foresight that requires more than just a generic policy. It's about engineering a safety net that accounts for rising property values and the unique economic landscape of Broward County. We've examined how to navigate the choice between term and permanent structures and the importance of precise calculations to avoid both under-insurance and unnecessary premium costs. By approaching your coverage with this level of methodology, you transform a complex obligation into a cornerstone of permanent stability.
Finding the right life insurance florida plan doesn't have to be a solitary journey. At Si Insurance Agency, our independent status allows us to provide carrier-neutral advice from our offices in Sunrise and Pompano Beach. We combine deep expertise in Term, Whole, and Universal Life structures with a human-centric service model that acts as a protective guardian for your legacy. It’s our mission to ensure your strategy is as robust as the life you've worked so hard to build. Secure your family’s future with a personalized life insurance strategy from Si Insurance Agency. You've laid the foundation; now let's ensure it stands for generations to come.
Common Questions Regarding Life Insurance in Florida
Is life insurance taxable in Florida?
Life insurance death benefits are generally received by beneficiaries tax-free at both the federal and state levels. Since Florida doesn't impose a state income tax, your loved ones won't face local taxation on the payout. However, if the benefit is held by the insurer and accrues interest before distribution, that specific interest portion may be subject to federal income tax. This is a key reason why life insurance florida remains a preferred vehicle for wealth transfer.
Can I have multiple life insurance policies in Florida?
You can absolutely maintain multiple life insurance policies to cover different financial objectives. This strategy, often called laddering, allows you to align specific policies with varied timelines, such as a 20-year term for a mortgage and a whole life policy for permanent estate costs. Insurers will evaluate your total coverage across all providers during the underwriting process to ensure the combined benefit aligns with your documented financial needs and income levels.
How does the Florida Life Insurance Policy Locator work?
The Florida Department of Financial Services offers a free online tool designed to help residents find lost or unknown life insurance policies of deceased family members. Once you submit a request with the necessary documentation, the state coordinates with insurance companies to search their records for matching policies. This service provides a vital safety net for families who believe a loved one may have secured coverage but cannot locate the physical policy documents.
What happens if I outlive my term life insurance policy?
If you outlive your term, the coverage simply expires and the death benefit is no longer active. However, many modern policies include a conversion rider that allows you to transition into a permanent structure without a new medical exam. You might also have the option to renew on an annual basis, though premiums typically increase significantly at that stage. Reviewing your life insurance florida strategy before the term ends ensures you aren't left without protection.
Can I change my life insurance beneficiary at any time?
You generally have the right to update your beneficiary designations whenever your personal circumstances change, provided the original designation wasn't irrevocable. Life events such as marriage, divorce, or the birth of a child often necessitate these adjustments. To make a change, you simply submit a beneficiary change form to your insurance provider. Keeping these records current is essential for ensuring your death benefit is distributed according to your most recent wishes and legacy goals.
Do I need life insurance if I am single with no dependents?
Even without dependents, life insurance serves several strategic purposes. It can be used to cover outstanding debts, such as private student loans or a mortgage, ensuring these liabilities don't burden your parents or estate. Additionally, securing a policy while you're young and healthy allows you to lock in lower premiums for the future. It also provides immediate liquidity for final expenses, preventing your extended family from facing unexpected financial strain during a difficult time.
How often should I review my life insurance coverage?
We recommend conducting a formal review of your coverage at least once a year or whenever you experience a significant life milestone. Events like purchasing a home in Broward County, starting a new business venture, or a change in your marital status can drastically alter your coverage requirements. Regular assessments ensure that your policy continues to match your current lifestyle and that you haven't become under-insured as your assets and responsibilities grow over time.
Is employer-provided life insurance sufficient for my family?
While group life insurance offered through an employer is a valuable benefit, it's rarely sufficient for comprehensive family security. These policies typically offer a payout equal to only one or two times your annual salary, which often falls short of long-term income replacement needs. Furthermore, these policies are usually not portable, meaning you lose coverage if you change jobs. Maintaining an individual life insurance florida policy ensures your protection remains constant regardless of your employment status.
Comments