


Broward County Commercial Auto Insurance: 2026 Risk Guide
Updated: Sep 20
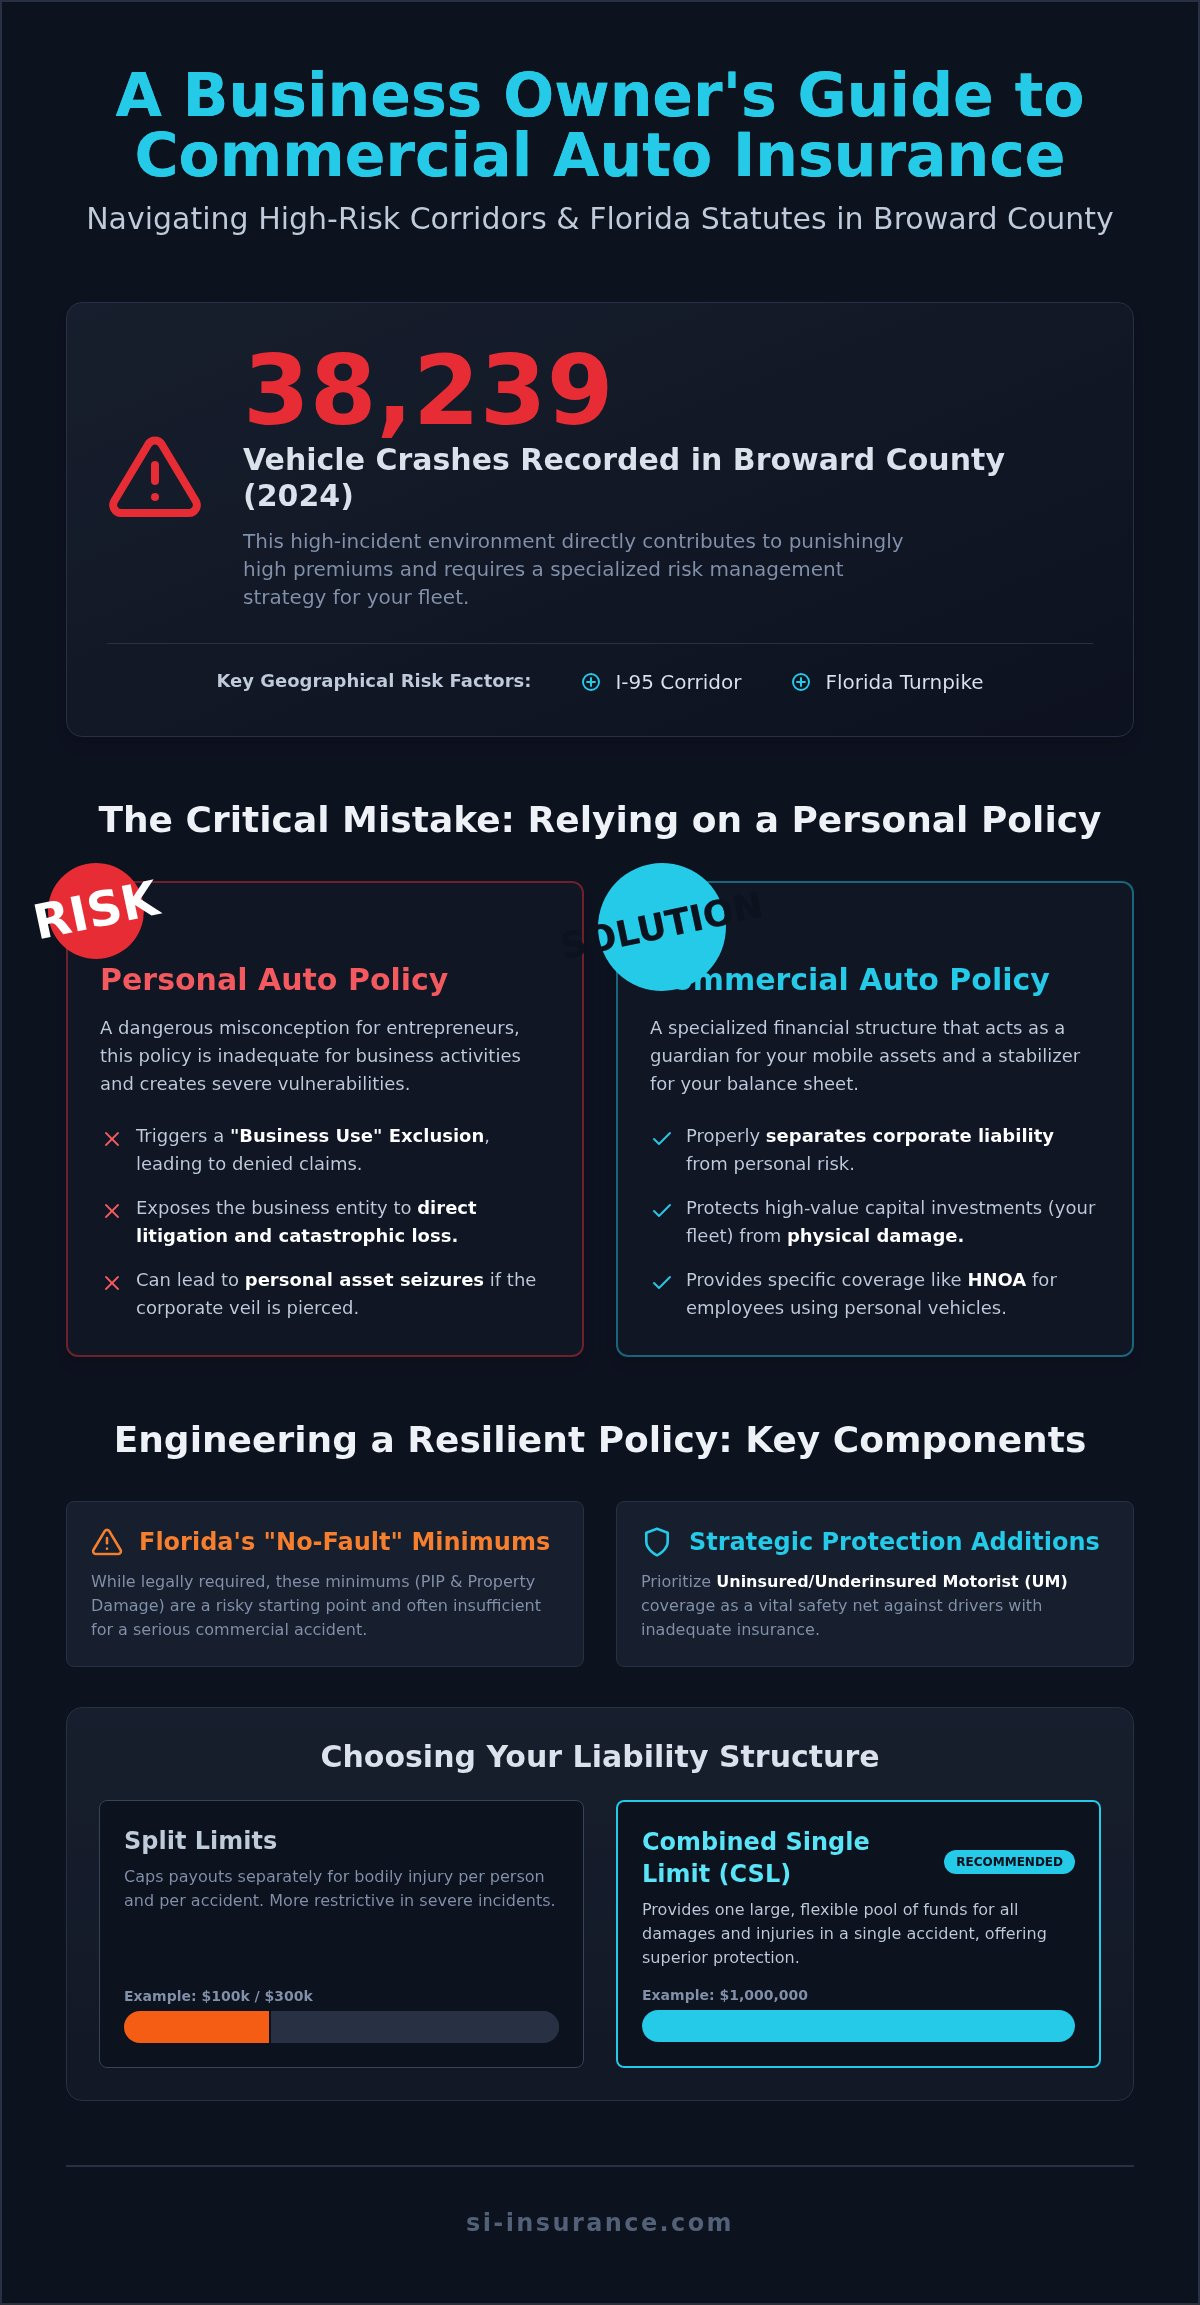
In 2024, Broward County recorded 38,239 vehicle crashes, a sobering statistic that reflects the high-stakes environment where your company fleet operates every day. If you're managing a business in South Florida, you already know that these accident rates often translate into punishingly high premiums for commercial auto insurance Broward County policies. It's frustrating to deal with national call centers that offer vague terms and don't understand the specific traffic patterns of the Pompano Beach or Sunrise corridors. You need more than a generic policy; you require a calculated risk management strategy.
This 2026 risk guide is designed to help you secure coverage that's both comprehensive and precisely aligned with your organizational goals. We'll show you how to navigate the complexities of Florida's latest insurance statutes, including the specific implications of Ordinance 2026-14 and Senate Bill 584. By the end of this analysis, you'll have a clear methodology for engineering a protection plan that ensures absolute security for your assets while maintaining a balanced, cost-effective structure for your business. We'll move through these technical mitigation strategies together to ensure your fleet remains a strength rather than a liability.
Table of Contents
The Strategic Importance of Commercial Auto Insurance in Broward County
Many entrepreneurs in Pompano Beach and Sunrise operate under the assumption that their personal policy extends to their business activities. It's a dangerous misconception that often leads to total financial exposure. In Florida, the line between personal liability and corporate risk is exceptionally thin, yet the financial consequences of crossing it are immense. Commercial auto insurance is a specialized financial structure for business-owned vehicles. When an accident occurs during a business errand, a standard personal policy often triggers a "business use" exclusion. This leaves the business entity exposed to direct litigation, which can be catastrophic in a high-accident area. According to a U.S. Vehicle Insurance Overview, the distinction between personal and commercial risk is fundamental to how liability is assigned and managed across the country.
Distinguishing Business Use from Personal Transit
Employees using their own cars for work tasks create a significant "grey area" that often goes unaddressed until a crisis occurs. Whether it's a quick trip to the bank or transporting a client, these moments represent unmitigated risk for the business owner. Hired and Non-Owned Auto (HNOA) coverage is the specific mechanism designed to fill these gaps, providing protection when your company is held vicariously liable for an accident involving a vehicle it doesn't own. Misclassifying vehicle use in Florida isn't just a minor paperwork error. It's a legal vulnerability that can lead to denied claims and the potential for personal asset seizures if the corporate veil is pierced during litigation. Securing commercial auto insurance Broward County ensures that these operational nuances are covered before they become liabilities.
Asset Protection for the Modern Broward Enterprise
Your fleet is more than just transportation. It's a high-value capital investment that requires a protective guardian to ensure its longevity. For a modern Broward enterprise, comprehensive coverage acts as a stabilizer for the balance sheet, preventing a single collision from derailing your annual financial goals. There’s a profound sense of psychological security that comes from knowing your mobile assets are professionally guarded by a policy that's been engineered for your specific needs. By securing a robust commercial auto insurance Broward County policy, you're not just buying a document; you're implementing a sophisticated risk mitigation strategy that protects your company's future. This proactive approach allows you to focus on growth while SI Insurance focuses on the complex variables of South Florida's traffic environment.
Engineering Your Policy: Essential Coverage Components
Designing a robust risk strategy requires more than just checking boxes on a standard form. It's about engineering a financial structure that can absorb significant shocks without destabilizing your operations. Liability protection serves as the cornerstone of this architecture. It acts as the primary wall between your business assets and the high costs of legal defense or settlements following an accident. While many focus on the premium, the true value of commercial auto insurance Broward County lies in how well these components are calibrated to your specific risk profile.
Florida law is quite specific about these requirements, though the minimums are often just a starting point for a healthy business. For instance, Florida Statute 627.7415 outlines liability limits based on vehicle weight, requiring higher thresholds for heavier commercial vehicles. Beyond the state-mandated Personal Injury Protection (PIP) and Property Damage Liability, sophisticated decision-makers also prioritize Uninsured/Underinsured Motorist (UM) coverage. In our local landscape, where many drivers carry only the bare minimum, UM coverage acts as a vital safety net that protects your own drivers and vehicles when others can't pay for the damage they cause.
Liability Limits: Beyond the Minimum
Most standard policies utilize split limits, which cap payouts for bodily injury per person and per accident. However, many high-level decision-makers opt for a Combined Single Limit (CSL). This structure provides one large pool of funds for any combination of property damage and bodily injury, offering much greater flexibility during a complex claim. If your liability needs exceed standard thresholds, it's often wise to discuss how your auto policy interacts with a broader umbrella structure to ensure total asset security.
Specialized Endorsements for Unique Business Needs
A generic policy often leaves out the most valuable parts of your operation. If your vehicles carry expensive tools or specialized machinery, Inland Marine coverage is necessary to protect that equipment while it's in transit. For delivery-based businesses, loading and unloading liability covers accidents that happen while moving goods between the vehicle and the destination. These aren't just "add-ons"; they're essential stabilizers for your specific workflow. If you aren't sure which endorsements fit your trade, speaking with a local agent can help you identify those invisible gaps before they lead to a denied claim.
Physical damage coverage rounds out the policy by protecting the physical integrity of your fleet. Whether it's collision coverage for accidents or comprehensive coverage for non-crash events like theft or flooding, this ensures your mobile assets can be repaired or replaced quickly. By meticulously balancing these components, you move beyond simple insurance and into a state of absolute security for your company assets.
The Broward Corridor: Geographical Risk Factors
Operating a fleet along the I-95 and Florida Turnpike corridors requires a level of tactical awareness that most national insurers simply don't grasp. These arteries are among the most densely packed transit routes in the nation, where high-speed logistics meet unpredictable commuter behavior. In 2024, Broward County experienced 38,239 vehicle crashes, illustrating a direct and quantifiable correlation between regional traffic density and the elevated liability risks inherent to commercial auto insurance Broward County policies. Broward’s traffic density, which features a high concentration of commercial vehicles interacting with approximately 1.9 million residents, creates an environment where accident frequency directly necessitates specialized risk coverage.
South Florida's seasonal population surges introduce another layer of complexity to your risk profile. During peak months, the influx of temporary residents and tourists unfamiliar with local road layouts significantly increases accident frequency. Beyond the asphalt, your parked assets face environmental threats that are uniquely Floridian. Flash flooding and high-wind events can cause substantial damage to a fleet overnight, making comprehensive coverage a non-negotiable component of your financial planning. We look at these variables as part of a larger, integrated security strategy for your company.
The Pompano Beach and Sunrise Business Hubs
The industrial and commercial corridors in Pompano Beach and Sunrise present specific hazards that general risk models often overlook. These zones are characterized by heavy industrial traffic, frequent stop-and-go delivery cycles, and tight loading bays that increase the likelihood of minor but costly collisions. We don't rely on generic state averages. Instead, SI Insurance integrates hyper-local data into our risk assessments to ensure your premiums reflect your actual operational reality. Understanding these route-specific hazards allows us to engineer more precise protection for your service vehicles, ensuring that your coverage isn't just broad, but accurate.
Mitigating the "Florida Factor" in Claims
One of the most challenging variables in South Florida is the high rate of uninsured or underinsured motorists. When an accident occurs, the legal framework outlined in the Florida Statutes on Commercial Auto Insurance dictates how claims are processed, but it won't replace a missing liability limit from the other party. We help you mitigate this "Florida Factor" by prioritizing strategic positioning for rapid claim response and advising on proactive driver safety programs. These programs aren't just about compliance. They're a vital defensive measure in a high-risk geography, helping to preserve your loss history and keep your long-term costs stable.
Deciphering Florida Statutes: Requirements vs. Strategic Protection
In Florida, the phrase "fully insured" is often a dangerous misinterpretation of the law. For many, it simply means they've met the state's bare minimum requirements of $10,000 in Personal Injury Protection (PIP) and $10,000 in Property Damage Liability (PDL). While this keeps you legal on the road, it's a fragile shield for a growing enterprise. In a county where medical costs and litigation are rising, a $10,000 limit can be exhausted before a vehicle is even towed from the scene. True commercial auto insurance Broward County protection requires a methodology that looks beyond these statutory baselines to calculate your actual exposure.
Florida's "No-Fault" system is designed to provide quick medical payments regardless of who caused the accident, but it doesn't provide a release from significant liability. When a commercial entity is involved, the stakes are higher. If your vehicle causes substantial damage or injury, the other party can, and likely will, pursue your business for damages that exceed those small PIP limits. Specialized firms like the Law Offices of David Davidi, APLC represent victims in such complex litigation, highlighting why businesses must maintain robust liability limits. At SI Insurance, we view legal minimums as a starting point, not a destination. Our approach involves a rigorous analysis of your fleet's daily operations to ensure your coverage is an accurate reflection of your risk.
Florida's requirements scale with the size and weight of your vehicles. For example, commercial vehicles with a gross vehicle weight rating (GVWR) of 26,000 pounds or more are subject to much higher liability limits. A vehicle weighing between 26,000 and 34,999 pounds must carry at least $50,000 in combined single limit coverage. Registration and insurance verification in Broward are rigorous; failing to maintain these standards leads to immediate fines and license suspensions. However, the real consequence of non-compliance isn't the fine. It's the total legal exposure your business faces when a claim exceeds your policy limits.
Strategic Recommendations for High-Value Operations
We recommend limits that significantly exceed the state's basic requirements because the goal isn't just compliance; it's asset preservation. If a corporate vehicle is involved in a major accident, plaintiff attorneys may attempt to look past the business entity to reach the personal assets of the owners. High-limit coverage acts as a definitive barrier in these scenarios. This is a core component of a broader strategy, which we detail in our Business Insurance in Broward County: A Strategic Guide. By engineering your policy with this level of foresight, you ensure that a single road incident doesn't threaten your life's work. If you're ready to move past basic compliance, you can secure a consultation with our team to review your current liability structure.
The Si Insurance Approach: A Protective Partnership
Choosing an insurance provider in South Florida often feels like a purely transactional exchange, but for a business with high-value assets, that approach is insufficient. At Si Insurance Agency, we've moved beyond the commoditized model of selling policies to offer a consultative risk partnership. In a volatile market where carriers frequently shift their appetite for risk, the value of an independent agency cannot be overstated. We don't represent a single national call center. Instead, we act as your protective guardian, utilizing our access to multiple carriers to engineer a commercial auto insurance Broward County strategy that's as resilient as it is cost-effective.
Our commitment to the Broward County community is rooted in a blend of traditional reliability and modern risk engineering. We understand that your fleet's security is the foundation of your operational stability. By applying rigorous analysis to your specific data, we create a shield that accounts for the unique pressures of the South Florida landscape. It's a method that prioritizes long-term security over short-term fixes, ensuring your business remains protected through every market cycle. We're not just providing a policy; we're delivering intellectual confidence.
Tailored Solutions for Sunrise and Pompano Beach
We respect that your time is a finite and valuable resource. Our agents provide personalized service that cuts through the noise, offering direct access to professionals who understand the nuances of your specific industry. Whether you're managing a logistics firm in Pompano Beach or a service fleet in Sunrise, the Si Insurance promise remains the same. We deliver composed, reassuring, and meticulous protection that allows you to focus on growth while we manage the complexities of your risk. It's a localized perspective that national insurers simply can't replicate.
Next Steps: Securing Your Fleet
The process of a professional insurance analysis with Si Insurance Agency is designed to be thorough yet efficient. When you prepare for your consultation, it's helpful to have your current policy declarations, driver schedules, and vehicle maintenance logs ready for review. This information allows us to perform a precise audit of your existing coverage gaps. You don't have to navigate these complexities alone. We invite you to Consult with a Si Insurance expert today to begin the process of fortifying your company's mobile assets. Our team is ready to provide the absolute security your business deserves.
Fortifying Your Fleet for the Road Ahead
We've explored how a sophisticated approach to risk management goes far beyond simply meeting Florida's bare legal minimums. By engineering a policy that accounts for the high-density traffic of the I-95 corridor and the specific industrial hazards found in Sunrise and Pompano Beach, you transform insurance from a mandatory expense into a strategic stabilizer for your business assets. Securing a tailored commercial auto insurance Broward County policy ensures your fleet remains protected against the unique volatility of the South Florida market.
As an independent agency, Si Insurance Agency provides you with direct access to top Florida carriers and the deep local expertise required to protect your company's future. Our human-centric, professional service is meticulously designed for entrepreneurs who demand more than a national call center can offer. You've worked hard to build your business, and we're here to ensure your mobile assets are guarded with the highest level of care. Secure Your Business Fleet with a Strategic Quote from Si Insurance Agency. We look forward to helping you navigate the complexities of the road with absolute confidence.
Frequently Asked Questions
Is commercial auto insurance required for my small business in Broward County?
Yes, Florida law requires all commercial vehicles to carry minimum liability coverage. For most, this means at least $10,000 in Personal Injury Protection and $10,000 in Property Damage Liability. However, if your vehicles exceed 26,000 pounds, your requirements increase significantly under state statutes. Meeting the bare legal minimum is rarely enough to protect a business from a major lawsuit in South Florida's litigious environment. We always suggest evaluating your specific risk profile before settling on a policy.
How much does commercial auto insurance cost for a Broward County business?
Premiums for commercial auto insurance Broward County are determined by several variables, including your fleet size, vehicle types, and driver safety records. Because Broward experienced over 38,000 crashes in 2024, local rates reflect that higher risk. While some carriers are filing for rate decreases in 2026, your specific cost depends on your loss history and chosen limits. We recommend a professional audit to find the most competitive rates from multiple Florida carriers.
Can I use my personal car for business purposes without a commercial policy?
Using a personal vehicle for business tasks is a common but dangerous mistake. Personal insurance policies typically contain specific exclusions for business use, meaning a claim could be denied if an accident happens during a work errand. This leaves your personal assets exposed to corporate liabilities. If you or your employees use personal cars for business, you need a commercial policy or a specific endorsement to bridge that protective gap.
What is Hired and Non-Owned Auto (HNOA) insurance, and do I need it?
HNOA insurance provides liability protection for vehicles your business uses but doesn't own, such as employee vehicles or short-term rentals. If an employee causes an accident while picking up supplies or visiting a client, your business could be held vicariously liable. HNOA fills this critical gap, ensuring your company isn't left vulnerable to lawsuits stemming from accidents in non-fleet vehicles. It's an essential stabilizer for any modern Broward enterprise.
How do Florida’s no-fault laws affect my commercial auto policy?
Florida’s no-fault system requires Personal Injury Protection (PIP) to cover medical expenses regardless of who caused the accident. This allows individuals to access necessary treatment from specialists like Chiropractic Natural Care Center for injuries sustained during a collision. While this speeds up initial payments, it doesn't shield your business from being sued for significant damages. If an accident involving your commercial vehicle causes serious injury or property damage exceeding $10,000, the other party can pursue your business for the difference. Commercial policies are engineered to handle these high-stakes liability claims beyond the PIP threshold.
Several regional factors drive rates in South Florida, primarily the extreme traffic density on the I-95 and Florida Turnpike corridors. Seasonal population surges and a high percentage of uninsured motorists also contribute to the local risk environment. Additionally, the rising cost of vehicle technology and medical care means claim severity is increasing. These factors make it vital to work with an independent agent who can navigate the volatile Florida insurance market on your behalf.
How often should I review my commercial auto coverage with my agent?
You should review your commercial auto insurance Broward County policy at least once a year. However, it's wise to contact your agent immediately if you hire new drivers, purchase new equipment, or change your service routes. Regular reviews ensure your limits remain adequate as your business grows. Since the Florida insurance market is showing signs of stabilization in 2026, an annual checkup might also reveal new opportunities for more competitive pricing or better terms.
Does commercial auto insurance cover the tools and equipment inside my van?
A standard commercial auto policy generally protects the physical vehicle but excludes the cargo, tools, or specialized equipment inside. To protect these high-value assets, you typically need an Inland Marine endorsement. This coverage ensures your tools are protected against theft or damage while they're in transit or at a job site. For service-based businesses in Pompano Beach or Sunrise, adding this protection is a necessary step in securing your company’s total capital investment.
A risk guide like this is a good reminder that insurers look closely at driver records, whether they are covering a commercial fleet or a single family car. Every driving record starts with how well a person was trained, and in New York the first step is the 5 hour pre-licensing course, which https://5hour-class.nyc/ offers online for $40 with an emailed MV-278 certificate. The course covers traffic laws, the point system and insurance responsibilities, so new drivers understand early how their habits behind the wheel will affect what they pay for coverage.