


Dropped by Your Auto Insurer in Hialeah? Understand Your Options
If you’ve received a notice from your auto insurer in Hialeah, start by checking whether your policy is still active and when its status may change. The options after being dropped by auto insurer in Hialeah depend in part on what the notice says. Don’t assume your coverage has already ended or that you have unlimited time to find another insurer.
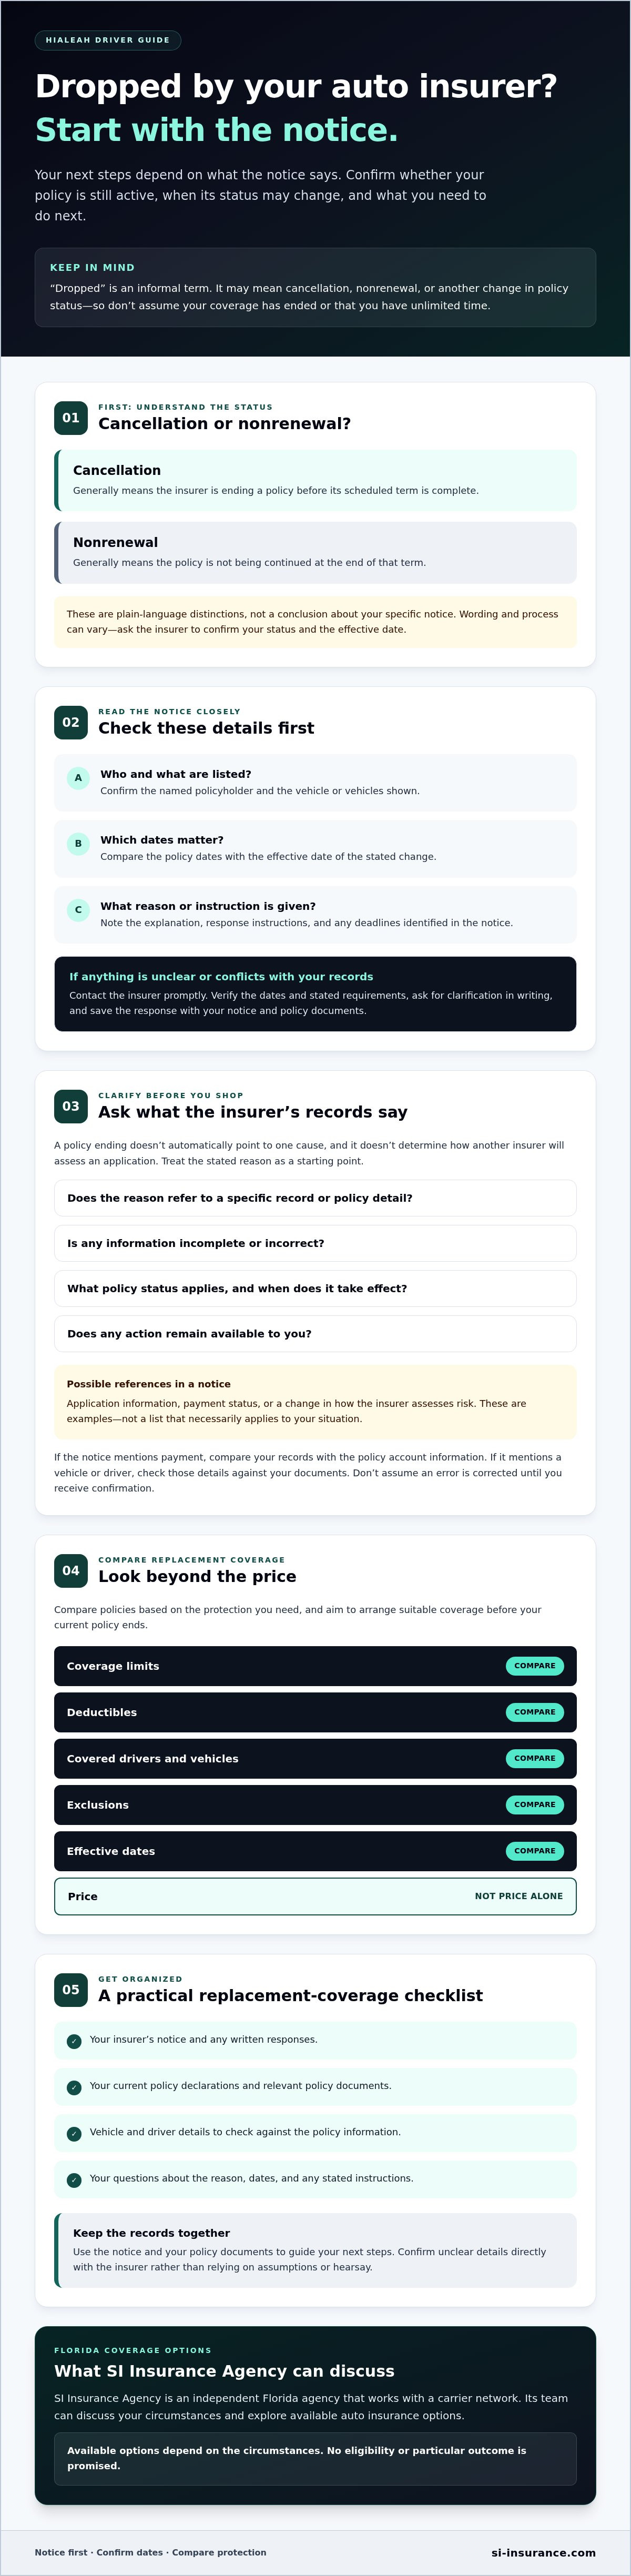
Cancellation and nonrenewal can involve different timelines. Check the notice for the reason, effective date, and any steps or deadlines it identifies. Then compare replacement policies based on the protection you need, not price alone, and aim to arrange suitable coverage before your current policy ends.
This article explains how to read your notice, check key dates, and compare possible coverage. SI Insurance Agency is an independent Florida agency that works with a carrier network. Its team can discuss your circumstances and explore available options, without promising eligibility or a particular outcome.
Table of Contents
Dropped by an Auto Insurer in Hialeah? First, Check What Your Notice Actually Says
A notice that your insurer is ending or changing your auto policy can leave you unsure whether you’re still covered and what to do next. Start with the document: identify the policy status, the date shown, the reason given, and any action the insurer says you can take. If anything is unclear, confirm it directly with the insurer before making decisions.
“Dropped” is an informal term. It may refer to a cancellation, a nonrenewal, or another change in policy status. The options after being dropped by auto insurer in Hialeah depend on your notice and policy documents, so keep those records and any written communications together as you plan your next steps.
For another perspective on comparing insurance choices, you can watch this video:
How can you tell whether the insurer cancelled or will not renew your policy?
Cancellation generally means the insurer is ending a policy before its scheduled term is complete. Nonrenewal generally means the policy is not being continued at the end of that term. This is a plain language distinction, not a conclusion about your specific notice. Wording and process can vary, so ask the insurer to confirm your policy’s status and the date any change takes effect. Save the notice, policy documents, and written responses together.
Which details in the notice should a Hialeah driver check first?
Read the notice carefully and compare it with your current policy documents. Check:
The named policyholder and the vehicle or vehicles listed.
The policy dates and the effective date of the stated change.
The reason provided and any response instructions or deadlines.
If a detail is unclear or conflicts with your policy records, contact the insurer promptly and ask for clarification in writing. Verify the dates and stated requirements rather than relying on hearsay or assuming the policy has already ended. An insurer’s decision can relate to its assessment of risk. For general background, see how insurers determine risk. Keep your immediate focus on confirming what the notice means and when your policy status changes.
Why Was Your Florida Auto Policy Dropped, and What Can You Clarify?
A policy ending doesn’t automatically point to one cause, and it doesn’t determine how another insurer will assess an application. The reason on your notice is a starting point, not a complete explanation of every underwriting factor or a guarantee that the same issue will affect your next application. Check the notice and policy documents, then ask the insurer to explain any wording you can’t interpret.
What reasons might an insurer give for ending or not renewing coverage?
Depending on the situation, the notice may refer to application information, payment status, or a change in how the insurer assesses risk. These are examples to compare with the actual explanation, not a list of reasons that necessarily applies to you or establishes whether a decision was valid. Insurers assess risk in different ways, and another carrier may review the same driver and vehicle under its own process.
If you believe a detail is inaccurate, gather relevant records and ask the insurer how to correct or clarify it. For example, if the notice refers to a payment issue, compare your payment records with the policy account information. If it refers to a vehicle or driver, check those details against your policy documents. Don’t assume an error has been corrected until you receive confirmation.
What should you ask the insurer before you shop for coverage?
Keep the conversation focused. Ask the insurer to confirm which policy status applies, when it takes effect, the specific reason in its records, and whether any action remains available to you. You can also ask whether its records accurately reflect your payment and vehicle information. Request a written explanation if that will help you keep the details clear, and save the response with the notice.
Does the stated reason refer to a specific record or policy detail?
Is any information incomplete or incorrect, and what documentation may help clarify it?
What is the current policy status while you review the notice?
Keep insurer notices and state correspondence organized separately. If you receive a letter from the FLHSMV, read its instructions and use the agency’s information to understand what response it requests. Don’t assume it is the same as a notice from your insurer.
Once you understand the stated reason, you can explain your circumstances more accurately while comparing the options after being dropped by auto insurer in Hialeah. SI Insurance Agency is an independent Florida agency offering auto insurance through carriers. You can discuss available auto insurance options without assuming that a particular carrier will offer coverage or approve an application.
Options After Being Dropped by Auto Insurer in Hialeah: Compare Coverage
Once you know what your current insurer has decided, compare replacement proposals by their terms, not just their quoted premiums. A lower premium can reflect different limits, deductibles, or policy details, so compare like with like wherever possible. A low premium alone cannot establish whether coverage fits your needs.
What should you compare besides the premium?
Review the coverage limits and deductibles, then confirm which drivers and vehicles are listed. Check exclusions and policy dates as well. Differences in listed household drivers or vehicle information can affect how a proposal fits your circumstances, so ask the carrier or agent to explain anything you don’t understand. Don’t assume a feature is included unless the carrier confirms it in writing.
Consider how you use the vehicle and who may drive it. If a proposal doesn’t appear to reflect your household or driving situation, ask for clarification before choosing. You can use Florida’s statute on insurance notice provisions as a starting point, but don’t treat a general reference as a decision about how a specific policy applies. Confirm questions about your notice with the insurer or an appropriate professional.
How can an independent agency help you explore carrier options?
An independent agency can help present your information to available carriers and discuss proposals that may be accessible for your situation. This can make comparisons more organized, but it doesn’t determine the outcome. Carrier availability, eligibility, underwriting decisions, and offered terms vary. Each carrier conducts its own review, so a previous insurer’s decision doesn’t establish what another carrier will decide.
Answer application questions accurately, including questions about a prior insurer’s decision. If you’re unsure what a question means, ask the carrier or agent before submitting the application rather than guessing or leaving out relevant information. Compare the written proposal with your needs and confirm the effective date before making a change.
A useful comparison of the options after being dropped by auto insurer in Hialeah makes the trade-offs clear: what each proposal covers, what it excludes, what you may pay out of pocket under its deductible, and when coverage would begin. Keep proposals and written clarifications together so you can review them side by side. Don’t base your decision on a headline quote alone.
A Practical Replacement Coverage Checklist for Hialeah Drivers
Prepare before requesting quotes so you can compare proposals and catch mismatched details. Keep your current insurer’s notice and any replacement policy documents together to check dates and terms side by side.
What information should you prepare before requesting quotes?
Gather the information needed to describe your current policy and driving situation accurately. You don’t need to share unnecessary sensitive details just to organize your questions. Start with:
Your notice and current declarations: Keep the insurer’s notice and policy declarations available, including listed vehicles and drivers, coverage details, and policy dates.
Vehicle information: Have the identifying details for each vehicle you want to insure, and check that they match your existing documents.
Driver and household details: Prepare accurate information about the drivers relevant to the application and how the vehicles are used.
Your coverage questions: Note the limits, deductibles, exclusions, listed drivers, and effective dates you want clarified in each proposal.
Answer application questions consistently and accurately. If a question about your previous policy or insurer’s decision is unclear, ask for clarification before submitting the application rather than guessing or omitting information.
How can you reduce the risk of a coverage gap?
Confirm your current policy’s status and end date directly with your insurer. Don’t assume coverage has ended because a notice arrived, or that it remains active because a new proposal is being discussed. Review the replacement policy documents and confirm the proposed effective date with the carrier or agent. A quote or application alone isn’t confirmation that a policy is active.
Before relying on replacement coverage, check that the documents list the intended vehicle and drivers, that you understand the terms, and that the effective date aligns with your current policy status. If anything is unclear, request written clarification. Avoid cancelling or changing a policy based on an unconfirmed date or verbal assumption.
Florida insurance requirements can depend on the circumstances and may change, so verify current requirements with an authoritative state source rather than relying on informal advice. For the options after being dropped by auto insurer in Hialeah, aim for a documented transition: confirmed current policy dates, accurate applications, and written replacement terms you’ve reviewed. SI Insurance Agency is an independent Florida agency offering auto insurance through carriers. You can discuss your auto insurance options and circumstances without assuming a particular carrier will offer coverage or approve an application.
Explore Auto Insurance Options With SI Insurance Agency
After reviewing your notice and gathering your current policy details, an independent agency may help you explore available options. SI Insurance Agency is an independent Florida agency that offers auto insurance through a network of carriers. Its team can discuss your circumstances and help you consider carrier options, while each insurer makes its own decisions about eligibility, terms, and coverage.
Hialeah drivers can discuss their needs with the agency, but SI Insurance Agency does not have a Hialeah office. Its offices are in Sunrise and Pompano Beach, and it serves customers in cities across Florida.
What information can help an agency understand your situation?
Have your insurer’s notice and current policy dates available, along with accurate vehicle details and the coverage you’re looking for. It can also help to note who needs to be listed as a driver and which parts of a proposed policy you want explained. You don’t need every answer before starting a discussion. Clear questions can help identify what needs further review.
Share the prior insurer’s decision accurately if it’s relevant to your inquiry or an application. Complete information can help an agency explore relevant carrier options, but it doesn’t guarantee that a carrier will offer coverage. The insurer determines eligibility and final policy terms.
What should you expect when discussing replacement coverage?
The discussion can help clarify your circumstances and identify proposals to review, if options are available. Ask what each proposal covers, which drivers and vehicles it lists, what exclusions apply, and when coverage would begin. If a detail is unclear, request an explanation before treating the proposal as a suitable replacement. Confirm the effective date and review the written policy documents before relying on the coverage.
The options after being dropped by auto insurer in Hialeah depend on your circumstances and the carriers available to consider them. Share the notice details and your coverage questions, then review any available proposals carefully.
To discuss your situation and explore possible auto insurance options through SI Insurance Agency, discuss your auto insurance options through the agency’s website.
Take the Next Step Toward Suitable Coverage
A notice from your auto insurer can feel like a final decision, but your next move is to clarify the policy status and dates, then compare replacement proposals. Check the stated reason with the insurer, answer application questions accurately, and review limits, deductibles, listed drivers, exclusions, and effective dates before relying on a new policy. These steps can help you assess the options after being dropped by auto insurer in Hialeah without basing your decision on price alone.
SI Insurance Agency, operated by SI Insurance LLC, is an independent Florida agency offering auto insurance through a network of carriers. The agency can discuss your circumstances and help explore available carrier options, though each insurer determines eligibility and final terms. No particular outcome is guaranteed.
Bring your notice, policy dates, vehicle details, and coverage questions to the conversation. To take the next step, discuss your auto insurance options with SI Insurance Agency. Clear information and a careful review can help you move forward with a better understanding of your choices.
Frequently Asked Questions
Can an auto insurer drop you in Florida without notice?
Generally, Florida insurers must provide advance notice before cancelling or not renewing an auto policy, but the required timing depends on the reason and circumstances. The notice timing described here includes 45 days for cancellation or nonrenewal and at least 10 days for cancellation due to nonpayment. Review your actual notice and confirm its effective date with the insurer, since your policy status and applicable requirements depend on the details.
What is the difference between cancellation and nonrenewal of auto insurance?
Cancellation generally means a policy is ended before its scheduled term is complete. Nonrenewal means the insurer won’t continue it at the end of the term. The notice should identify the policy status and relevant date, but wording and circumstances can vary. Ask the insurer to confirm what applies to your policy, and keep its explanation with your policy documents while exploring replacement coverage.
Can I get auto insurance after being dropped by my insurer?
You may be able to find coverage, but another insurer may reach a different decision from your previous carrier. Each carrier reviews applications under its own underwriting process, so eligibility and terms can vary. Answer questions about the previous insurer’s decision accurately. An independent agency can help you explore available carrier options, but it can’t promise acceptance, coverage, or a particular price.
How do I avoid a lapse in auto insurance after a nonrenewal notice?
Confirm your current policy’s status and end date directly with your insurer, then compare replacement proposals early enough to review them carefully. Before relying on a new policy, check its written documents and confirm the effective date with the carrier or agent. Don’t assume a quote or application means coverage is active, and don’t change or cancel a policy based on an unverified date. Verify current Florida requirements through authoritative sources.
Will being dropped by an insurer make my next auto policy more expensive?
Not necessarily. A new carrier reviews your application independently, and the premium it offers depends on its assessment and the information provided. The prior insurer’s decision may be relevant to application questions, but it doesn’t establish what another carrier will charge or whether it will offer coverage. Compare limits, deductibles, listed drivers, exclusions, and effective dates alongside the premium to assess the policy’s overall fit.
What documents should I have when shopping for auto insurance in Hialeah?
Have your insurer’s notice and current policy declarations available, along with vehicle details and accurate information about the drivers who need to be considered. Note the current policy dates, the notice’s stated reason, and questions about proposed limits, deductibles, exclusions, or effective dates. These records can help you give consistent answers and compare written proposals. Share personal information only through an appropriate application or agency process.
Can an independent insurance agency help after my insurer drops me?
Yes. An independent agency can help you present your circumstances to available carriers and explore possible auto insurance options, though each carrier decides eligibility and final terms. SI Insurance Agency is an independent Florida agency operated by SI Insurance LLC and offers auto insurance through a carrier network. It serves customers in Hialeah and other Florida cities, with offices in Sunrise and Pompano Beach.
Comments