


Finding Affordable Home Insurance With a Bad Roof in Pensacola
What if a roof that complicates your insurance search doesn’t have to end it? Finding affordable home insurance with a bad roof in Pensacola can be challenging, especially when you’re unsure whether age, visible wear, or past repairs will affect eligibility, premiums, or coverage. Before requesting quotes, gather the roof details you can verify and note any damage or repairs still outstanding. That gives insurers a clearer picture of the property and helps you compare responses.
A roof concern changes the search, but it doesn’t remove the need to compare carefully. Insurers may evaluate the same roof differently, so look beyond the premium to the coverage, deductibles, exclusions, and roof settlement terms in each offer. Compare quotes on equivalent coverage assumptions, and keep track of any inspection or documentation requests.
This guide explains which roof details may matter, what records can help support an application, and how to compare terms such as actual cash value and replacement cost. SI Insurance is an independent Florida agency that works with carriers to review home insurance options based on each homeowner’s circumstances. The same practical steps apply to homeowners across Florida, including Pensacola: document the roof accurately, then weigh price against the protection described in the policy.
Key Takeaways
“Bad roof” isn’t a universal insurance classification. Age, visible damage, maintenance history, and inspection findings may each shape how a roof is evaluated.
For finding affordable home insurance with a bad roof in Pensacola, compare policy terms as carefully as premiums because carrier requirements and coverage options can differ.
Compare quotes using the same coverage limits and deductibles, then review roof settlement terms, exclusions, and documentation requirements.
Gather available roof records, repair invoices, inspection reports, and clear photographs so you can describe the property accurately when requesting quotes.
Si Insurance Agency works with carriers to compare Florida home insurance options in light of your individual circumstances.
Table of Contents
What a Bad Roof Can Mean for Home Insurance in Pensacola
“Bad roof” is a homeowner’s description, not a universal insurance classification. One person may use it for an aging roof that still appears intact; another may mean missing shingles, an active leak, or visible deterioration. For finding affordable home insurance with a bad roof in Pensacola, the distinction matters because insurers may consider roof age, material, condition, maintenance history, and inspection findings in different ways.
A roof concern can affect the questions an insurer asks, whether an inspection is requested, and the terms or options presented. It does not determine the home’s overall insurability by itself. Insurers may also assess other property characteristics and the coverage requested. The structure and purpose of home insurance provide useful context, but the details of a particular policy depend on its wording.
This video offers additional context on roof condition and insurance pricing:
Which roof details may affect an insurance application?
Roof age and material describe what’s on the home, while visible condition can point to damage or deterioration that may need closer review. Repair history adds important context. A dated invoice or inspection report can show that a specific issue was addressed, while an active leak or unrepaired damage describes a different current condition. When you share roof information, separate completed work from repairs that are still needed or only recommended.
Carrier eligibility criteria and documentation requests vary, so don’t treat one roof-age or condition threshold as universal. An insurer may ask for details or an inspection, but its requirements and decision depend on the carrier and the property. If you don’t know a roof’s installation date, say so rather than guessing.
Why Pensacola homeowners should consider local exposure
Pensacola’s Gulf Coast setting makes weather exposure a relevant part of a property’s context, but a citywide assumption can’t describe an individual roof. Construction, roof material, maintenance, visible condition, and documented repairs help provide a more precise picture. Two homes in the same area may therefore receive different underwriting consideration. Homeowners elsewhere in Florida can use the same approach: describe the specific home and roof, rather than relying on a general impression of local conditions.
In brief: Roof condition is one part of an insurance review, not a universal verdict on whether the entire home can be insured. Clear, specific information helps insurers evaluate the property rather than a vague label.
How Roof Condition Can Shape Florida Home Insurance Options
Roof information can influence how an insurer evaluates an application, but the effect depends on the carrier and the property. It may affect eligibility, prompt an inspection request, change available policy terms, or narrow the options presented. These decisions are separate from other underwriting considerations, including the home’s construction and the amount and type of coverage requested.
What insurers may ask about an aging or damaged roof
An application may ask for the roof’s age, material, current condition, repair history, or inspection records. Some insurers may request additional documentation or an inspection; others may use a different review process. There is no single age threshold or repair rule that applies to every carrier, so treat stated criteria as specific to that insurer and policy.
Accurate details help distinguish a reported issue from its current status. For example, a past leak with documented repairs is different from an active leak, while general wear may be assessed differently from visible damage. Share what you know, and don’t assume that a completed repair automatically determines eligibility or coverage.
How to read roof-related terms in a quote
A premium alone won’t show how much protection a policy provides for roof damage. Review the proposed limits and deductibles, along with exclusions and the wording that explains how a roof loss would be settled. Check which causes of loss are covered and whether a roof-related limitation affects that coverage.
Replacement-cost language generally refers to settlement based on repair or replacement cost, subject to the policy’s terms. Actual-cash-value language generally accounts for depreciation, but how either basis applies to a particular roof or loss depends on the contract. Read the policy documents, not just the quote summary, and note any endorsements or special conditions that affect roof coverage.
The policy wording, not the quote headline, defines what coverage applies. This is central to finding affordable home insurance with a bad roof in Pensacola: compare the protection alongside the price, using equivalent limits and deductibles wherever possible.
Homeowners considering improvements can visit the official My Safe Florida Home grant program site for information about the program and its current terms. Program eligibility and insurer decisions are separate matters. Don’t assume that an upgrade or grant changes a specific carrier’s requirements or premium.
A side-by-side review can make differences between offers easier to spot. Si Insurance Agency works with carriers to compare Florida home insurance options based on individual circumstances. Learn more about Florida home insurance options as you consider policy terms for your home.
How to Compare Affordable Home Insurance Quotes With a Bad Roof
A lower premium can look attractive, but it doesn’t tell you whether two quotes provide comparable protection. For a useful comparison, keep dwelling coverage limits and deductibles consistent, then examine how each policy addresses the roof. Exclusions, settlement terms, and conditions attached to coverage can change the value of an offer.
Which quote details should Pensacola homeowners compare?
Use a side-by-side review rather than relying on the premium alone. Record what each quote says about these details, and note anything that is missing or still subject to an inspection or documentation request.
Confirm that each quote reflects the same dwelling coverage and requested protections. If one offer assumes an inspection or additional proof of repairs while another does not, that difference may affect the review or terms. Treat the quotes as comparable only after you understand those assumptions.
How to weigh affordability against protection
Affordability involves more than the amount due for the policy. A lower premium paired with a higher deductible or narrower roof coverage may leave you with greater out-of-pocket costs after a loss. A higher-priced option may have terms that better fit your circumstances. You can’t judge either outcome without considering the home and the policy wording.
Bundling home insurance with other coverage may be worth including in a broader comparison, but it doesn’t guarantee savings or suitable roof terms. Evaluate each policy on its own merits, including limits, deductibles, exclusions, and conditions. The lowest premium isn’t automatically the best-value policy.
For finding affordable home insurance with a bad roof in Pensacola, think of affordability as a balance between premium and the protection you can rely on. Si Insurance Agency works with carriers to compare options in light of individual circumstances. Review home insurance options with both price and policy terms in view.
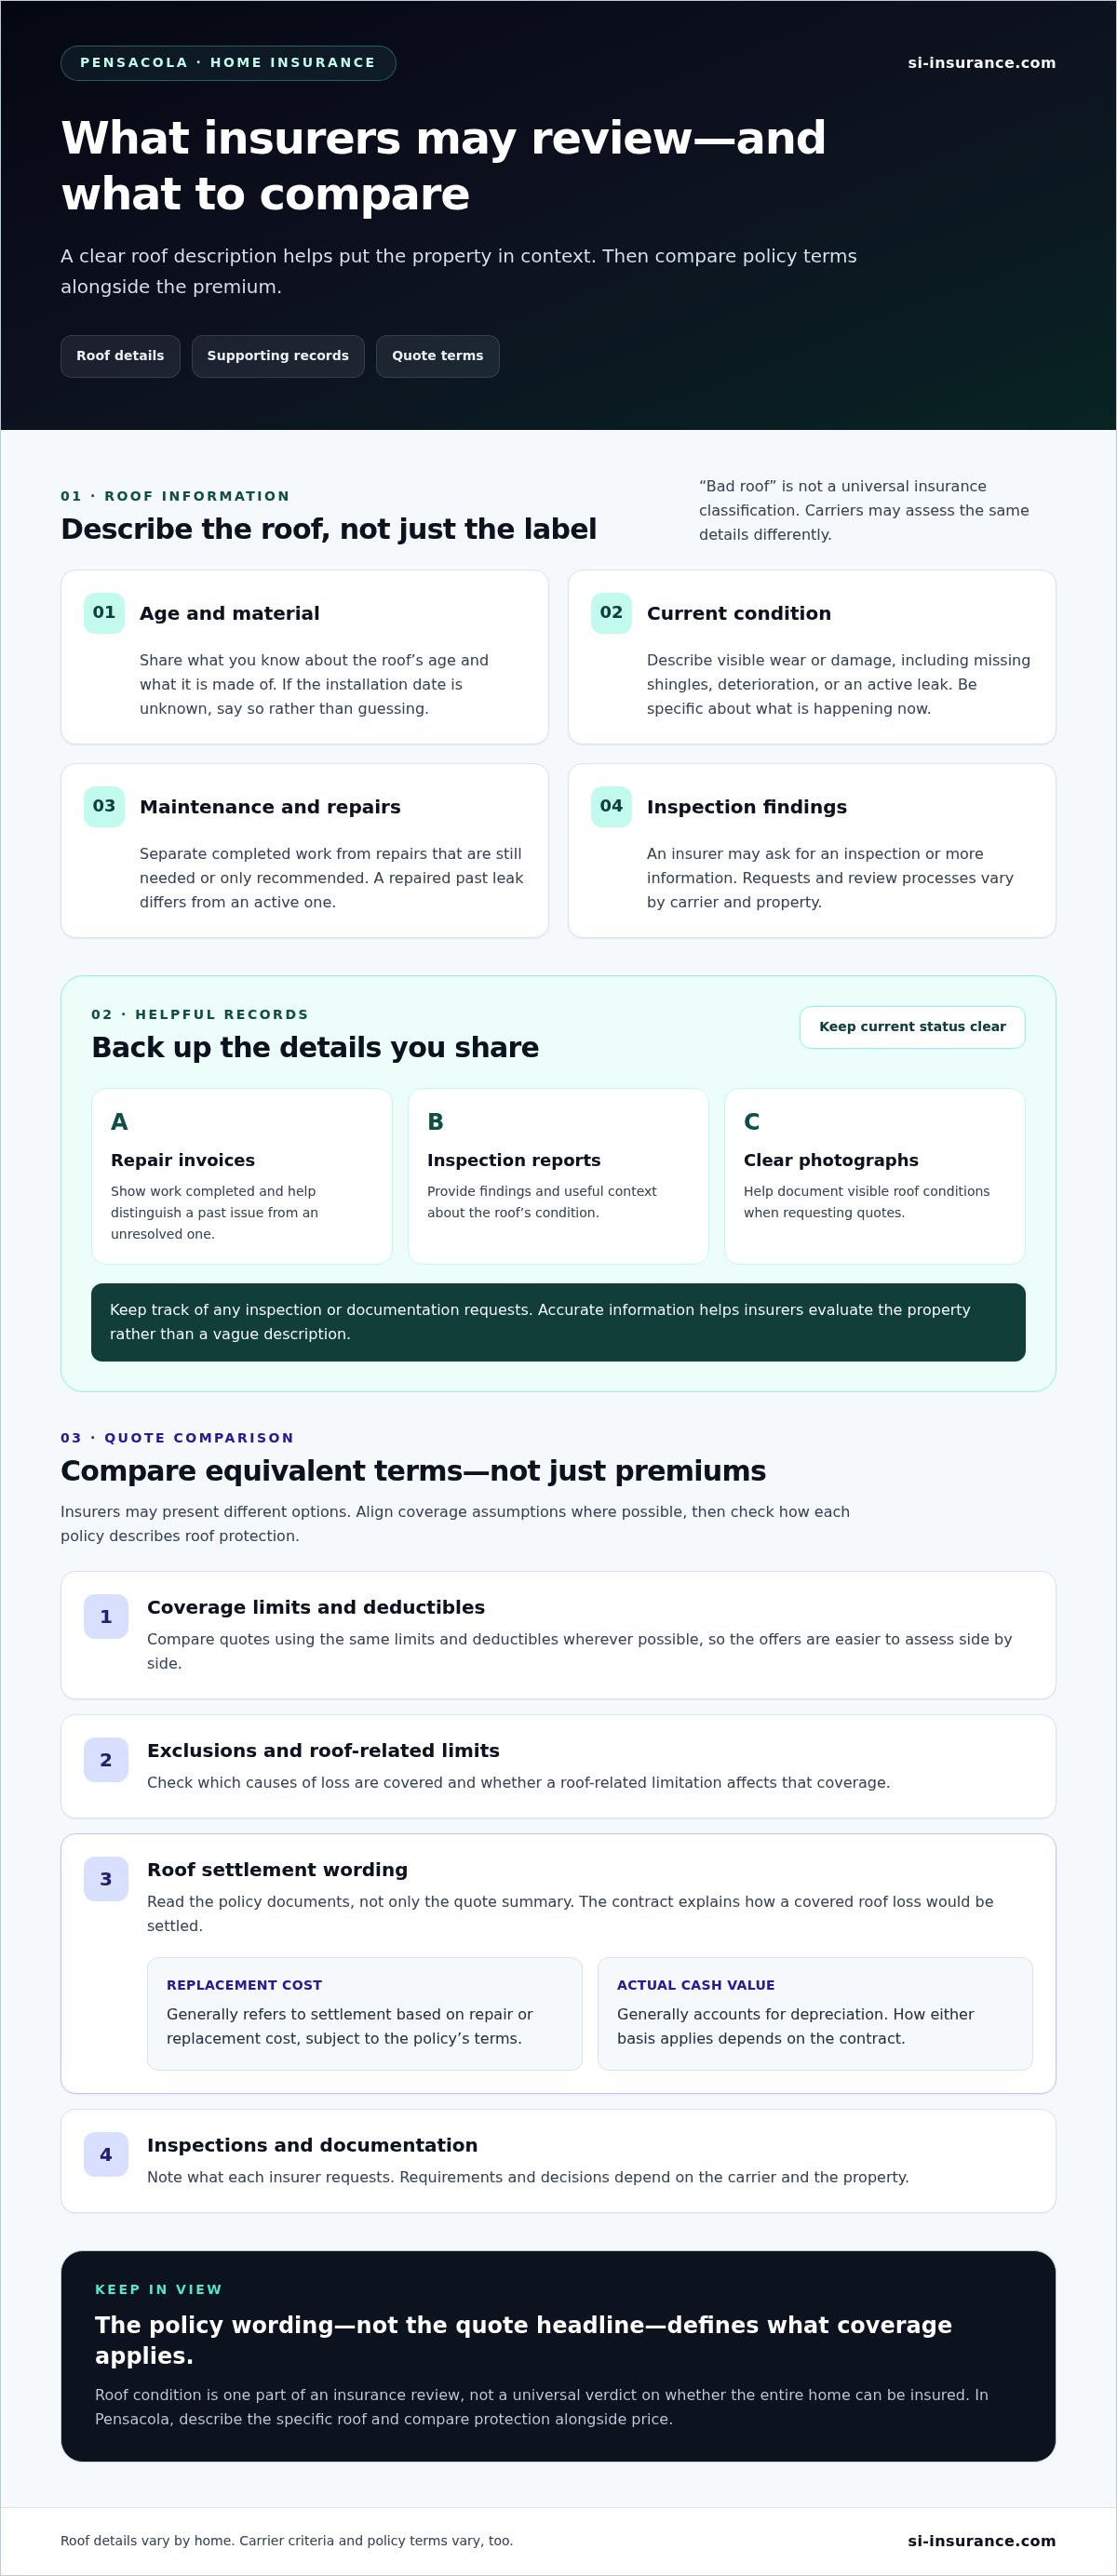
Prepare Your Roof Information Before Requesting Pensacola Quotes
A clear, well-organized account of your roof makes insurance comparisons more straightforward. You don’t need to guess at missing details or describe the roof in overly broad terms. Gather what you can substantiate, describe its current condition accurately, and use the same information and coverage assumptions for each quote request. This preparation supports a more useful comparison, though each carrier may have its own review process.
Gather accurate roof and property records
Start with records that establish what is known about the roof and any work completed. Useful materials, when available, include:
Roof installation or replacement records, with dates only when documented.
Repair invoices and maintenance notes that describe completed work.
Existing roof inspection reports and other relevant property records.
Clear photographs showing the roof’s current visible condition.
Keep completed repairs separate from work that has only been recommended or planned. If you can’t verify an installation date, say so rather than estimating. Don’t conceal known damage or describe a repair as complete when it isn’t. Accurate information gives the application a sound basis for review and can help avoid confusion if an inspection or follow-up questions arise.
Request and review quotes consistently
Provide the same roof details and coverage assumptions for each comparison. Keep the requested dwelling limits and deductibles consistent where possible, and note any differences in what a quote assumes about the roof. If a carrier requests an inspection, repair documentation, or additional information, record the request and any stated policy conditions so you can account for them as you compare offers.
Then compare the proposed terms, not just the premium. Make sure you understand roof settlement wording, exclusions, deductibles, and any conditions attached to coverage. For broader context on policy considerations in Florida, review Florida home insurance coverage guidance.
Preparation won’t dictate a carrier’s decision, but it can make your circumstances easier to assess and quote differences easier to identify. If you’re finding affordable home insurance with a bad roof in Pensacola, Si Insurance Agency works with carriers to compare home insurance options in light of your property details and coverage needs. Explore home insurance options as you prepare to compare.
Find a Practical Home Insurance Path With Si Insurance Agency
A roof concern can make the insurance process feel uncertain, but a methodical approach keeps the decision grounded in the home’s actual condition and the policy terms. Document what you know, provide accurate property information, compare coverage carefully, and weigh the premium against the protection and potential out-of-pocket costs. The aim isn’t simply to secure the lowest price; it’s to identify an option that fits your circumstances.
What to bring to a home insurance review
Gather any available roof records, inspection findings, repair invoices, maintenance notes, and clear photographs. Include accurate property details, and distinguish completed work from repairs that are planned or recommended. You don’t need to fill gaps with estimates; identify what is known and what remains uncertain.
It also helps to consider your household’s coverage priorities before reviewing options. Think about the dwelling coverage you need and which policy terms matter most, including deductibles, roof settlement language, and exclusions. Clear information gives the review a useful starting point and helps keep comparisons aligned with your needs.
Compare options with a Florida insurance agency
As a Florida-based independent agency, Si Insurance Agency works with insurance carriers to compare home insurance options in light of each homeowner’s circumstances. A comparison can help clarify how different offers address a roof concern, while carrier decisions, eligibility, premiums, and policy terms depend on the specific application and property.
For finding affordable home insurance with a bad roof in Pensacola, use the same decision path throughout: organize the roof information, compare policy wording, assess the premium alongside potential out-of-pocket costs, and select coverage that suits your situation. Learn more about Florida home insurance support as you consider your next steps.
Bring the records you have and the questions you want answered. A clear discussion of your roof documentation and coverage priorities can make it easier to understand the options for your circumstances. Discuss your home insurance options with Si Insurance Agency.
Move Forward With a Clearer Coverage Plan
A roof concern can affect insurance options, but it doesn’t answer every question about a home’s insurability. A stronger application starts with accurate roof records and a clear description of the property. Then compare equivalent limits and deductibles, paying close attention to roof settlement terms, exclusions, and any conditions attached to coverage.
Finding affordable home insurance with a bad roof in Pensacola means weighing the premium against the protection offered and the out-of-pocket costs you may face. The right choice depends on your home, your coverage priorities, and the terms available for your circumstances.
Si Insurance Agency, operated by SI Insurance LLC, is an independent Florida agency that works with carriers to compare home insurance options. With offices in Sunrise and Pompano Beach, the agency serves homeowners across Florida, including Pensacola. Discuss your Florida home insurance options with Si Insurance Agency to compare your roof documentation and coverage needs.
Frequently Asked Questions
Can I get home insurance in Pensacola with a bad roof?
Possibly, but the outcome depends on the roof, the property, and the insurer’s underwriting criteria. Finding affordable home insurance with a bad roof in Pensacola may involve sharing details about the roof’s age, material, condition, and repair history. An insurer may also request an inspection or additional records. Requirements differ by carrier, so a roof concern doesn’t automatically determine whether coverage is available or what it will cost.
Will homeowners insurance cover a roof that is already damaged?
Damage that existed before a policy began is generally treated differently from damage caused by a later covered event. Don’t assume a new policy will pay for a known, unrepaired problem. Coverage depends on the policy wording, the cause and timing of the damage, and any applicable exclusions or conditions. Describe the roof accurately during the application process and review the policy terms to understand the protection it provides.
Does an old roof make home insurance more expensive in Florida?
An older roof may affect the options, terms, or premium an insurer offers, but age alone doesn’t determine the outcome. Carriers may also consider material, visible condition, maintenance, inspection findings, and documented repairs. In Florida, including Pensacola, underwriting criteria can vary between insurers. Compare quotes using equivalent coverage limits and deductibles, then review roof settlement terms and exclusions to judge whether a premium difference represents meaningful value.
Can I get insurance before repairing my roof?
Possibly, but an insurer may require an inspection, request repair documentation, set conditions, limit available coverage, or decide not to offer a policy. The response varies by carrier and by the roof’s specific condition. Provide accurate information about existing damage and distinguish completed repairs from planned work. Review the insurer’s decision and policy documents rather than assuming coverage will begin on particular terms.
What roof documents should I provide when requesting a home insurance quote?
Provide available records that help establish the roof’s history and current condition. These may include installation or replacement records, repair invoices, maintenance notes, inspection reports, and clear photographs. Use documented dates rather than estimates, and identify recommended or planned repairs separately from completed work. An insurer may request additional information or use a different review process, so organized records help present the property clearly without promising a particular underwriting decision.
How can I compare home insurance quotes if my roof needs repairs?
Give each insurer the same accurate roof information and compare quotes with equivalent dwelling limits and deductibles. Then review the premium alongside roof settlement terms, exclusions, deductible structure, and any inspection or repair-documentation conditions. A lower price may come with different coverage or greater out-of-pocket costs. In Pensacola and elsewhere in Florida, assess how each policy addresses your circumstances rather than ranking offers by premium alone.
Does a roof inspection guarantee that an insurer will offer coverage?
No. An inspection provides information about the roof, but it doesn’t guarantee eligibility, a particular premium, or specific policy terms. Each insurer applies its own underwriting criteria and may consider the inspection alongside the roof’s age, material, condition, repairs, and other property details. Keep a copy of the report and share it accurately when requested. The insurer’s written offer and policy documents determine the available terms.
Comments