


Insurance Solutions for Homes That Failed a 4-Point Inspection in Fort Myers
Could a failed 4-point inspection automatically make a Fort Myers home uninsurable? Not necessarily. For homeowners looking for insurance solutions for homes that failed a 4-point inspection in Fort Myers, the result is a reason to examine the reported conditions, not a final decision about coverage. The next steps depend on the findings and each insurer’s review.
This guide explains how to read the inspection result, clarify concerns, gather repair records or other requested documents, and ask whether updated inspection information may help. It also covers how to compare home insurance options and what to prepare before speaking with an agent. Carrier eligibility, documentation requirements, and policy terms vary, so a clear, complete review can help you understand which options may be worth exploring.
Table of Contents
What a Failed 4-Point Inspection Means for Fort Myers Home Insurance
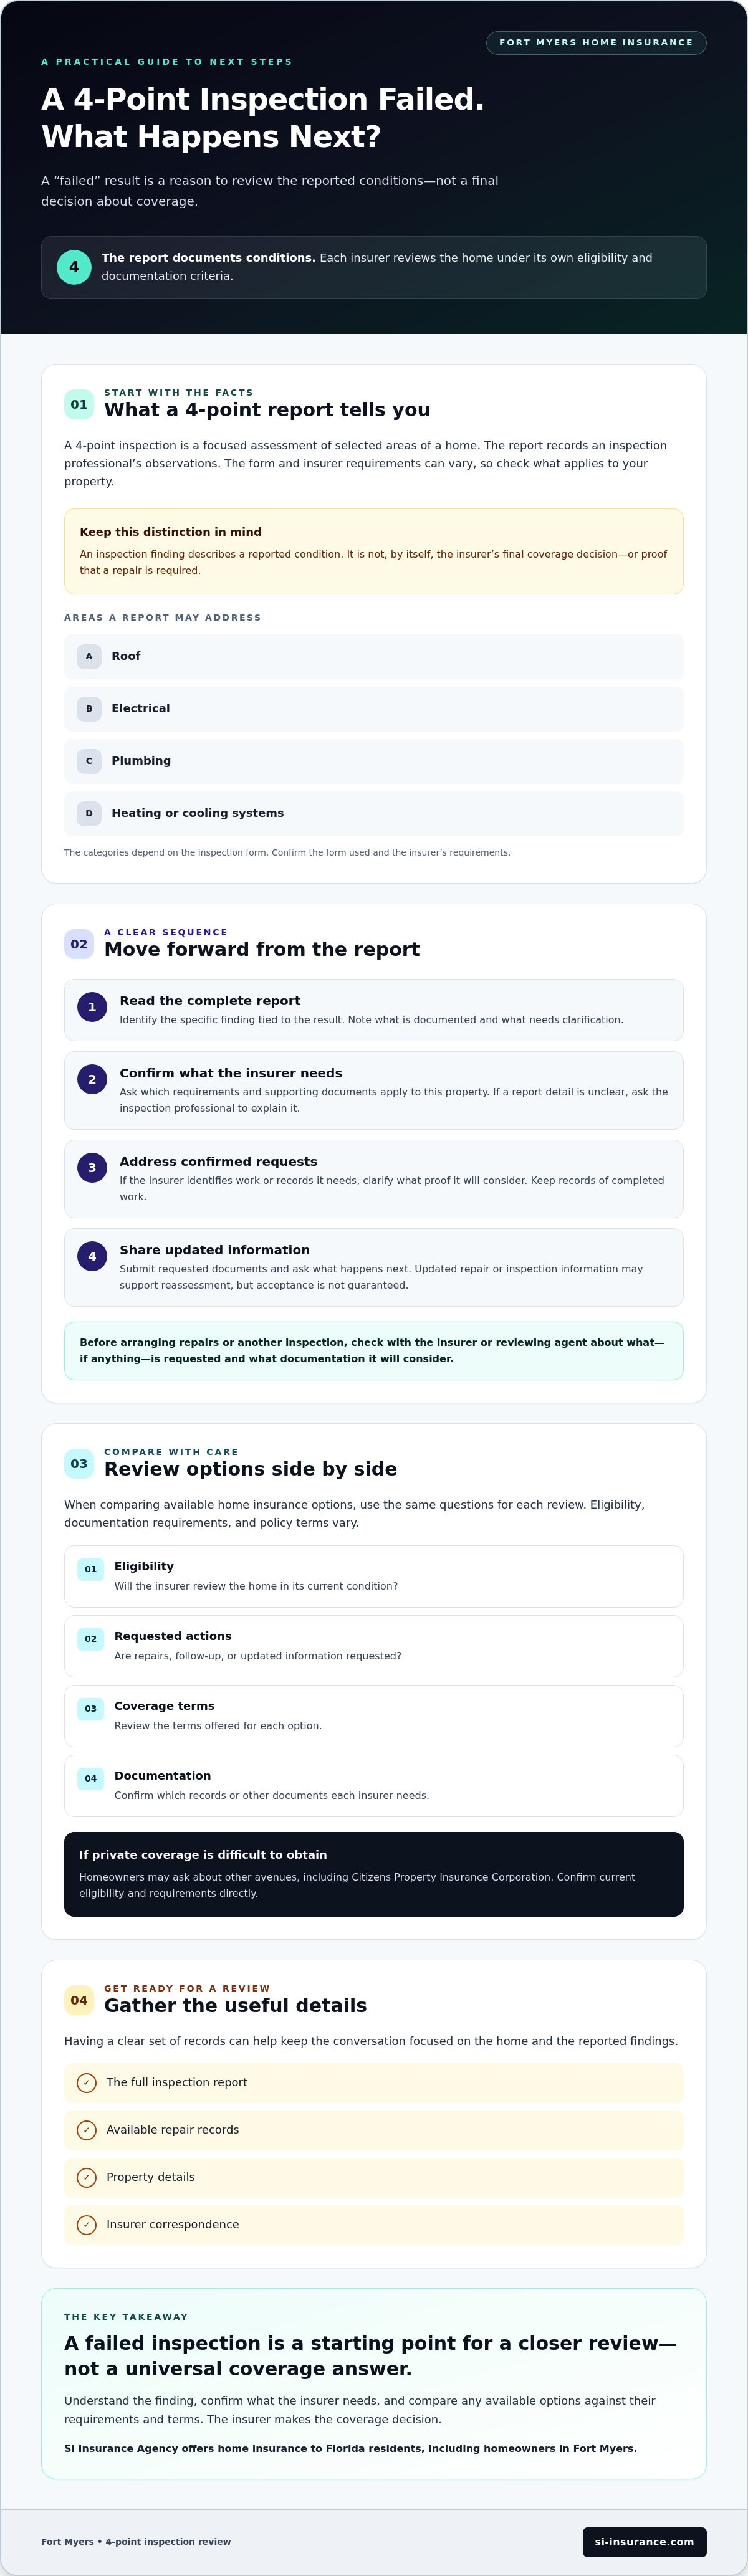
A 4-point inspection is a focused assessment of selected areas of a home that can help an insurer evaluate its condition. A result marked “failed” can be unsettling, but it does not establish that every insurer will decline coverage. The report records an inspection professional’s observations. Each insurer makes its own decision using its current eligibility and documentation criteria.
For homeowners seeking insurance solutions for homes that failed a 4-point inspection in Fort Myers, start by understanding the report rather than treating “failed” as a universal underwriting outcome. Confirm which form was used and what additional information the insurer needs for the specific property.
This video offers additional context on 4-point inspections and home insurance in the Fort Myers area:
Which home systems may appear in a 4-point report?
The categories depend on the inspection form, so confirm the current form and insurer requirements instead of assuming a general list applies. Reports may address major areas such as the roof, electrical, plumbing, and heating or cooling systems. The written findings, visible concerns, and supporting records can all inform the insurer’s review.
Read each finding and note what is documented, what needs clarification, and whether the report refers to records or follow-up. If a description is unclear, ask the inspection professional to explain it, then confirm with the insurer what documentation it needs. A reported concern is not automatically a confirmed repair requirement.
Does a failed report automatically mean no home insurance?
No. The inspection report alone does not settle the coverage outcome. The inspection professional documents property conditions, while the insurer evaluates the submission under its own criteria. The decision may depend on the findings, property details, and any additional documentation requested. A repair or updated report may be relevant if the insurer identifies it as part of its review, but acceptance is not guaranteed.
An inspection finding describes a reported condition; it is not the insurer’s final coverage decision. If private coverage is difficult to obtain, homeowners may also ask about other avenues, including the Citizens Property Insurance Corporation, while confirming current eligibility and requirements directly. For any option, a case-specific review is more useful than drawing conclusions from the word “failed” alone.
Fort Myers Options After a Failed 4-Point Inspection
A failed result is a cue to clarify the reported condition and the insurer’s next steps, not a reason to begin repairs based on assumption. First determine whether the report needs explanation or whether the insurer has identified a specific condition for considering coverage. Repairs, another inspection, or additional records may be relevant, but the right response depends on the findings and the insurer reviewing them.
A practical sequence is to:
Read the complete report and identify the specific finding associated with the result.
Ask the insurer or reviewing agent which requirements and supporting documents apply.
Address confirmed issues if requested, and keep records of completed work.
Submit requested updated documents and ask what happens next.
For homeowners exploring insurance solutions for homes that failed a 4-point inspection in Fort Myers, this process keeps decisions grounded in the actual findings. An insurance agent can review whether available options may fit the home’s current condition and clarify what information is needed for an assessment.
When might repairs or an updated inspection help?
Start by clarifying the concern in the report. Before arranging repairs or another inspection, ask the insurer or reviewing agent what work, if any, is requested and what proof it will consider. Depending on the situation, that proof may include repair records or updated inspection documentation. Updated information may support a reassessment, but it does not guarantee an offer or particular terms.
What if repairs are not immediately possible?
If work cannot be completed right away, discuss the report and timing with an insurance professional before concluding that no options remain. Ask whether documents could help the insurer review the home as it currently stands, and whether a review can proceed while you clarify the concern. Confirm whether any temporary arrangement or alternative is available for your circumstances rather than relying on assumptions.
Eligibility and coverage depend on insurer review and property-specific facts. Keep the report and related correspondence together so the discussion focuses on the same documented details. Si Insurance Agency offers home insurance in Florida, including to residents in Fort Myers. You can review SI Insurance’s insurance services to discuss your property and coverage needs.
How to Compare Fort Myers Insurance Options After an Inspection Failure
A quote summary may not show what an insurer expects after reviewing an inspection report or how the written policy would respond. Compare offers using the same property details and a similar scope of coverage wherever possible. For insurance solutions for homes that failed a 4-point inspection in Fort Myers, assess both the insurer’s position on the findings and the policy terms offered.
Use the table as a working checklist, not a substitute for the insurer’s written materials. Offers with different limits or exclusions may not be directly comparable, even if their quote summaries look similar. Ask for clarification before deciding which option better fits your needs.
Which questions should homeowners ask before choosing?
Ask whether the insurer considered the complete inspection report and any repair records you provided. Confirm whether it needs specific repairs, a follow-up inspection, or other documents, and ask when they are due. Then request a clear explanation of the conditions, exclusions, and coverage limits in the written offer. Keep the answers together so you can compare options consistently.
How can you assess coverage beyond the initial quote?
Review the policy documents and declarations rather than relying only on a preliminary quote summary. Verify the property details and requested effective date. Check the applicable deductibles, exclusions, and limits. If an inspection-related condition or restriction is unclear, ask the insurer or reviewing agent to explain it before deciding.
A useful comparison shows what the insurer has reviewed, what remains required, and what coverage the written documents describe. To discuss home insurance options, review Si Insurance Agency’s insurance services.
A Practical Fort Myers Checklist for Moving Forward
Organizing the inspection and follow-up documents gives a coverage review a clear starting point. Before contacting an agent, gather the records you have, note what remains uncertain, and prepare a concise account of the property’s current condition. This helps keep the discussion focused without assuming a particular repair or coverage outcome.
Gather the complete inspection report. Include notes, photographs, or attachments supplied with it so the reviewer can see the findings in context.
Collect records related to reported concerns. Available receipts, contractor records, and updated inspection documents may help explain completed work or changes since the report.
Set aside relevant policy documents. For a renewal or replacement discussion, include the current policy and related insurer correspondence.
Mark questions and requested follow-up. Note unclear findings, actions an insurer has requested, and any response timing it has provided.
Request a property-specific review. Ask what additional information is needed to assess options for the Fort Myers home and confirm how the agent will follow up.
What documents should you have ready?
Start with the full 4-point report, not just a summary or the page showing the result. Add records related to the findings, such as available repair receipts, contractor documentation, or updated inspection materials. For a renewal or replacement discussion, include the current policy and insurer letters or messages explaining the circumstances. Keep copies together so you can track what has been submitted and what may still be needed.
How should you prepare for an agent conversation?
Be ready to summarize the result and explain whether anything has changed since the inspection, such as completed work or a clarified concern. Ask what other property details or documents would help assess available options. Before ending the conversation, confirm the expected follow-up and next steps. A preliminary discussion is not a binding offer of coverage, so rely on the insurer’s written terms.
For broader context on policy considerations, see Home Insurance in Florida: A Strategic Guide. If you’re exploring insurance solutions for homes that failed a 4-point inspection in Fort Myers, contact SI Insurance to discuss your inspection documentation. Si Insurance Agency serves homeowners throughout Florida, including Fort Myers, and any coverage remains subject to insurer review.
Review Fort Myers Home Insurance Options with SI Insurance
A failed inspection report can leave homeowners unsure what to do next. A focused review can clarify what information an insurer may need and which options merit further consideration. SI Insurance offers home and homeowners insurance throughout Florida, including Fort Myers. Eligibility and policy terms remain subject to insurer review.
What to expect when requesting an insurance review
An initial conversation can begin with the property details, inspection findings, and coverage you’re seeking. Sharing the complete report, available repair records, and relevant insurer correspondence gives the reviewer a clearer picture than a short summary of the result. Explain what has changed since the inspection and what matters most to you in a policy.
An insurer may need more information to assess eligibility. Requested documents and review steps depend on the situation, so submitting a report does not guarantee a quote, approval, or policy by a particular time. Ask what else is needed and how you will receive an update.
Make your next decision with clear information
If options are presented, review the written terms carefully. Check that the property details are accurate, then confirm the coverage limits, exclusions, deductibles, effective date, and any inspection-related conditions. If a requirement or limitation is unclear, ask for an explanation before accepting an offer or arranging work based on an assumption.
For a broader discussion of policy considerations, readers can consult Home Insurance in Florida: A Strategic Guide. The report-specific review helps clarify the property information under consideration. Reviewing the policy helps you understand the terms being offered. Consider both as you weigh your next step.
For homeowners exploring insurance solutions for homes that failed a 4-point inspection in Fort Myers, an agent can help organize questions and determine whether further review may be appropriate. Coverage is not guaranteed, but SI Insurance offers home insurance to Florida residents. To discuss your options, contact SI Insurance with your inspection documents ready.
Move Forward with a Clear Coverage Review
A failed 4-point inspection is a documented finding, not a universal decision about whether a home can be insured. Understand the specific concerns, confirm what an insurer requires, and provide the complete report and relevant repair records for review. When comparing options, look beyond a quote summary and check the written coverage terms, conditions, and documentation requirements.
Si Insurance Agency offers home and homeowners insurance throughout Florida, including Fort Myers. Eligibility and policy terms depend on insurer review. If you’re considering insurance solutions for homes that failed a 4-point inspection in Fort Myers, an organized conversation can help clarify what to explore next.
Discuss your Fort Myers home insurance options with your inspection documents ready. A clear record can help you take the next step with a better understanding of what is being reviewed.
Frequently Asked Questions
Is a home uninsurable in Fort Myers after it fails a 4-point inspection?
No. A failed report alone does not establish that every insurer will decline the home. Each insurer assesses the property and submitted documents under its current criteria, so the outcome depends on the circumstances. Review the complete report and ask an insurance agent which options, if any, may be considered. Approval is not guaranteed, and a preliminary review is not confirmation of coverage.
What does a 4-point inspection check in Florida?
A 4-point report addresses specified areas of a home, but confirm the applicable form and insurer requirements before assuming which components or thresholds apply. Use the report prepared for your property as the reference for its findings, including notes and attachments. Then ask the insurer what supporting records it needs. Requirements may differ, so a generic component list is not a definitive standard.
Can I get homeowners insurance in Fort Myers if I complete the repairs?
Possibly, but completing repairs does not guarantee approval or a particular policy. Ask the insurer which reported issues it considers necessary to address and what proof it will accept. After the work is completed, provide relevant records and ask for written confirmation of any remaining requirements. The insurer makes its decision based on the property and its current criteria, so repairs alone do not settle eligibility.
How do I find insurance solutions after a failed 4-point inspection?
Obtain the complete report, clarify each finding, and gather available repair records or updated inspection documents. Discuss the property and its circumstances with an insurance professional, then ask which options can be reviewed and what documents are needed. Insurance solutions for homes that failed a 4-point inspection in Fort Myers depend on insurer review and property-specific details. Not every insurer can place every home, and coverage is not assured.
Can an insurance agent help with a failed 4-point inspection in Fort Myers?
An agent can discuss the report, identify information needed for a review, and explain options available through the agency. Si Insurance Agency offers home and homeowners insurance throughout Florida, including Fort Myers. An agent cannot guarantee an insurer’s approval or override its requirements. Share the complete report and ask what additional records may be useful.
What documents should I send when requesting a home insurance quote after an inspection failure?
Prepare the complete inspection report, available records for completed repairs, accurate property details, and relevant correspondence from your current or prospective insurer. The agent or insurer may request more information, so confirm what is needed and how to submit it. Complete, accurate records can support a review, but they do not guarantee a quote, eligibility, or specific policy terms. Keep copies of everything you provide.
Is a 4-point inspection the same as a wind mitigation inspection?
No. These are distinct inspection terms, and one report should not be assumed to replace the other. Confirm the purpose, form, and insurer requirements for each inspection for the specific property and application. Ask the reviewing insurer or agent which reports are requested and whether existing documents meet its needs. Do not assume an inspection affects premiums or coverage in a particular way without current, case-specific confirmation.
Comments