


Miami Home Insurance Cancellation Appeal Guide 2026
Can you challenge a home insurance cancellation in Miami? Appealing a home insurance cancellation in Miami may be possible, but first determine whether the notice describes a cancellation or a nonrenewal, and identify the dates and instructions it gives. If you’re unsure whether coverage continues while the insurer reviews your request, don’t assume it does. An appeal is only one part of your plan.
This guide explains how to read your notice, request an insurer review, and prepare a clear, evidence-supported case when reconsideration is appropriate. It also covers why exploring replacement coverage at the same time can help you plan for a possible gap.
You’ll learn how to check the stated reason and supporting documents, organize records that address the insurer’s concerns, and distinguish an internal review from a formal complaint. A review doesn’t guarantee the insurer will reverse its decision. SI Insurance can also help you explore replacement home insurance options through its carrier network, subject to availability for your property. The goal is a practical two-track approach: seek reconsideration while planning for continuous coverage.
Key Takeaways
Check the notice’s wording, stated reason, and dates before deciding what to do.
For appealing a home insurance cancellation in Miami, use the insurer’s official channel and support your reconsideration request with relevant records.
Understand the different roles of an insurer review, consumer complaint, legal counsel, and replacement-policy search.
Track your communications and ask prospective insurers what details they need to assess your property.
An independent agency may help explore replacement home insurance options, but it cannot guarantee reinstatement or provide legal advice.
Table of Contents
Received a Miami home insurance cancellation notice? Identify what it means first
How to challenge a home insurance cancellation in Miami with a documented review request
Appeal, complaint, legal advice, or replacement coverage: compare your Miami options
A practical checklist for protecting coverage while your cancellation is reviewed
How a Florida insurance agency can help after a Miami home policy cancellation
Received a Miami home insurance cancellation notice? Identify what it means first
A notice about your home insurance can be unsettling, especially if it isn’t clear whether your protection is ending or the insurer needs more information. Before deciding whether to dispute it, read the wording and dates carefully. They clarify what the insurer says is happening and whether the notice asks you to take action.
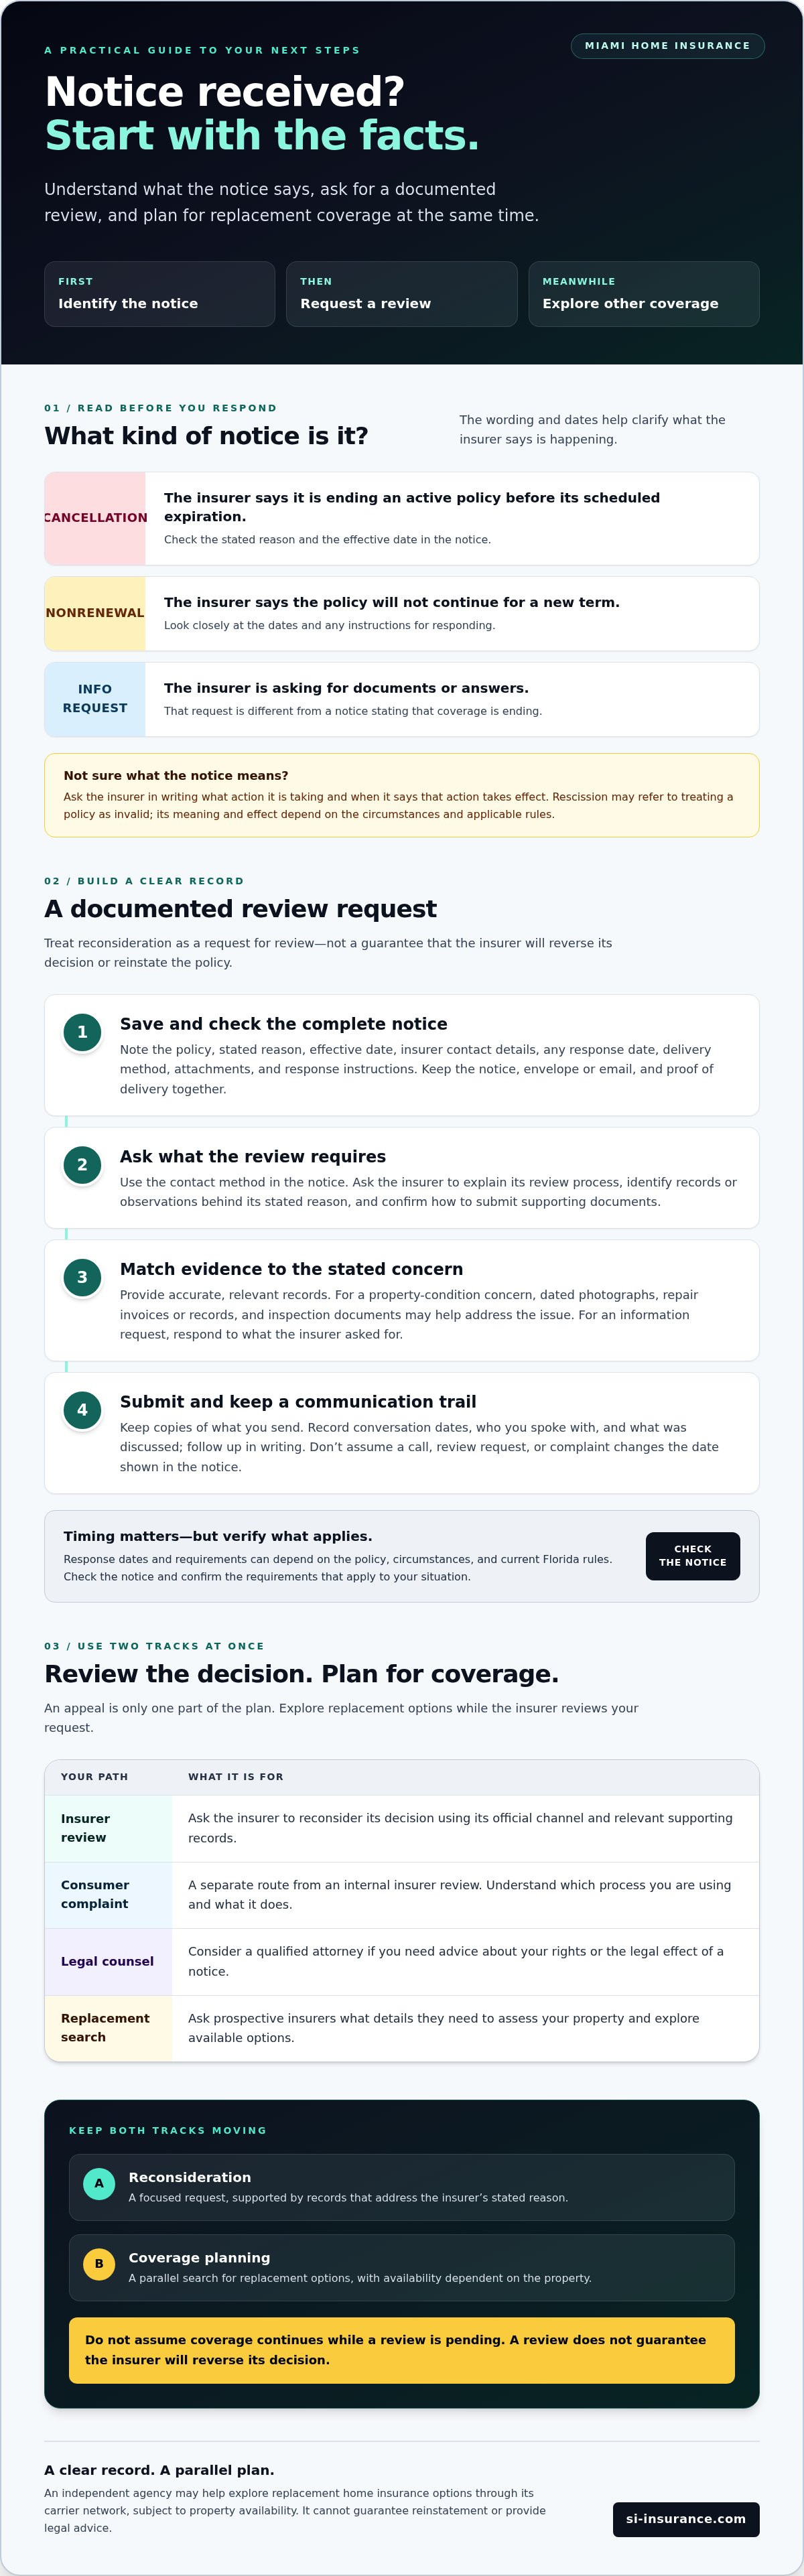
A cancellation generally means an insurer is ending a policy before its scheduled expiration. A nonrenewal means the policy is not being continued for a new term. A request for additional information is different: it may ask you to provide documents or answer questions without stating that coverage is ending. Terms and requirements can depend on the policy, the notice, and current Florida rules, so check the details rather than assuming a particular deadline applies.
For a neutral introduction to what home insurance covers, see this overview. Then focus on the notice you received and the action it actually requests.
This video offers another perspective on what to do after a cancellation notice:
How to read the cancellation notice without overlooking a deadline
Check the policy named, the reason given, the effective date, the insurer’s contact details, and any requested response date. Note how the notice was delivered and whether it includes attachments or instructions for responding. Keep the full record together, including the envelope or email and any proof of delivery. Don’t assume that a call, appeal, or complaint changes the date shown in the notice.
Cancellation, nonrenewal, or rescission: which situation applies?
Check whether the notice concerns an active policy, an upcoming renewal, or the insurer’s position on the policy’s validity. Rescission may refer to treating a policy as invalid, but its meaning and effect depend on the circumstances and applicable rules. If the wording is unclear, ask the insurer to explain in writing what action it is taking and when it says that action takes effect.
Save the notice before contacting the insurer. After any conversation, record the date, the person you spoke with, and what was discussed, then follow up in writing. If you’re considering appealing a home insurance cancellation in Miami, confirming the notice type is a practical first step, not a conclusion about whether the insurer’s decision is valid. If you’re unsure about your rights or the notice’s legal effect, consider speaking with a qualified attorney.
How to challenge a home insurance cancellation in Miami with a documented review request
Once you’ve identified what the notice says, you can ask the insurer to review its decision. Treat this as a request for reconsideration, not an assurance that a formal appeal process exists or that the policy will be reinstated. Use the contact method specified in the notice. Ask the insurer to explain its review process, identify the records or observations behind its stated reason, and confirm how to submit supporting documents.
Keep timing in view. Any response date on the notice, and any applicable requirements, may depend on the circumstances, policy, and current Florida rules. Verify what applies rather than relying on a general deadline. United Policyholders offers an overview of consumer rights in Florida; for advice about how rules apply to your situation, consult a qualified attorney.
What evidence may help address the insurer's stated reason?
Choose records that directly address the issue named in the notice. If it raises a property-condition concern, dated photographs, repair invoices or records, and inspection documents may help clarify the home’s condition or show work completed. If the insurer requested information, provide accurate, responsive records instead of unrelated paperwork. Don’t alter documents to make them appear more favorable or claim that a repair resolved an issue unless the evidence supports that statement.
How to make a clear written request for reconsideration
Make your request factual and easy to review. Identify the policy and notice, explain which part of the insurer’s stated reason you’re asking it to reconsider, and request a written response. This concise structure can help:
Policy and notice: Include the policy identifier and the date of the notice.
Issue and request: Briefly describe the reason given and ask for a review.
Supporting records: List or attach the documents that address that reason.
Confirmation: Ask the insurer to confirm receipt and explain its review steps.
Stay respectful, even if you disagree. Avoid unsupported accusations, speculation about the insurer’s motives, or statements that could inaccurately describe the property or events. Save your request and build a simple timeline with submission dates, contact names, reference numbers, and responses. This record helps you track the review and decide what to do next. While pursuing appealing a home insurance cancellation in Miami, you can also explore replacement home insurance options independently. An agent at SI Insurance can help explore coverage paths, but can’t determine your legal rights or compel the insurer to reverse its decision.
Appeal, complaint, legal advice, or replacement coverage: compare your Miami options
These options address different needs. An insurer review asks the company to reconsider its decision. A complaint seeks help through a consumer or regulatory process. Legal counsel can advise you about your rights. A replacement-policy search focuses on keeping coverage in place. A complaint does not automatically reverse an insurer’s decision, and pursuing a review alone may not prevent a lapse.
When to contact Florida insurance regulators or consumer assistance
The Florida Department of Financial Services and the Florida Office of Insurance Regulation are entities to check for current consumer guidance and complaint pathways. Their responsibilities and submission routes may differ, so confirm which agency handles your type of concern before filing. Prepare the policy, notice, correspondence, and a dated timeline so you can explain the issue clearly. A complaint may bring attention to a concern, but it doesn’t replace individualized legal advice or determine whether you have a court remedy.
When a Florida attorney or replacement policy may be appropriate
Consider speaking with a Florida attorney if the facts are complex, the consequences are significant, or you’re unsure what the notice means for your rights. At the same time, begin exploring replacement coverage if reinstatement is uncertain or the stated end date is approaching. Don’t wait for an appeal or complaint to conclude before asking what coverage may be available for your property.
For context as you compare options, review the agency’s Florida home insurance options. An independent agency may help explore replacement coverage through its carrier network, subject to underwriting and availability for your property. It can’t compel reinstatement or provide legal representation. Keep both tracks moving: pursue your review while preparing a plan for continuous coverage.
A practical checklist for protecting coverage while your cancellation is reviewed
Keep the review and the replacement-coverage search moving side by side. A reconsideration request may take time and may not change the insurer’s decision, so don’t rely on it alone to prevent a gap. Use the dates in your notice to build a personal action list, and confirm applicable deadlines or requirements with the insurer or a qualified professional.
A simple timeline can keep both tracks organized:
On the day you receive the notice: Confirm which policy and property it names, the reason given, and the stated effective date. Save the notice and its attachments.
After reviewing the notice: Contact the insurer through its official channel to ask about its review process and the evidence it needs. Record the date, contact name, and any reference number.
As you prepare your request: Gather documents that directly address the stated concern, submit copies, and note when and how you sent them.
While awaiting a reply: Contact prospective insurers or an independent agent to ask what information they need and whether your property’s circumstances affect eligibility.
Documents to prepare for an insurer or agent
Keep the declarations page, cancellation notice, property details, and relevant correspondence together. If they address the reason in the notice, include maintenance or repair records, inspection documents, and mitigation information. Share accurate details consistently with your current insurer and any prospective insurer. Retain copies of applications and submitted documents so you can check what information each party received.
Questions to ask before replacement coverage begins
Don’t treat a quote or application as confirmation that coverage is in force. Ask the prospective insurer to confirm the proposed policy’s effective date and how it aligns with the current policy’s stated end date. Request written clarification about exclusions, conditions, inspection requirements, or outstanding items. Compare coverage limits and deductibles as well as the premium.
Property-specific underwriting questions may arise in Miami-Dade, but don’t assume a single local rule determines whether a home qualifies. Describe the property accurately and ask the insurer to explain its requirements in writing. Before making a change, confirm that replacement coverage has actually been issued and when it begins. Don’t cancel existing coverage based only on an unconfirmed application.
If you’re appealing a home insurance cancellation in Miami while preparing for a possible transition, explore replacement home insurance options with SI Insurance. An independent agency may help you review available paths through its carrier network, subject to underwriting and availability for your property.
How a Florida insurance agency can help after a Miami home policy cancellation
A cancellation notice can leave you managing two separate tasks: asking your current insurer to review its decision and working out how to maintain coverage if the policy ends. An independent Florida insurance agency may help with the second task by exploring replacement home insurance options through its carrier network. Whether a carrier can offer coverage depends on its underwriting and your property details.
For a useful discussion of options, bring the notice, declarations page, and relevant property information. If the notice identifies a concern about the roof, repairs, or another condition, records that clarify the issue may help an agent understand what information a prospective insurer could request. Be prepared to describe the home accurately, including known updates or unresolved conditions. An agent can help explore potential paths, but can’t promise that a carrier will accept the property.
What an independent agent may help you evaluate
An agent can discuss your property details and available carrier options, then help you compare proposed terms. Review coverage limits, deductibles, exclusions, and any conditions or information requirements carefully. Ask questions about anything you don’t understand, and request clarification from the insurer before deciding. A quote or preliminary discussion isn’t confirmation that a policy has been issued or that coverage is in force.
SI Insurance is an independent Florida agency offering home insurance and helping customers explore coverage options through its carrier network. Learn more about Florida home insurance options and the information that may be useful for a discussion. Availability for a specific Miami property must be confirmed.
A calm next-step plan for Miami homeowners
Keep a record of your communications with the current insurer and continue pursuing its review through the channel it provided. At the same time, explore replacement coverage if the policy’s end date is approaching or the outcome remains uncertain. Before relying on a new policy, confirm that it has been issued and check its effective date. Don’t assume a review pauses the current policy’s stated end date.
For questions about applicable requirements or complaint processes, check current information from official Florida sources. If you need an assessment of your legal rights or advice about a complex dispute, speak with a qualified attorney. An insurance agent can help explore coverage alternatives, but can’t determine your legal rights, replace an attorney, or guarantee reinstatement.
If you’re appealing a home insurance cancellation in Miami, you don’t have to treat the review and replacement search as competing choices. SI Insurance can help you explore available home insurance options while you pursue the insurer’s review independently.
Take a clear next step toward continuous coverage
A cancellation notice calls for two parallel steps: understand the insurer’s stated reason and dates, then prepare a documented request for review if reconsideration is appropriate. Keep copies of your communications, and don’t assume an appeal or complaint will pause the date in the notice. If your current coverage may end, explore replacement options at the same time rather than waiting for the review to conclude.
SI Insurance Agency is an independent Florida agency with access to a network of insurance carriers, with offices in Sunrise and Pompano Beach and service across Florida. An agent may help you explore home insurance options for your property, subject to carrier underwriting and availability, but can’t guarantee reinstatement or provide legal advice.
For help considering your next coverage path, explore Florida home insurance options with SI Insurance Agency. With a clear record and a practical plan, appealing a home insurance cancellation in Miami can become a more manageable process. Take it one step at a time.
Frequently Asked Questions
Can I appeal a home insurance cancellation in Florida?
You can contact your insurer to ask whether it will reconsider and provide information that addresses the reason in the notice. Whether a formal appeal is available, what deadline applies, and whether coverage continues depend on your policy, notice, and current law. Verify the process and dates promptly with the insurer and an official Florida source. If the consequences or your rights are unclear, consider getting advice from a qualified attorney.
How long do I have to respond to a home insurance cancellation notice in Florida?
There isn’t one universal response deadline you can safely assume from a general article. Check the notice for its effective date, response instructions, and any stated deadline, then verify applicable requirements with the insurer and current official Florida guidance. Keep a record of when and how you contacted the insurer. Don’t assume that requesting a review or filing a complaint extends coverage or pauses a deadline.
What should I do first after receiving a home insurance cancellation notice in Miami?
Read the complete notice and identify the policy, the insurer’s stated reason, the effective date, and any response instructions. Save the notice and related records, then contact the insurer through a verified channel to ask what review process applies. If the stated end date is approaching, explore replacement coverage at the same time. A request for reconsideration doesn’t guarantee that your current coverage will continue.
Can the Florida Department of Financial Services help with a home insurance cancellation?
The Florida Department of Financial Services offers consumer-facing insurance assistance, but confirm its current role and available complaint pathways through official state sources. Before reaching out, gather your policy, notice, insurer correspondence, and a dated timeline of events. An inquiry or complaint may help you understand possible next steps, but it doesn’t guarantee that the insurer will reverse its decision or confirm that your policy remains active.
Will filing a complaint stop my home insurance cancellation?
Don’t assume that filing a complaint pauses a cancellation, changes the effective date, or restores coverage. Any effect depends on the circumstances and applicable requirements, so confirm your policy status and relevant dates with the insurer and current official Florida sources. Keep exploring replacement options if needed rather than waiting for a complaint response. If you’re unsure about a deadline or legal right, consider consulting an attorney.
Can an insurance agent reverse my home insurance cancellation?
No. An independent agent doesn’t control the current insurer’s decision and can’t guarantee reinstatement or determine your legal rights. An agent may help you explore replacement home insurance through available carrier options, subject to underwriting and availability for your property. SI Insurance Agency serves customers across Florida, including Miami-area homeowners. Keep the reconsideration request with your insurer, and consult a qualified attorney for legal advice about disputed rights or obligations.
Should I look for a new home insurance policy while appealing a cancellation?
It can be prudent to explore alternatives while the insurer reviews your request, particularly if the notice’s effective date is approaching. A quote or application isn’t confirmed coverage. Before relying on a replacement policy, verify that it has been issued, review its terms, and confirm its effective date. Don’t assume an appeal keeps your current policy in force, and avoid making coverage changes until you understand how the dates align.
Comments