


Options for Homes Deemed Uninsurable Due to Roof Age in Naples
If you’re weighing options for homes deemed uninsurable due to roof age in Naples, it can feel as though your only choices are replacing the roof right away or risking a gap in coverage. But one insurer’s concern is a reason to review your choices, not proof that homeowners coverage is out of reach. Insurers may consider the roof’s age, condition, and inspection information, and their criteria can differ.
This guide explains why an older roof may prompt additional scrutiny and outlines practical paths to consider. You’ll learn how to document the roof’s age and condition, when an inspection may help clarify its remaining useful life, and what to gather for an insurance review. SI Insurance can compare home insurance options across its network of carriers. With a clearer picture of the roof and available options, you can decide what to do next.
Table of Contents: Options for Homes Deemed Uninsurable Due to Roof Age in Naples
Why an Older Roof Can Complicate Home Insurance in Naples
An older roof can raise questions during a home insurance review, but age alone doesn’t automatically mean coverage is impossible. Insurers may consider age alongside visible condition, materials, maintenance history, and available inspection information. A roof with a documented repair history may present a different picture from one with visible damage or little information about its upkeep.
These details are part of the insurance underwriting process, in which an insurer evaluates information about a property before making a decision. If you’re exploring options for homes deemed uninsurable due to roof age in Naples, distinguish one insurer’s application or renewal decision from a broader conclusion about every possible coverage path. Each carrier sets its own criteria, and only the insurer can determine how it will assess a particular home.
Does roof age alone make a Naples home uninsurable?
Not necessarily. Roof age may be one factor among several, and insurers can weigh it differently depending on the roof’s condition and other property-specific details. There isn’t one universal age cutoff that applies to every insurer or home. A decision about one application or renewal describes that insurer’s response, not whether other coverage options can be explored.
Why roof condition and local exposure enter the review
Damage, maintenance records, roof materials, and inspection findings can help explain the roof’s current condition rather than relying on age alone. Clear photographs and records of completed work can also make the property information easier to assess. A professional inspection can document condition, but it can’t guarantee an insurer will accept the home.
In Naples and across Florida, a home’s location is another part of its property profile. Insurers may assess local exposure alongside roof details, but the outcome depends on the carrier’s review of the individual property. Roof-related underwriting is an insurer’s assessment of how a roof’s age, condition, and related property details affect its coverage decision.
For broader context on coverage considerations in the state, see this Florida home insurance overview. Knowing what an insurer may review can help you prepare useful information and consider next steps without assuming that one decision settles every possibility.
What to Review Before Choosing an Insurance Path for an Older Roof
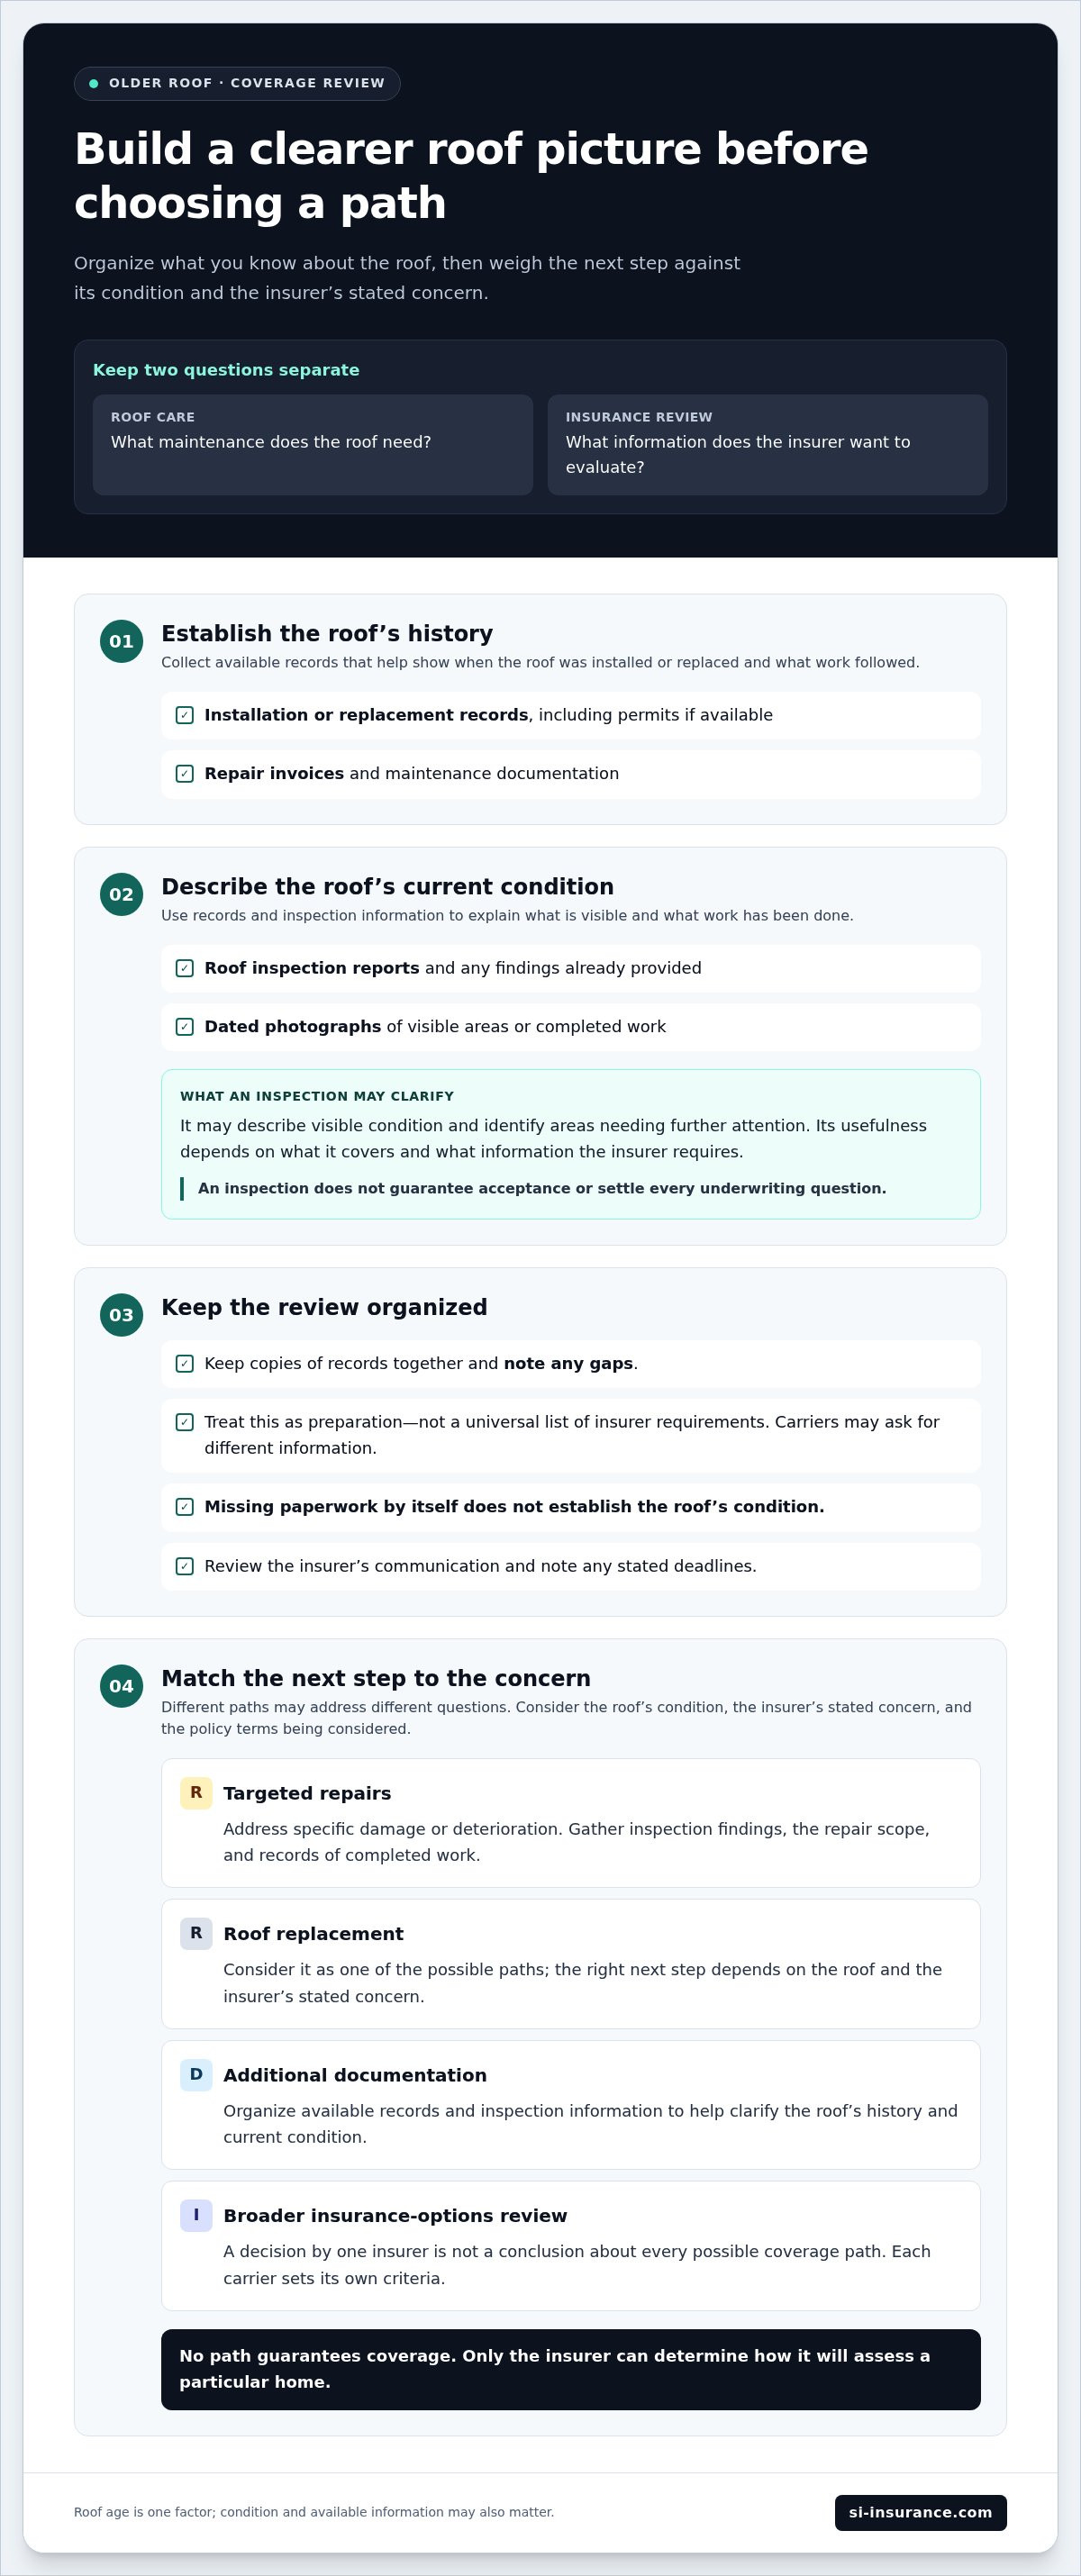
Before deciding whether to repair, replace, or pursue another coverage path, gather what you know about the roof. A clear record can help explain its history and current condition. Keep two questions separate: what maintenance the roof needs and what information an insurer wants to evaluate.
Which roof records can help clarify the situation?
Collect available documents that help establish when the roof was installed or replaced and what work has been done since. Depending on what you have, useful records may include:
Installation or replacement records, including permits, if available
Repair invoices and maintenance documentation
Roof inspection reports and any findings already provided
Dated photographs showing visible areas or completed work
These are preparation materials, not a universal list of insurer requirements. One carrier may ask for different information than another, and a document’s relevance depends on the property and the review. Keep copies together and note any gaps. Missing paperwork, by itself, doesn’t establish the roof’s condition.
What can a roof inspection establish?
A professional inspection may describe visible condition and identify areas that need further attention. Its usefulness depends on what the inspection covers and what information the insurer requires. An inspection doesn’t guarantee acceptance or settle every underwriting question. If the report identifies a maintenance concern, consider that separately from any insurer request. Addressing a roof issue may be prudent, but it doesn’t necessarily resolve every coverage question.
For homeowners comparing options for homes deemed uninsurable due to roof age in Naples, an inspection’s practical value is clearer documentation, not a promised outcome. Florida insurance legislation can provide broader background to the coverage environment. The Florida Senate’s page on Florida Senate Bill 2-A is a primary source for the bill itself, rather than a substitute for reviewing an insurer’s specific request.
Once your records are organized, the Florida home insurance guide offers broader context for considering coverage. Reviewing roof information alongside the home’s insurance needs can help frame a more informed discussion of available options.
Compare Roof Repairs, Replacement, and Other Coverage Paths
There isn’t one response that fits every roof-related insurance concern. A focused repair, full replacement, more documentation, or a broader review of insurance options may each address a different question. The right next step depends on the roof’s condition, the insurer’s stated concern, and the policy terms being considered. None of these paths guarantees coverage.
When might repair or roof replacement be worth evaluating?
Unresolved damage or visible deterioration may make roof work worth assessing, but replacement isn’t automatically the right response to an age-related concern. Consider the inspection findings, extent of any damage, work already completed, and what the insurer’s communication actually requests. A repair may address a specific condition; replacement may be worth considering when the issues are broader. Neither choice ensures an insurer will accept the home.
What should homeowners compare in available policy options?
Look beyond the premium. Compare the covered property, roof-related terms, deductibles, exclusions, and stated settlement basis. Actual cash value generally accounts for depreciation, while replacement cost generally refers to the cost to repair or replace covered property without subtracting depreciation. Exact definitions, limits, and conditions depend on the policy. A roof’s documented condition and a policy’s terms are distinct considerations. For neutral consumer information, the Florida Department of Financial Services provides resources through Florida’s Insurance Consumer Advocate. Reviewing the complete policy terms can clarify trade-offs that a single premium figure won’t show.
For homeowners weighing options for homes deemed uninsurable due to roof age in Naples, an independent agency can compare options from its network of carriers. The insurer makes the underwriting decision and sets the policy terms.
Steps Naples Homeowners Can Take After a Roof-Related Insurance Concern
A roof-related notice can feel urgent, especially when a renewal or application decision is involved. Start with what the insurer has put in writing, then organize the roof information and compare next steps with the dates and terms that apply to your policy. Don’t assume a renewal, extension, or change in timing unless it’s confirmed in writing.
How to organize a roof and policy review
Create a simple timeline so the roof’s history and insurance communications are easy to follow. Include installation or replacement information, repairs, inspections, and the dates of notices or conversations with the insurer. Keep copies of the full policy, written decisions, inspection reports, repair records, and dated photographs together.
Review the policy and notice for effective and expiration dates, roof-related terms, the insurer’s stated reason, and any response or action dates. If the wording is unclear, write down specific questions, such as whether the concern relates to roof age, condition, missing documentation, or a stated policy term. A clear record helps keep those issues distinct.
How to compare possible next steps without rushing
Once your information is organized, compare possible roof work or documentation with the property’s condition, policy language, and your timing and circumstances. Pay attention to any date stated by the insurer, but don’t treat it as an extension or automatic renewal. If the notice gives a deadline, treat it as meaningful unless the insurer confirms otherwise in writing.
Then compare available insurance options using the actual written terms and any eligibility decision, not a verbal impression or premium alone. Review what the policy says about the home and roof, including applicable exclusions, deductibles, and settlement terms. If Citizens Property Insurance Corporation or another state program comes up, confirm current eligibility criteria and program details through current official information. Don’t assume a prior rule or another homeowner’s experience applies to your property.
For homeowners considering options for homes deemed uninsurable due to roof age in Naples, a measured review can help distinguish a roof-maintenance decision from an insurance decision while keeping the insurer’s stated requirements and timing in view. Si Insurance Agency is an independent Florida agency that compares home insurance options through its network of carriers. Review home insurance options with your roof and policy information organized.
Review Naples Home Insurance Options With Si Insurance Agency
A roof-related underwriting concern can leave you unsure whether to focus first on roof work, additional records, or another insurance option. Si Insurance Agency is an independent Florida agency offering home insurance through a network of carriers. A coverage review brings the home’s details, roof documentation, and available options into one conversation, helping you understand what may be worth considering next.
What information can make a coverage conversation more useful?
Having key records close at hand can make it easier to discuss the situation clearly. Consider gathering:
Your current policy and any written notice or decision from the insurer
Available roof details, such as its age, material, and known repair or replacement history
Inspection findings, repair records, and dated photographs you already have
Your questions, coverage priorities, and any timing concerns raised in the insurer’s communication
You don’t need every record before starting a review. The goal is to explain what’s known, identify what remains unclear, and distinguish the insurer’s stated concern from your broader coverage needs. Documentation can support a more informed discussion, but it doesn’t guarantee that an insurer will accept the property or offer particular terms.
How an independent agency can support a comparison
An independent agency can match clients with options from its carrier network, helping put different insurer responses and policy terms in perspective. Eligibility and decisions depend on the carrier’s criteria and the information it evaluates about the property. No single outcome should be assumed in advance.
As you compare options, focus on the written terms, including roof-related provisions, exclusions, deductibles, and the policy’s stated coverage. Consider how each option fits your priorities and timing, not only whether an application can proceed. If the insurer has provided a written decision, keep its stated reasons and dates in view while evaluating next steps.
For homeowners weighing options for homes deemed uninsurable due to roof age in Naples, an organized review can help turn uncertainty into specific questions and a clearer comparison. When you’re ready, review Florida home insurance options with your policy information and available roof records in hand.
Make Your Next Coverage Review More Informed
An older roof can raise questions, but one insurer’s decision doesn’t necessarily resolve every possible path. Reviewing the roof’s condition alongside its records, the written insurance notice, and the policy terms can help clarify whether to consider repairs, replacement, additional documentation, or another coverage review.
If you’re weighing options for homes deemed uninsurable due to roof age in Naples, Si Insurance Agency is an independent Florida agency serving communities across the state. It offers home insurance through a network of carriers, so you can compare available options while recognizing that eligibility and policy decisions rest with each insurer.
Bring your roof information and current policy details into the conversation. Review Florida home insurance options with Si Insurance Agency and take a clearer next step.
Frequently Asked Questions
Can I get homeowners insurance in Naples if my roof is old?
Yes, it may be possible, but an older roof can affect an insurer’s review. Carriers may consider its age alongside condition, materials, maintenance, and inspection information, and their criteria can differ. A decision about one application doesn’t necessarily determine every option. Si Insurance Agency is an independent Florida agency that compares home insurance options through its carrier network, while each insurer makes its own eligibility and policy decisions.
Does an older roof automatically make a home uninsurable in Florida?
No. Florida law generally prevents an insurer from refusing to issue or renew a policy solely because a roof is less than 15 years old. For a roof that is 15 years or older, a homeowner may obtain an inspection at their own expense; if it shows at least five years of remaining useful life, the insurer generally can’t refuse based on age alone. Roof condition and other underwriting factors may still affect a decision.
Will a roof inspection help me get homeowners insurance?
An inspection may help document visible condition and identify areas needing attention, providing useful information for an insurance review. It doesn’t guarantee acceptance, because the insurer determines what inspection information it will consider and how it applies to the property. If the roof is 15 years or older, an inspection may also be relevant under Florida’s roof-age law. Keep the report with other roof records for reference.
Should I repair or replace my roof before applying for home insurance?
Not automatically. First consider the roof’s documented condition, any unresolved damage, and the insurer’s written concern. A targeted repair may address a specific problem, while broader deterioration may lead you to evaluate replacement. Neither choice guarantees insurance acceptance. Compare the work under consideration with the policy or application timing and the insurer’s stated requirements. This helps distinguish necessary roof maintenance from steps intended to address an underwriting concern.
What roof documents should I gather for an insurance review?
Gather whatever records you have that help show the roof’s history and present condition. These may include installation or replacement information, permits, repair invoices, maintenance records, inspection reports, and dated photographs. Also keep the current policy and any written insurer notice or decision. These documents aren’t universal requirements, and a missing record doesn’t establish the roof’s condition. An organized file can make it easier to explain what’s known and identify unanswered questions.
Can Citizens Property Insurance Corporation insure a home with an older roof?
Possibly, depending on eligibility, roof details, and current requirements. Citizens generally serves homeowners unable to find private coverage or whose comparable private offer is more than 20% higher. Its roof guidelines call for documentation of full replacement for shingle roofs over 25 years old and certain other roof types over 50 years old, with an exception for documentation showing at least five years of remaining useful life. Confirm current criteria before relying on them.
What should I do if my homeowners insurance will not renew because of roof age?
Review the written notice and full policy first. Note the stated reason, policy dates, and any deadlines, and don’t assume an extension or renewal unless it’s confirmed in writing. Gather roof records and inspection information, then compare possible roof work with available insurance options and their written terms. If you’re exploring options for homes deemed uninsurable due to roof age in Naples, Si Insurance Agency can compare home insurance options across its carrier network. Each insurer makes its own coverage decision.
Comments