


Slide Insurance Takeout Offer Review vs. Independent Quote Florida (2026)
Could that official-looking letter from Citizens be a strategic opportunity, or is it a potential trap for your household budget? Receiving a depopulation notice often triggers a mix of confusion and legitimate concern regarding long-term financial stability. You've worked hard to secure your property, so it's natural to worry about premium spikes or whether a new carrier will actually show up when a claim is filed. This Slide Insurance takeout offer review vs independent quote Florida guide provides the analytical framework you need to decide whether to accept the offer or seek a tailored alternative.
The Florida market is shifting, with the Office of Insurance Regulation approving rate decreases for several carriers as recently as September 2026. While Slide Insurance maintains a Demotech A rating, their customer service reviews suggest that a simple premium comparison isn't enough to guarantee peace of mind. We'll examine the reality of the 20% rule, evaluate Slide's 2026 financial standing, and show you how to leverage current market stabilization to your advantage. You'll learn how to navigate this transition with the precision of a seasoned risk manager, ensuring your home remains protected by a carrier that aligns with your specific needs.
Table of Contents
Understanding the Citizens Depopulation Program and the Slide Takeout Offer
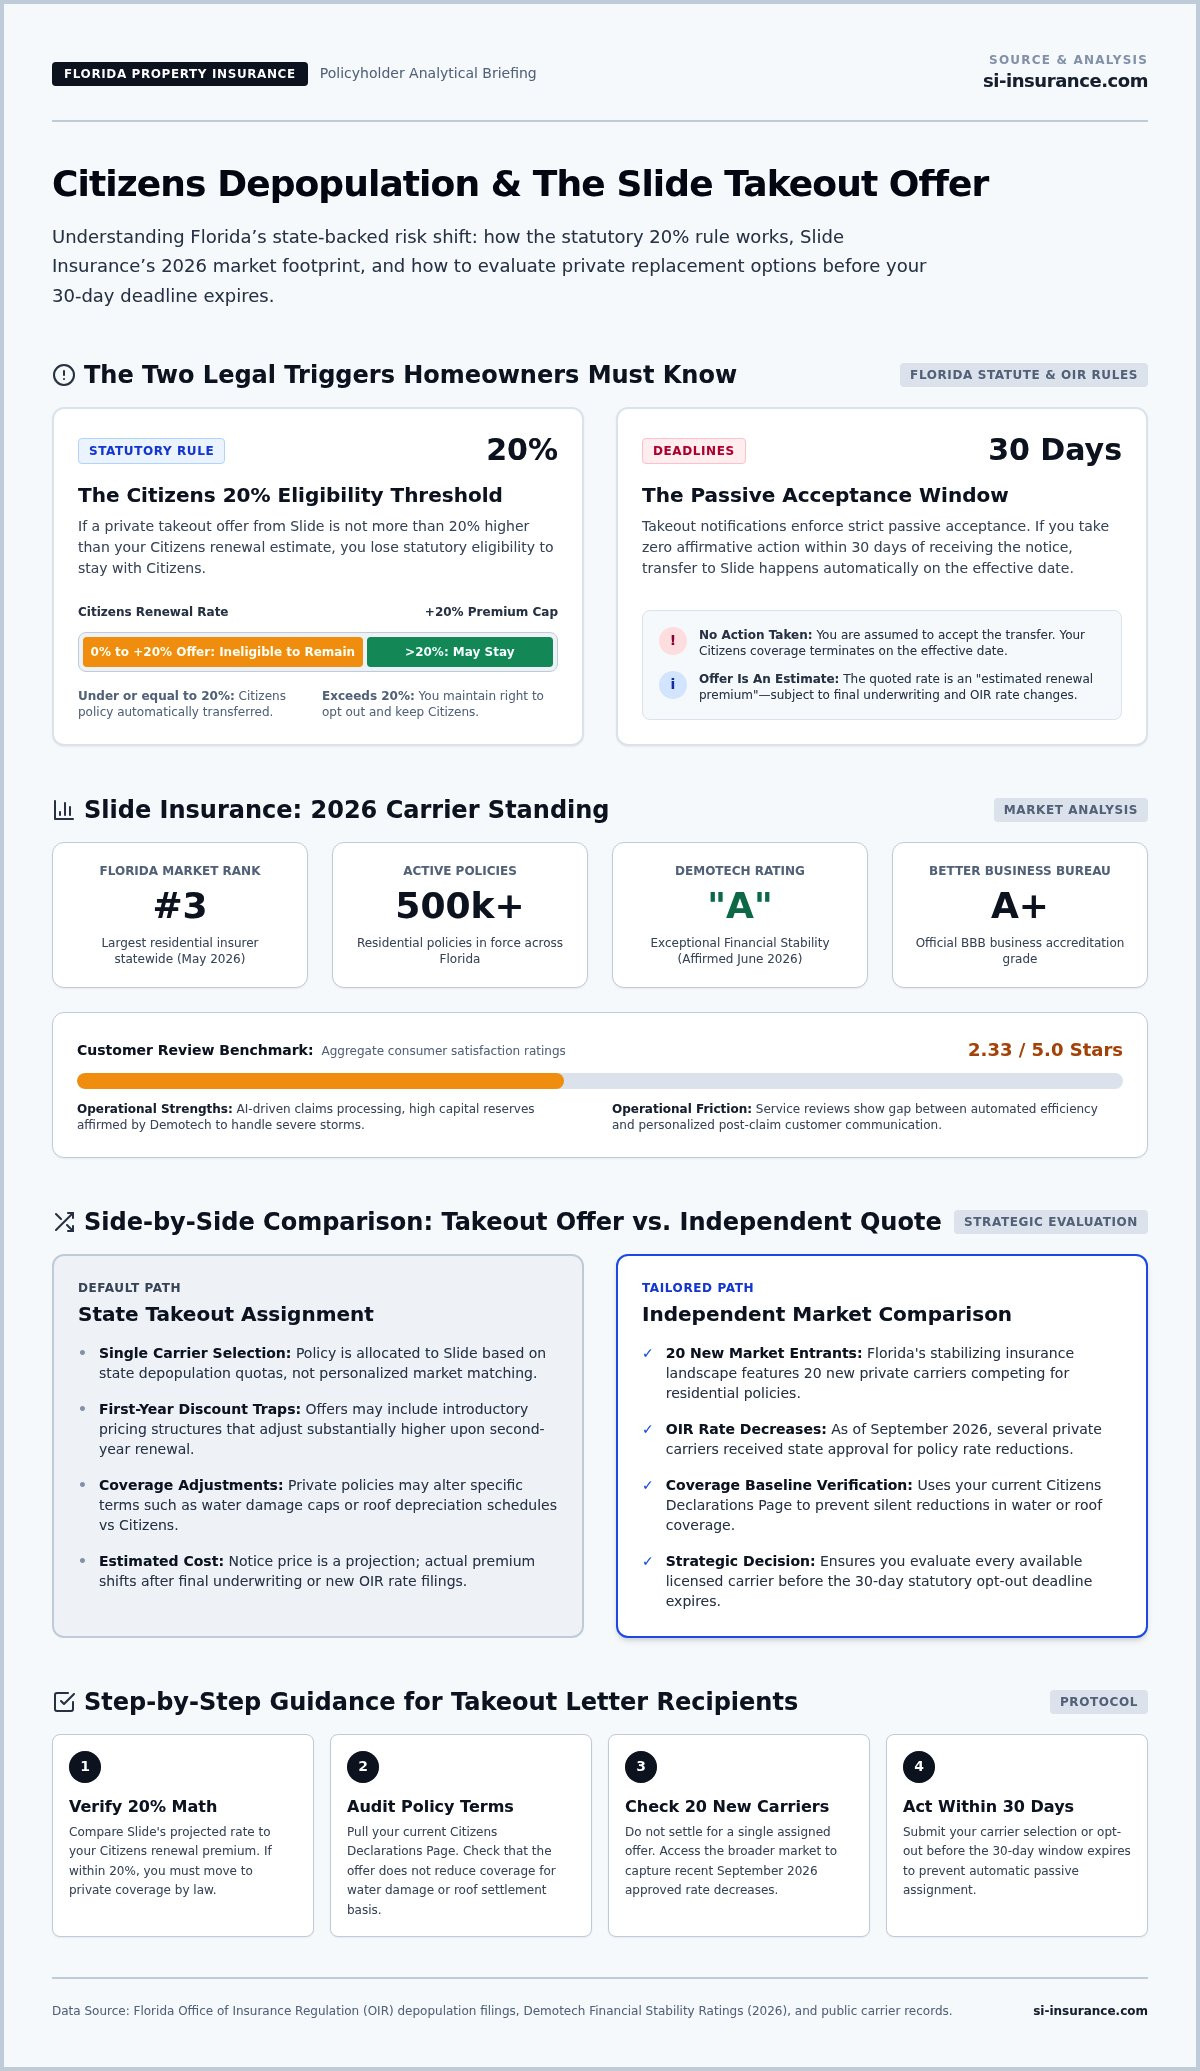
The Florida legislature and the Office of Insurance Regulation (OIR) utilize the depopulation program as a strategic mechanism to shift risk from the state-backed Citizens Property Insurance Corporation to the private market. This initiative isn't a sign of policy cancellation. Instead, it represents a calculated effort to reduce the state's total liability by moving eligible properties into the private sector. Slide Insurance has been selected as a primary takeout carrier for 2026, reflecting its rapid ascent to becoming the third-largest residential insurer in the state with over 500,000 policies in force.
When you receive a takeout notice, you'll see an "estimated renewal premium." It's vital to understand that this figure is a projection, not a fixed contract. The actual cost can fluctuate once the final underwriting is completed or if the OIR approves new rate filings. A comprehensive Slide Insurance takeout offer review vs independent quote Florida assessment is the only way to determine if this estimate aligns with the broader market's current pricing trends, especially as several private carriers have recently filed for rate decreases.
To better understand this concept, watch this helpful video:
Why Slide Insurance is Targeting Your Policy
Slide employs a sophisticated, data-driven underwriting methodology to identify high-value risks that complement their existing portfolio. They don't pick policies at random. Instead, they focus on specific criteria such as geographic distribution to avoid over-concentration in storm-prone zones and the age of the property's roof. The OIR carefully monitors these selections to ensure that Slide maintains its Demotech "A" rating, which signifies an exceptional ability to pay claims even after significant catastrophic events. Their goal is to build a stable, long-term book of business by acquiring well-maintained homes that meet their modern risk profile.
The Opt-Out Mechanism: Your Right to Choose
Homeowners have a strict 30-day window to respond to a takeout offer. If you don't take action, the state applies "passive acceptance," and your coverage will automatically transition to Slide on the effective date. However, simply opting out to stay with Citizens isn't always an option. Under Florida's 20% rule, if the Slide offer is not more than 20% higher than your Citizens renewal, you generally lose the right to remain with the state-backed insurer. This makes it imperative to contact an expert at SI Insurance to shop the market immediately. You need to know if a different private carrier offers superior coverage terms before your window of choice closes.
Slide Insurance Review: Financial Stability and Claims Reputation in 2026
Choosing between staying with a state-backed entity or moving to a private carrier requires a clinical look at the data. A Slide Insurance takeout offer review vs independent quote Florida analysis starts with understanding the carrier's rapid ascent. By May 2026, Slide became the third-largest residential insurer in Florida, managing over 500,000 policies. This scale allows them to leverage advanced artificial intelligence for claims processing, though the human element remains a point of contention. While they hold an A+ rating from the Better Business Bureau, aggregate customer reviews sit at approximately 2.33 out of 5 stars, highlighting a common friction point between automated efficiency and personalized service.
Financial resilience is the cornerstone of any Florida policy. In June 2026, Demotech affirmed Slide's Financial Stability Rating (FSR) of A, Exceptional. This rating indicates a robust ability to meet policyholder obligations even during catastrophic volatility. However, a high rating doesn't mean every policy is identical. You'll want to ensure your specific risk profile is managed by a team that understands these technical nuances. If you're feeling uncertain about the technicalities, you can consult with a specialist to verify these metrics against your specific property needs.
Financial Engineering and Reinsurance Strategy
Slide's stability isn't just about their internal capital; it's about their reinsurance structure. They've engineered a complex web of global reinsurance partnerships to offload extreme hurricane risks. This strategy is vital for the 2026 season, as it ensures they aren't wiped out by a single landfalling storm. A carrier's financial backbone matters far more than an introductory discount. If the reinsurance layer is thin, a low premium becomes a liability rather than a saving. Their focus on technology-driven underwriting helps them maintain this balance by avoiding high-risk clusters that could jeopardize their payout capacity.
Coverage Comparison: Citizens vs. Slide
Transitioning through the Citizens' Depopulation Program often reveals subtle coverage gaps. Citizens policies are standardized, but Slide may include specific endorsements or exclusions that alter your protection. Pay close attention to roof settlement terms. While many hope for replacement cost coverage, some private policies might shift toward actual cash value (ACV) for older roofs. These nuances can lead to thousands of dollars in out-of-pocket costs after a loss. Always compare the water damage limits and hurricane deductibles side-by-side to ensure the "comparable" coverage isn't actually a step down in quality. Check for differences in personal property limits and other structures coverage to get a true comparison.
Takeout Offer vs. Independent Quote: A Strategic Comparison
Accepting a state-mandated transition is often the path of least resistance, but for the sophisticated property owner, it's rarely the most cost-effective one. A takeout offer is essentially a pre-packaged solution, approved by the state to move volume quickly. In contrast, an independent quote is a bespoke risk assessment, tailored to your specific assets and liability requirements. Conducting a Slide Insurance takeout offer review vs independent quote Florida analysis reveals that the convenience of automated acceptance often comes at a high premium in the long term.
Strategic Comparison at a Glance:
Takeout Offer: Limited to one carrier; automated underwriting; potential for "teaser" first-year rates.
Independent Quote: Access to 20+ private carriers; customized coverage limits; human-verified mitigation credits.
The primary distinction lies in the methodology of selection. While the state facilitates the transfer to Slide based on broad data points, an independent agent at SI Insurance performs a comprehensive market sweep. This process ensures that your risk is not just placed, but strategically positioned with a carrier that offers the most favorable terms for your specific geographic and structural profile.
The Hidden Costs of Passive Acceptance
Passive acceptance carries significant financial risks that aren't immediately apparent in the initial letter. Automated transfers frequently fail to account for recent home improvements, such as a new secondary water resistance barrier or upgraded impact windows, which could drastically lower your costs. If these wind mitigation credits aren't manually verified, you'll likely overpay from day one. Renewal shock occurs when the introductory credits applied to a takeout policy expire, resulting in a sudden and substantial premium increase during the second policy term. Relying on an automated system means you're essentially gambling that the state's data is current, which is a dangerous assumption in Florida's fast-moving regulatory environment.
The Independent Advantage: A Global Market Sweep
Choosing the independent route transforms a transactional event into a consultative strategy. We don't just look at Slide; we evaluate their offer against dozens of other private insurers, many of whom have entered the Florida market in 2026 with aggressive pricing models. This approach also allows for sophisticated multi-line strategies, such as bundling your home and auto insurance to unlock deeper preferred-tier discounts. By leveraging our deep roots in Broward County and statewide expertise, we act as a protective guardian, ensuring that your transition out of Citizens results in enhanced security rather than just a different bill.
How to Evaluate Your Slide Offer: A Step-by-Step Guidance
Deciphering a state-issued transition letter requires a methodical approach to ensure your property remains adequately protected. This isn't just about a price tag; it's about the structural integrity of your financial safety net. To perform an effective Slide Insurance takeout offer review vs independent quote Florida analysis, you must first establish a clear baseline of your current risk profile. Follow these five tactical steps to regain control over your coverage trajectory.
Step 1: Locate your Citizens Declarations Page. This document serves as your baseline. It details your current coverage limits, deductibles, and any specific endorsements that have been tailored to your property over time.
Step 2: Scrutinize the 'Estimated Renewal Premium'. Look beyond the headline number on your Slide offer. This figure is a projection and often incorporates temporary credits that may not survive the transition to a full policy term.
Step 3: Initiate a market sweep. Contact a specialist to run a comparison quote across the broader market. With 20 new carriers entering Florida by May 2026, the competitive landscape has shifted significantly since your last renewal.
Step 4: Compare the fine print. Look for discrepancies in water damage sub-limits, hurricane deductibles, and roof settlement terms. A lower premium is a poor trade-off for a policy that moves from Replacement Cost to Actual Cash Value on your roof.
Step 5: Execute the opt-out. If the independent market sweep reveals a carrier with superior financial stability or better coverage terms, you must formally decline the Slide offer within the 30-day window.
If you're ready to see how your offer stacks up against the current market, you can request a strategic market sweep from our team today.
Checking Your Wind Mitigation Credits
Wind mitigation inspections are the primary engine for premium reduction in Florida. For 2026, many carriers, including Slide, are tightening their underwriting guidelines regarding roof age and secondary water resistance. If your inspection is more than five years old, it likely won't reflect recent upgrades like impact-rated windows or reinforced roof-to-wall connections. We manually verify that every eligible credit is applied to your independent quote, ensuring you aren't overpaying simply because of outdated data in the state's system. Slide's 2026 model heavily weights roof age, often requiring newer structures to qualify for their most competitive tiers.
Navigating the Citizens Opt-Out Portal
Declining a takeout offer is a time-sensitive technical process. You'll need to access the Citizens electronic opt-out portal using the unique offer code provided in your letter. It's vital to remember that "passive acceptance" is the default; if you don't act within 30 days, the transfer happens automatically. During this move, you can perform an 'Agency of Record' transfer. This allows you to keep your preferred independent consultant even if you move to a private carrier. This ensures you maintain a human-centric partnership rather than being managed by an automated state system. Don't let the clock run out, as a lapse in this decision-making window can lock you into a policy that doesn't fit your long-term goals.
Why SI Insurance is Your Strategic Partner in Florida
SI Insurance operates at the intersection of technical mastery and personalized advocacy. We don't just sell policies; we engineer risk management strategies that instill absolute security for high-value assets. In a marketplace flooded with automated letters, our role is to provide the professional validation needed to navigate your Slide Insurance takeout offer review vs independent quote Florida comparison. We prioritize intellectual confidence, ensuring that every recommendation is supported by rigorous analysis of current market stabilization trends and carrier solvency. You deserve a seasoned consultant who acts as a protective guardian for your financial interests.
Personalized Risk Mitigation in Sunrise and Pompano Beach
Algorithms used by large carriers often oversimplify the complex geography of Broward County. A home in Sunrise faces different hydrological risks than a property in Pompano Beach, yet a standardized takeout offer might treat them identically. Our local expertise allows us to account for specific flood zones and coastal proximity that automated underwriting might miss. This meticulous attention to detail extends to protecting high-value assets through specialized jewelry insurance and comprehensive asset protection. We believe in a human connection where your unique concerns are met with sophisticated, elite-level solutions that a direct-to-carrier model simply can't replicate.
Securing Your 2026 Renewal Strategy
The insurance landscape in 2026 is dynamic, with 20 new carriers introducing fresh capacity and increased competition to the Florida market. A direct-to-carrier model often leaves you vulnerable to premium volatility once introductory credits expire. As an independent partner, we monitor the market year-round to ensure your coverage remains optimal. Our deep roots in Broward County business insurance and personal lines provide us with a unique vantage point on regulatory shifts. We don't just react to takeout cycles; we proactively manage your portfolio to prevent premium spikes and coverage erosion. This long-term stability is the hallmark of a professional risk management approach.
Your Citizens depopulation letter is a signal to act, not just a document to file. We invite you to a personalized review where we'll dissect your Slide offer against the full spectrum of private market alternatives. Don't settle for a transactional transfer when you can secure a strategic partnership. Request a strategic comparison quote today to ensure your assets are protected by the best possible rate and terms for 2026.
Securing Your Property's Future with Intellectual Confidence
Your home is likely your most significant asset, so leaving its protection to an automated state process isn't just risky; it's unnecessary. We've explored the nuances of the Citizens depopulation program and why a carrier's financial stability rating matters more than an initial discount. A thorough Slide Insurance takeout offer review vs independent quote Florida assessment ensures you don't fall victim to "renewal shock" or hidden coverage gaps in your roof settlement terms. By analyzing your options now, you move from a position of uncertainty to one of strategic control.
Our team provides a sophisticated risk management approach backed by expert local knowledge of Broward County risk. We offer access to over 20 top-rated Florida carriers, giving you the elite-level perspective required to make an informed decision. Don't let a 30-day window dictate your long-term security. You can Request a Strategic Takeout Comparison from SI Insurance today to verify that your 2026 coverage is truly optimized. Taking this step today means you'll rest easier knowing your household is prepared for whatever the next season brings.
Frequently Asked Questions
What happens if I ignore the Slide Insurance takeout letter?
If you take no action within the specified 30-day window, your policy will automatically transition to Slide Insurance through passive acceptance. This means Citizens will transfer your risk on the effective date listed in your letter, and you'll be responsible for paying Slide's premium to maintain coverage. Ignoring the notice removes your ability to choose and can lock you into a policy that might not align with your long-term financial goals.
Is Slide Insurance a 'good' company compared to Citizens?
Slide Insurance is a financially viable private carrier that holds a Demotech Financial Stability Rating of A, Exceptional, as of June 2026. This rating indicates a robust ability to pay out catastrophic claims, whereas Citizens is a state-backed insurer designed as a market of last resort. However, Slide's aggregate customer service reviews are mixed, meaning a comprehensive Slide Insurance takeout offer review vs independent quote Florida evaluation is necessary to weigh financial stability against your service expectations.
Can an independent agent get a better rate than the Slide takeout offer?
Yes, an independent agent can often secure a more competitive rate or superior coverage terms by performing a comprehensive market sweep. With 20 new insurance companies entering the Florida market by mid-2026, competition has intensified significantly. We use this increased capacity to compare your Slide offer against multiple private carriers, ensuring you aren't limited to a single pre-packaged option that might overlook critical wind mitigation credits.
Why did Citizens choose Slide to take over my policy?
Citizens selected Slide because your property matches specific risk parameters established in Slide's data-driven underwriting algorithms. Private carriers look for balanced geographic distribution and specific structural characteristics, such as updated roof profiles, to complement their existing books of business. The Florida Office of Insurance Regulation approves these selections to systematically reduce the state's overall catastrophe exposure while moving stable risks back into the private market.
Will my mortgage company be notified if I switch from Citizens to Slide?
Yes, your mortgage company will be formally notified of the carrier change once the transition is finalized. If your insurance premiums are paid through an escrow account, the billing information will be automatically updated to ensure seamless payment processing. However, it's always a sound risk management practice to verify the change with your lender's insurance department to prevent any administrative delays or escrow calculation errors.
What is the deadline to opt-out of a Slide takeout offer in 2026?
The strict regulatory deadline to opt-out is exactly 30 days from the date printed on your Citizens depopulation letter. This timeline is non-negotiable under Florida Office of Insurance Regulation rules. Failing to submit your electronic opt-out through the Citizens portal within this window results in the automatic transfer of your coverage, making immediate consultation with an independent agent vital to exploring your market alternatives.
Does Slide Insurance cover flood damage in Florida?
No, a standard Slide homeowners policy does not cover rising ground water or storm surge damage. Like most traditional property insurance forms in Florida, flood protection must be purchased as a separate endorsement or through a standalone policy. Given the coastal and low-lying geography across Florida cities, matching your property with appropriate flood protection is a critical step we handle during our comprehensive market reviews.
How do I know if my Slide offer includes wind mitigation discounts?
You must review the premium breakdown page attached to your takeout offer to see which specific credits have been applied. Automated state transfers sometimes utilize legacy data that fails to account for recent structural upgrades. If your wind mitigation inspection isn't current, Slide's system may omit significant discounts, which is why we manually verify your inspection data during a professional market sweep.
Comments